
Shanghai Electric Secures First Overseas Heavy-Duty Gas Turbine Order for 500 MW Malaysian Project
Source: PR Newswire
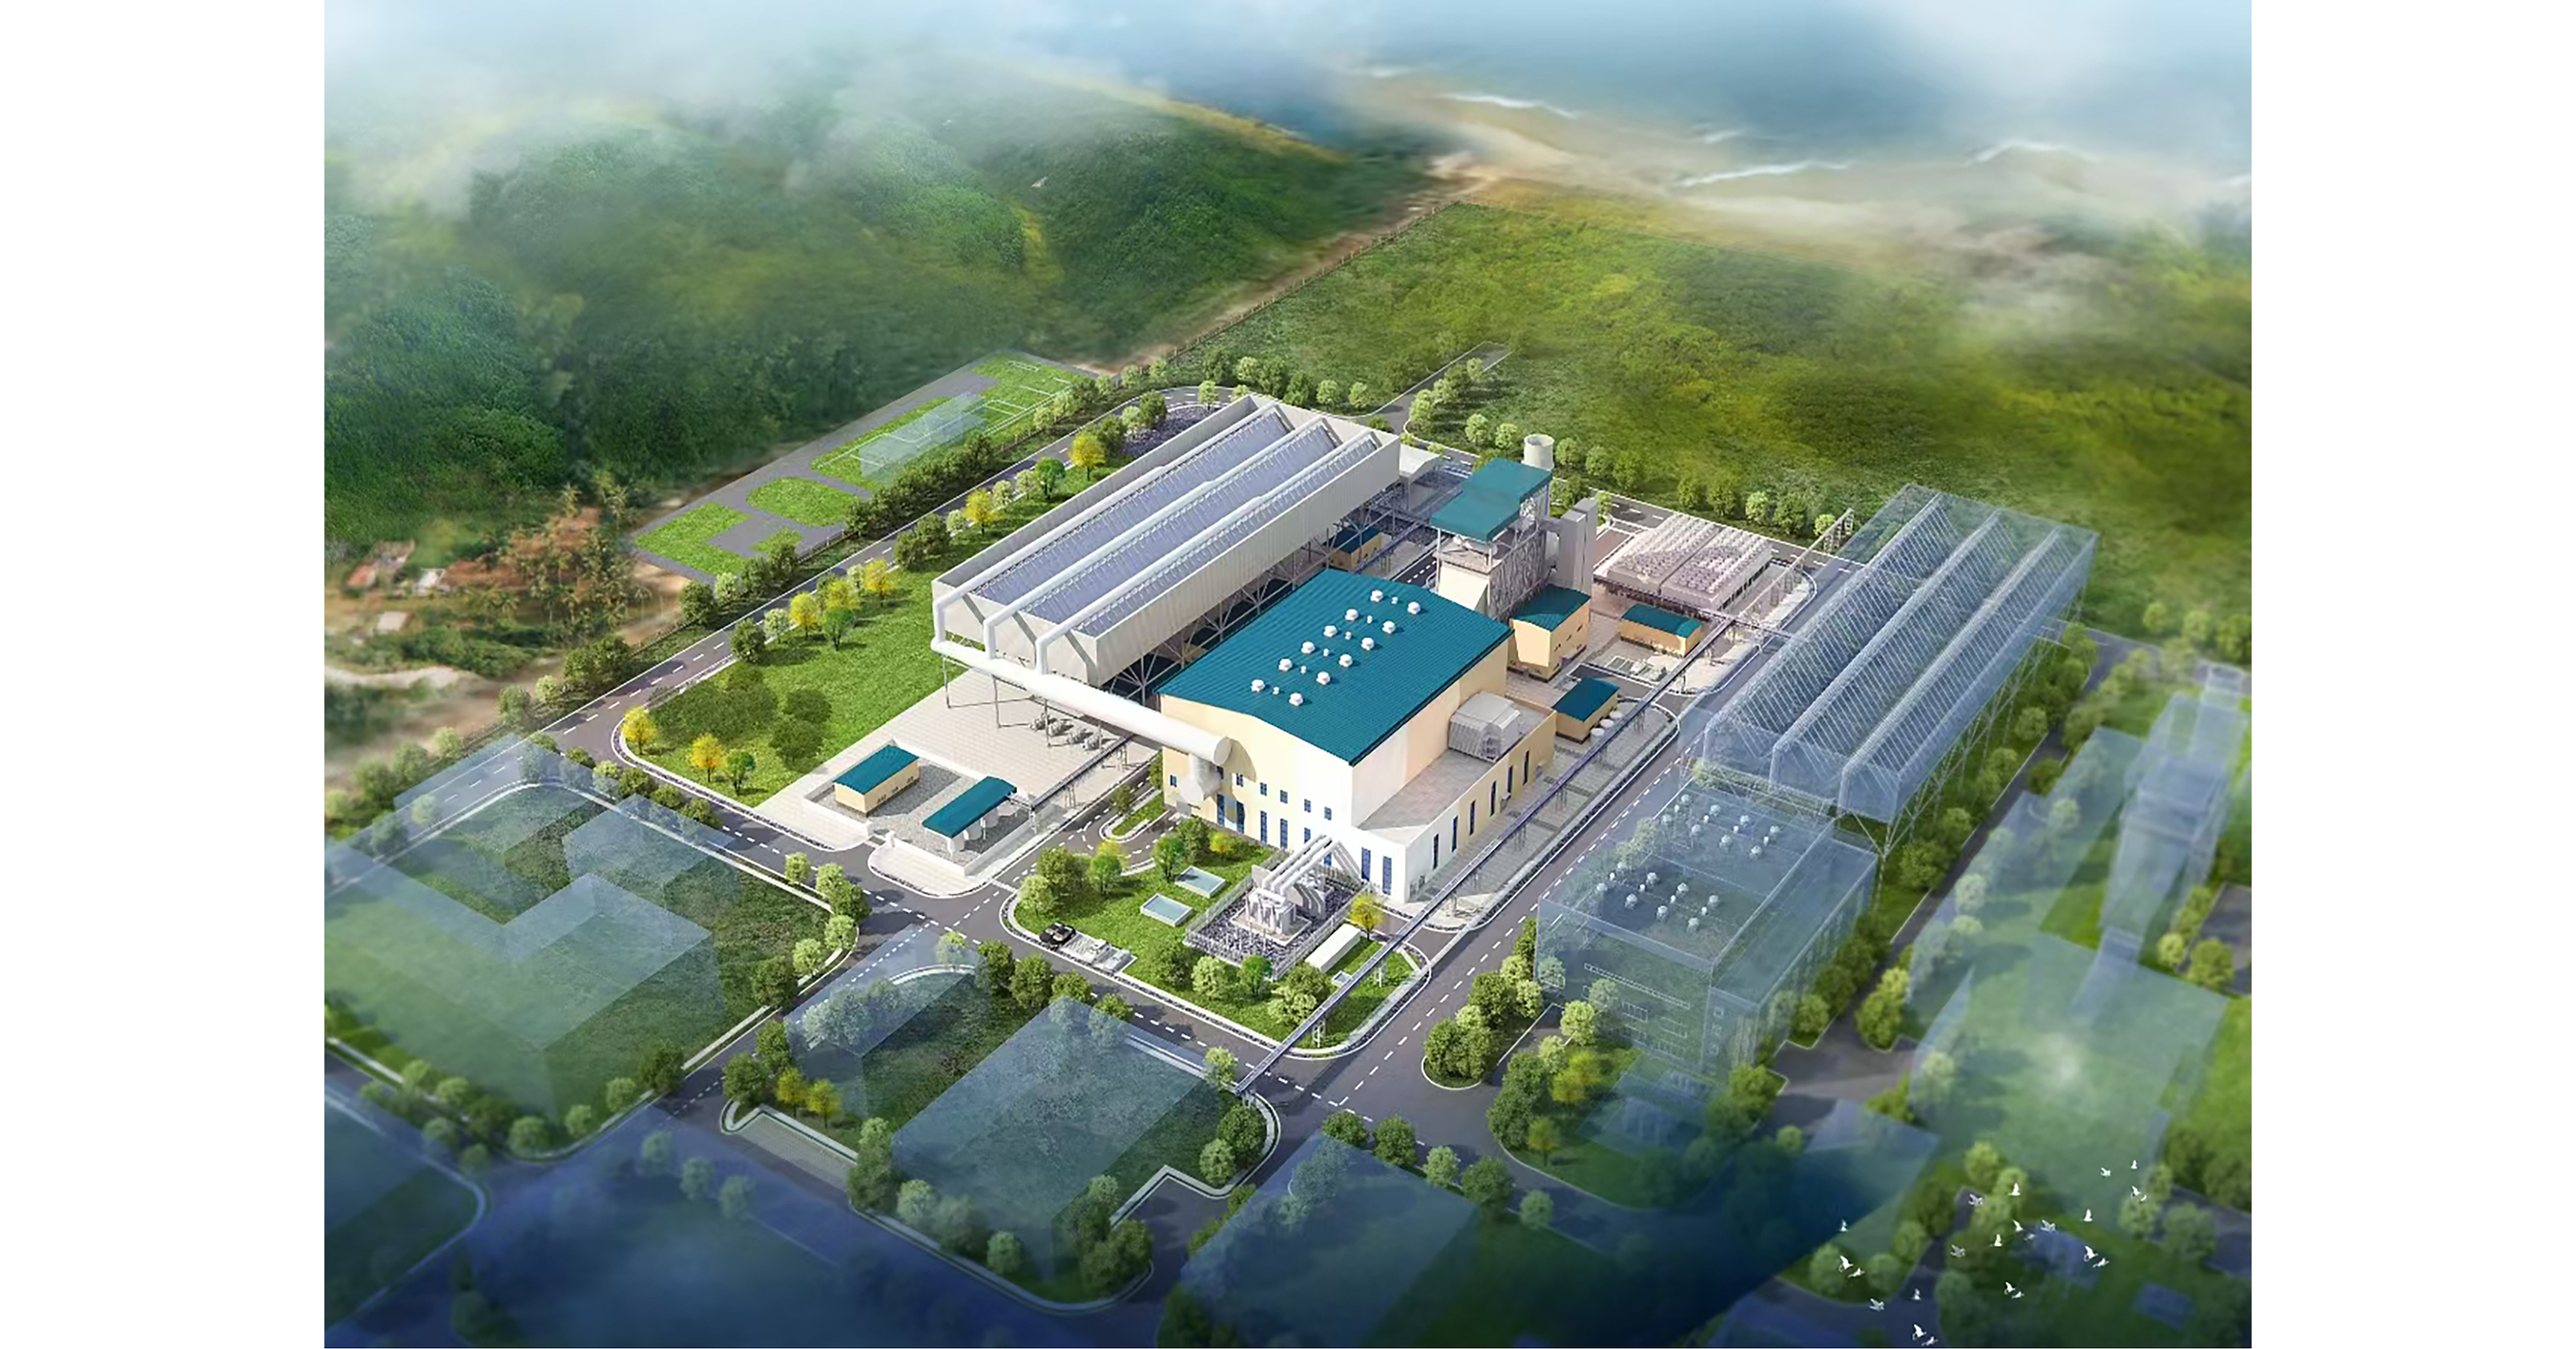
Shanghai Electric secured its first overseas heavy-duty gas-turbine order, winning the EPC contract for Unit 3 of Malaysia's Sarawak Samalaju CCGT project, with approximately 500 MW of capacity. The contract includes a 25-year long-term service agreement, allowing Shanghai Electric to provide all core equipment and maintenance across the plant life cycle. The company has delivered 103 heavy-duty turbine units totaling more than 21,000 MW of commissioned capacity and cited prospective demand from Indonesia, Thailand, the Philippines and Vietnam, with new-unit delivery capacity from 2028.
Analysis
The strategic read-through is less about near-term earnings and more about whether Chinese heavy-equipment suppliers can convert domestic turbine scale into export reference projects. A credible Southeast Asian operating reference could lower financing and perceived-performance barriers in markets where developers prioritize capex, delivery certainty and local-service commitments; that would pressure the lower end of GE Vernova (GEV), Siemens Energy (ENR.DE) and Mitsubishi Heavy Industries (7011.T) bidding economics rather than displace them immediately in premium markets.
For Shanghai Electric (601727.SS; 2727.HK), the economic value hinges on contract margin, advance-payment terms, performance guarantees and the service agreement's indexation—not the headline EPC value. Turnkey fixed-price projects can consume working capital and create material liquidated-damages exposure if commissioning slips. The manufacturer’s delivery claim and management’s service assumptions require validation through backlog disclosure, receivables movement, project gross-margin guidance and independent evidence of turbine availability after initial operation.
Over the next 1-3 months, the likely catalyst is further Southeast Asian order conversion, which would support a rerating from a domestic equipment story toward an export-platform narrative. Over 6-18 months, an installed base produces higher-quality aftermarket revenue only if the first units meet heat-rate and availability guarantees; a single high-profile outage would disproportionately damage export credibility. Consensus may underappreciate that gas-power additions are increasingly constrained by grid, LNG-import and project-finance availability, so expressions of interest should not be valued as backlog.
There is no compelling liquid direct trade solely from this announcement. The more actionable implication is to monitor whether Chinese export competition causes GEV/ENR.DE/7011.T to concede price or accept weaker service terms in ASEAN tenders; competitive damage would appear first in order-margin commentary, not in reported revenue.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.67
Key Decisions for Investors
- Place 601727.SS and 2727.HK on an export-backlog watchlist; consider a tactical long only after disclosed order economics, customer financing and payment milestones support positive operating-cash-flow conversion. Exit or avoid if receivables/inventory expand faster than backlog over the next two reporting periods.
- Maintain GEV, ENR.DE and 7011.T as relative-value shorts only upon evidence of ASEAN price concessions or reduced service-margin guidance; absent such evidence, this is not a recommended short because their installed bases and financing capabilities remain meaningful defenses.
- Monitor Malaysia and broader ASEAN LNG-import capacity, power-purchase agreements and project-finance approvals over 3-12 months. Delays in these inputs would falsify the assumed regional order pipeline before they affect turbine manufacturers' reported results.
- For a sector expression after verified follow-on awards, prefer long 601727.SS versus short a broad China industrial ETF rather than an outright long, isolating export-turbine optionality from domestic capex and broader China equity beta.
More News
- Trump says U.S. may keep Iranian oil 'like Venezuela' as Gulf-Iran Hormuz talks stall
- Baker Hughes sees no slowdown in energy projects despite higher rates as AI buildouts stoke LNG demand
- U.S. stock futures slide on calls to slow AI development, M.East escalation
- Diplomacy stumbles with postponement of meeting on Strait of Hormuz proposal
- Oil prices rise after Saudi Arabia shut down critical pipeline that bypasses Strait of Hormuz
- Z.ai shares tumble over 10% after $5 billion fundraising, its second major raise in two months