
National Franchise T.A.C.T. Celebrates Franchisee Feature in Esquire Magazine Highlighting Industry Excellence
Source: PR Newswire
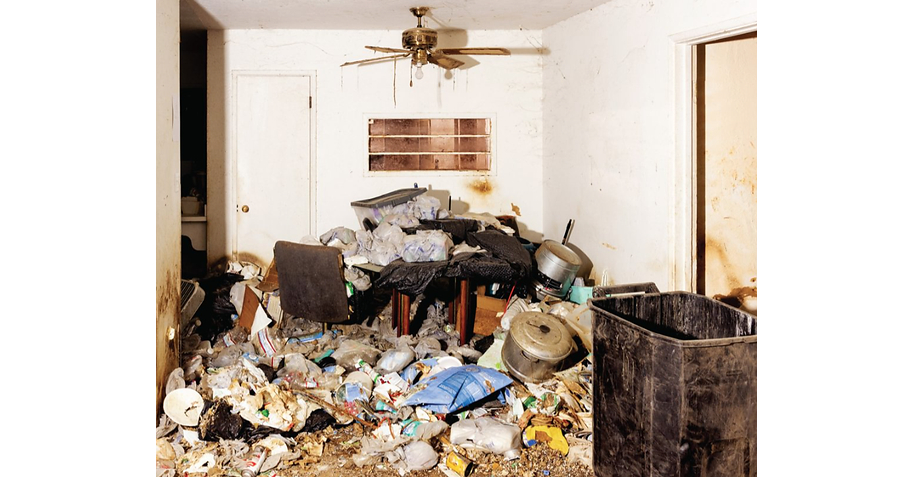
T.A.C.T., a national biohazard-remediation franchise, highlighted an Esquire profile of franchisee David Lesaffre and his multi-unit operations in Arizona and Texas. The company cited growing demand for biohazard and hoarding remediation and characterized its multi-billion-dollar market as recession-resistant, but disclosed no financial results, unit-growth figures, or forward guidance. The announcement is primarily a brand-building and franchise-recruitment update with limited investable market impact.
Analysis
This is non-investable private-company promotional content rather than evidence of a measurable change in remediation demand, unit economics, franchise openings, or insurance reimbursement rates. The near-term read-through for public markets is effectively nil; publicity may modestly improve franchisee lead generation, but it is unlikely to alter competitive positioning or sector earnings estimates over the next 1-3 months.
The only potentially relevant structural angle is that specialized remediation is a fragmented, labor-intensive services category with limited public-market exposure. If independent evidence emerges of accelerating insurance-funded claims, municipal outsourcing, or consolidation, likely beneficiaries would be facility-services and restoration platforms with adjacent capabilities, including ServiceMaster Brands (private), BELFOR (private), and FirstService (FSV) through property-services demand; however, T.A.C.T.'s disclosed information does not substantiate such a trend.
Consensus should resist assigning a "recession-resistant" multiple to the category without verified same-store revenue, franchisee closure, claims-frequency, labor-cost, and customer-acquisition data. Higher wage inflation, liability insurance costs, or reimbursement scrutiny could compress franchisee economics even if incident volume rises. No trade is warranted from this item alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate position: do not use this release as a catalyst for FSV or broader facility-services exposure; there is no public-company earnings linkage or independently verifiable demand data.
- Create a watch alert for public restoration/remediation comparables if quarterly disclosures show sustained organic growth above 5% alongside stable labor margins; that combination would support a 6-18 month consolidation thesis rather than a reaction to media coverage.
- For any future franchise-services investment, require evidence on unit-level EBITDA, franchisee churn, insurance reimbursement collection periods, and wage-cost trends before underwriting growth; deterioration in any of these metrics would falsify the defensive-demand narrative.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- How Pepsi fell behind in the cola wars—and then lost KFC
- 5 big analyst AI moves: ’Uniquely catalyst-rich’ months ahead for SpaceX
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Xencor reports phase 1 data for cancer drug XmAb819
- The experience economy keeps defying expectations. Maybe we’ve been looking at it all wrong
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check