
Queen Mary 2 to Make History in Liverpool on Landmark 500th Transatlantic Crossing as Cunard Unveils 93 New Voyages
Source: PR Newswire
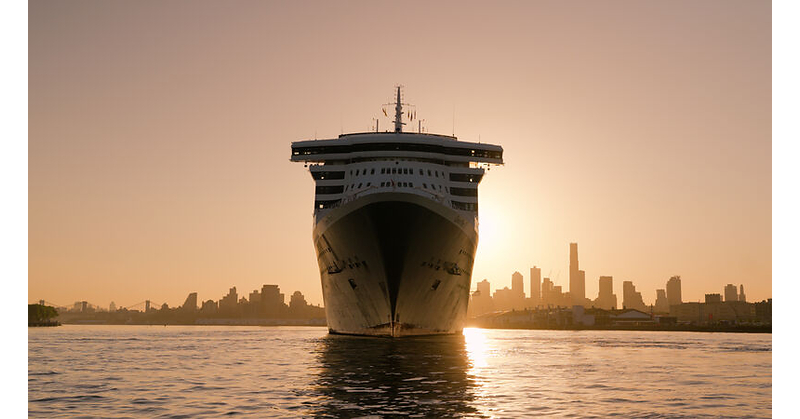
Cunard unveiled 93 voyages for October 2028–May 2029, covering 104 destinations in 49 countries, including Queen Mary 2’s 500th Transatlantic Crossing and Queen Elizabeth’s 115-night World Voyage. The program also features Queen Anne’s South America voyage during Rio Carnival and seven maiden port calls. Club-member bookings open November 3, 2026, general sales open November 4, and bookings by December 16 receive 10% introductory savings on Cunard Fare.
Analysis
This is a modest demand/merchandising signal for Carnival Corporation (CCL), not evidence of a step-change in consolidated earnings: the itinerary window is 2028–29, and the release provides no bookings, fare levels, occupancy, or capacity-growth data. The investable mechanism is whether distinctive long-haul and event-timed voyages support higher realized ticket prices and onboard spend without relying on heavier discounting. Overnight calls may improve itinerary appeal, but also shift time away from sea days and onboard spending; net economics need validation.
The 10% introductory saving is worth monitoring as a pricing signal, not proof of weak demand: it applies to bookings by a specified date and a particular fare type. Early booking uptake could improve forward visibility, but deposits this far ahead do not establish eventual yield or cancellation-adjusted demand. A competing risk is cost and execution exposure from long itineraries, port fees, fuel, and disruption around high-profile calls such as Carnival in Rio.
Near term, the November booking window is a sentiment catalyst; over 1–3 months, watch disclosed booking volume and pricing/yield commentary rather than press-release enthusiasm. Structural effects over 6–18 months are limited absent evidence that Cunard’s positioning changes fleet utilization or returns. Contrarian read: the rich itinerary narrative could be overvalued as a growth signal when the release may primarily repackage existing capacity. No standalone CCL trade is justified without measurable yield or booking data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Keep CCL on watch rather than trade the announcement. Reassess on company-reported booking trends, realized ticket prices/yield, and cancellation-adjusted deposits; the release does not quantify any of these.
- Treat the 10% offer as an alert for possible price sensitivity, not an automatic bearish signal. It would become more concerning if subsequent CCL commentary indicates broader discounting or weaker net yields.
- Falsify the demand-positive thesis if booking momentum fails to convert into stronger pricing/yield, or if management lowers guidance citing costs, itinerary disruption, or weaker premium demand. Conversely, evidence of sustained yield improvement would make the Cunard signal more relevant to CCL.
More News
- Meta put out an ambitious roadmap to Muse monetization after strong quarter and guide
- Sovereign wealth funds' China and Hong Kong investments surge 190% after a bruising slump
- Apple's iPhone Duo in short supply — plus, the 2 stocks fueling an AI rebound
- Billionaires fleeing California could turn a $30 billion tax windfall into a $39 billion loss, Stanford economists warn
- Capital One delivered a strong quarter. Why we're not declaring victory just yet
- Tesla stars Optimus robot production in California as profit falls 43%