
HDFC Bank’s Nifty Crown Under Threat From ICICI Bank After CEO Exit
Source: Bloomberg
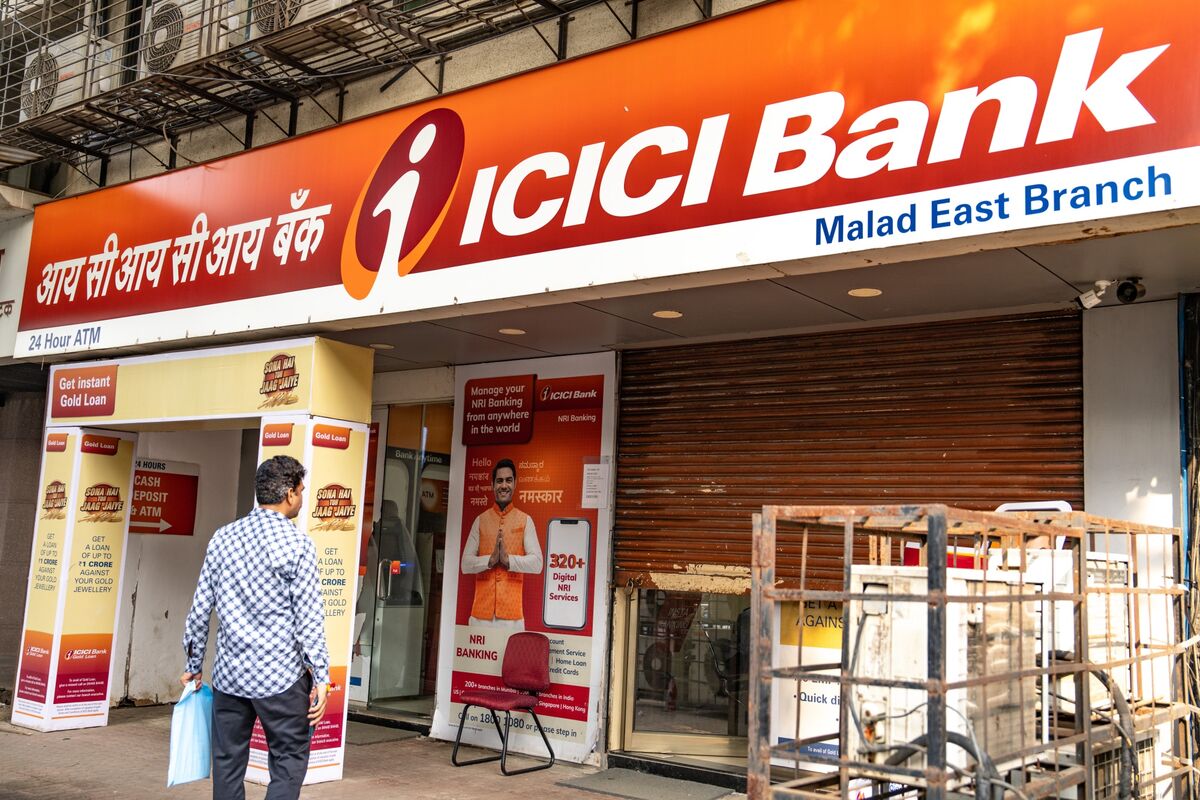
Nifty 50 slipped for a third straight session, falling below the 24,000 level as higher crude prices and a spike in global bond yields weighed on risk appetite. HDFC Bank’s influence in the benchmark is under pressure as ICICI Bank closes in following HDFC’s CEO exit headlines. On the FX front, the RBI has attracted about $127B of dollar deposits via its diaspora program (vs. a $80B+ target), strengthening its ability to defend the rupee even as elevated US yields could threaten foreign inflows.
Analysis
The market is likely to punish perceived governance slippage faster than earnings can re-rate it, which is why the bigger near-term impact is multiple compression at HDB rather than any immediate asset-quality issue. In a crowded, low-differentiation large-bank trade, leadership continuity is part of the product; when that breaks during a heavy integration phase, investors usually demand a discount before the P&L shows stress.
IBN is the cleaner relative beneficiary because it offers the opposite set of attributes: perceived execution consistency, less dependence on a single complex transition, and a better chance of attracting domestic institutional rotation if benchmark leadership shifts. The second-order effect is index-flow driven: once a stock becomes the clearer ‘default’ private-bank exposure, passive and semi-passive money can reinforce the gap even without a major fundamental revision.
The key horizon split is days versus months. Over the next few sessions this is mostly sentiment and flow; over 1-3 months the catalyst is successor credibility plus deposit growth, NIMs, and guidance. Over 6-18 months, the real question is whether HDB’s post-merger ROE ceiling is structurally lower than the market once assumed; if management steadies and operating data improve, the current discount should fade quickly.
Contrarian view: this could be an overreaction if investors are extrapolating a leadership event into a franchise impairment. HDB does not need a heroic CEO to avoid trouble, but it does need evidence that execution is not slipping versus peers. The thesis is falsified if the bank names a well-regarded successor and the next quarterly print shows deposit traction and stable margins; at that point the relative short should be covered.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.18
Ticker Sentiment
Key Decisions for Investors
- Put on a relative-value pair: long IBN / short HDB in equal dollar terms for a 1-3 month horizon; target 8-12% spread capture if the market continues to pay up for governance and execution quality.
- Avoid chasing standalone HDB downside after the first reaction; wait for the next quarterly deposit/NIM print. If HDB reclaims relative strength on improving operating metrics, cover any short exposure quickly.
- If already overweight Indian financials, rotate marginal capital from HDB into IBN rather than adding beta. This keeps sector exposure but improves expected return per unit of governance risk.
- Use HDB as a watchlist short only if the successor announcement disappoints or the next earnings update shows deposit growth lagging IBN by a meaningful margin; that is the cleaner catalyst than the headline itself.
More News
- Indian Shares Tumble On Rising Oil Prices, Bond Yields
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- Three Big Central Bank Decisions Loom: Evening Briefing Americas
- Treasury Yields Stay Elevated as Stocks Fall Before Fed
- Iran war has cost Pentagon $38 billion and depleted missile stockpiles, CBO says
- US Senate crypto bill collapses in blow to industry