
WhisperAI Reaches 145,000 Monthly Transcription Hours
Source: PR Newswire
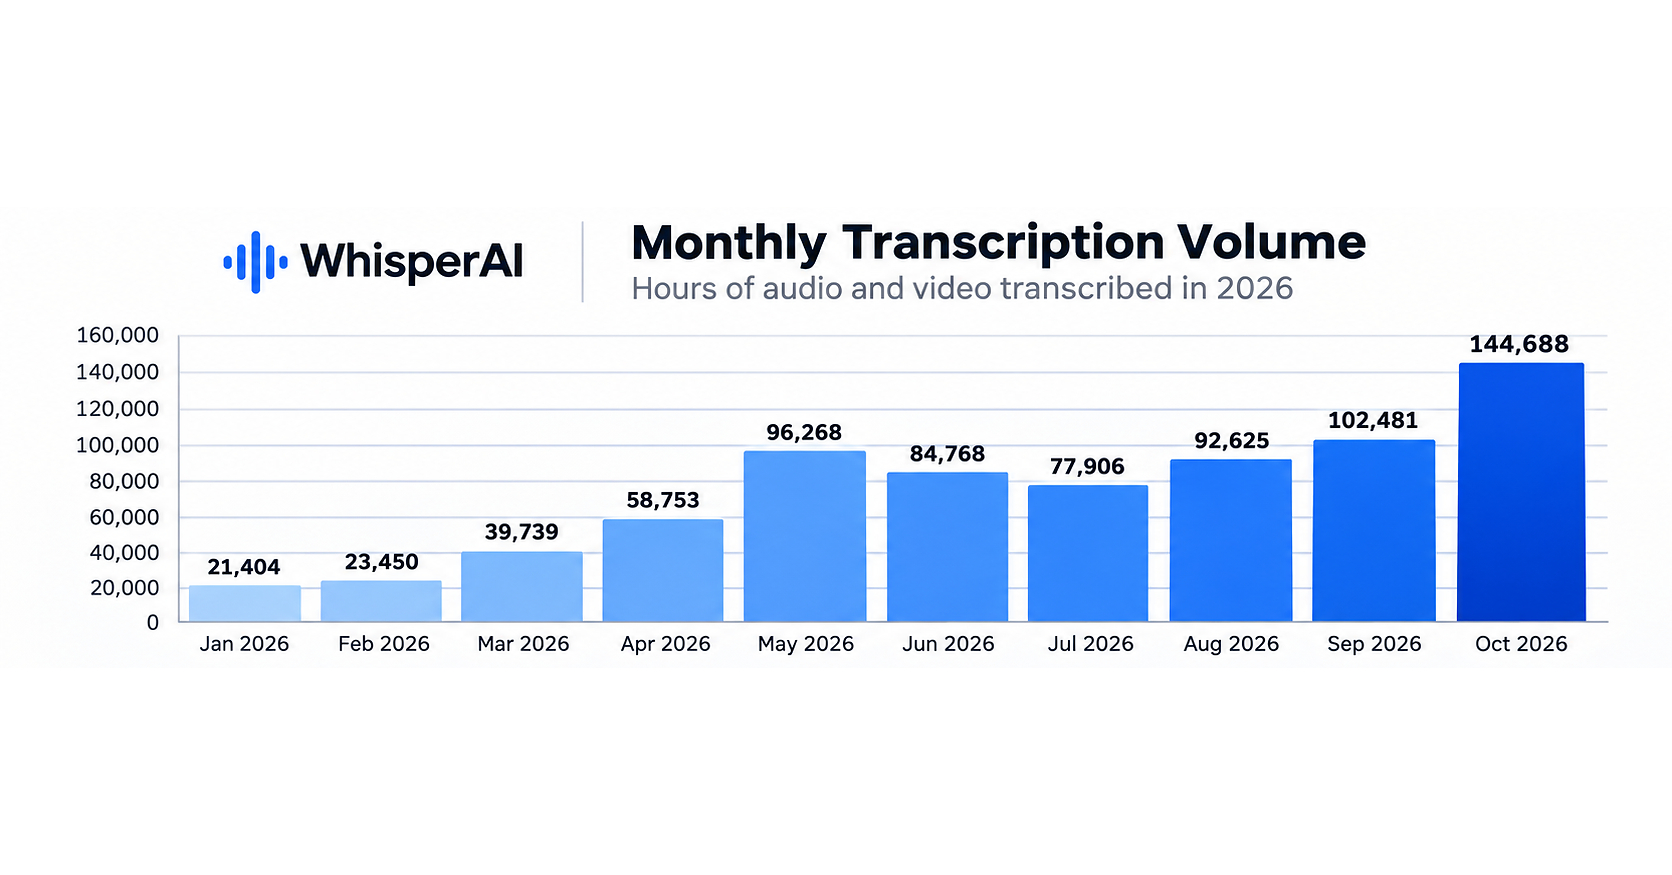
WhisperAI processed 144,688 audio and video hours in October, up 41% from September’s 102,481 hours and nearly sevenfold from 21,404 hours in January. The bootstrapped AI transcription company said it has attracted more than 460,000 users since launching in June 2025, with paying customers in over 125 countries. Recent workflow automation, AI integrations and meeting-assistant features support the reported growth.
Analysis
The investable signal is category economics, not WhisperAI equity: the company is private and the release provides no revenue, paid-user mix, retention, or inference-cost data. Audio volume can scale while gross profit does not, particularly if free usage or compute-intensive live features dominate. Treat the growth claim as a product-traction indicator, not evidence of attractive unit economics.
The more durable strategic point is workflow ownership. Automated ingestion and access through third-party AI assistants may increase switching costs and expand distribution, but also risk reducing WhisperAI to a replaceable transcription layer as Google, Microsoft, OpenAI, and Anthropic bundle speech and meeting features. Cloud and collaboration platforms could capture value if they control storage, identity, and the user interface; standalone transcription vendors may face pricing pressure. Privacy and consent requirements for recorded meetings are a potential adoption constraint, especially for enterprise customers.
Near term, this release is unlikely to move public-company earnings estimates. Over 1–3 months, watch for evidence that usage converts into paid seats/API revenue and that integrations improve retention. Over 6–18 months, competitive bundling and inference costs will determine whether independent vendors retain pricing power. The contrarian read: rising usage may signal category demand but could accelerate commoditization rather than create a durable moat. No standalone trade is justified without monetization or competitive displacement evidence.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No direct position: WhisperAI is not publicly listed, and the announcement does not establish revenue quality or profitability.
- Treat as a watch item for public cloud and productivity platforms, including Alphabet, Microsoft, and Zoom—not as an immediate catalyst. Reassess only if evidence shows measurable paid adoption, retention gains, or displacement of incumbent meeting tools.
- Track WhisperAI’s conversion from processing volume to paid customers/API revenue, gross margins after inference costs, and repeat usage. A slowdown in paid conversion or rising compute expense would falsify the bullish product-traction interpretation.
- Monitor enterprise privacy controls and major-platform bundling over the next 6–18 months; adverse regulation or free bundled substitutes would strengthen the commoditization thesis.
More News
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell-Lumentum Deal Puts Optical Networking at the Center of the AI Boom
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- AI Inference Startup Fal Raises Capital at $16 Billion Valuation