
Turkish Defense Firm Aselsan Extends Gains as BofA Says Buy
Source: Bloomberg
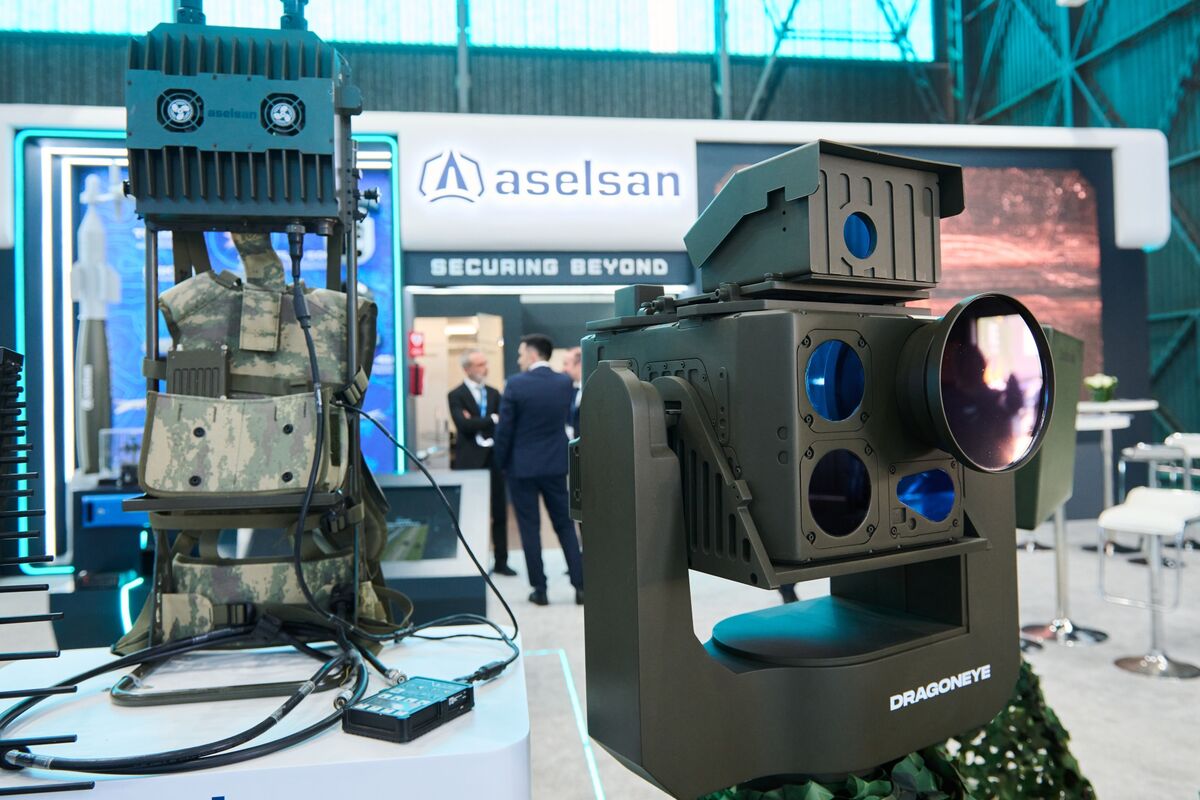
Aselsan shares climbed as much as 9.2% to 367.5 liras in Istanbul after BofA Securities issued a buy recommendation. The Turkish state-run defense contractor's year-to-date gain reached 58%, substantially outperforming the benchmark index's 8.4% advance.
Analysis
The relevant signal is not the recommendation itself but the emergence of an investable defense re-rating in a market where local liquidity, state ownership and limited foreign-float can amplify incremental institutional demand. A sustained valuation expansion would depend on evidence that export backlog converts into hard-currency revenue and that working-capital funding does not absorb the associated cash flow; headline order announcements alone are insufficient. The near-term risk/reward is unfavorable after a parabolic move unless daily turnover demonstrates that foreign participation—not domestic momentum accounts—is driving the bid.
Second-order beneficiaries are Turkish defense supply-chain companies with electronics, propulsion, aerospace and ammunition exposure, but the liquid global read-through is limited. European defense primes including Rheinmetall (RHM GR), Saab (SAAB SS), Leonardo (LDO IM), Thales (HO FP) and Hensoldt (HAG GR) remain more direct ways to express the broader European rearmament cycle, with deeper disclosure and lower country-risk premia. Conversely, Turkish sovereign-risk widening, further lira depreciation, capital-flow restrictions, or a deterioration in Ankara's external relations could compress the local equity multiple irrespective of operational execution.
Contrarian view: the market may be assigning a scarcity premium to a strategic asset before independently verifiable margins and free-cash-flow conversion justify it. Over the next 1-3 months, watch for order-book detail, export mix, receivables days, net debt/EBITDA and management guidance revisions. Over 6-18 months, the thesis becomes constructive only if foreign-currency exports outpace local-cost inflation and procurement funding remains durable; failure on either variable turns nominal revenue growth into an earnings-quality problem.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.52
Ticker Sentiment
Key Decisions for Investors
- No immediate directional position in Aselsan absent access to Istanbul liquidity and updated valuation, free-float and foreign-ownership data; treat a further sharp, low-volume advance as a momentum-risk alert rather than confirmation.
- For liquid defense exposure over 6-18 months, prefer a diversified basket long RHM GR / SAAB SS / LDO IM over a single Turkey-specific position; size modestly given already elevated sector expectations. Reassess if European order intake or FY guidance fails to support backlog-to-revenue conversion.
- If Aselsan reports accelerating export revenue with stable receivables and positive free-cash-flow conversion, consider a 1-3 month tactical long only after consolidation, with a hard stop on a break below the post-upgrade support level and profit-taking into renewed volume spikes.
- Monitor Turkish 5-year CDS, USD/TRY and local policy rates weekly. A material CDS widening or renewed lira stress would be a thesis falsifier for any Turkish defense equity exposure because discount-rate and capital-mobility risk can overwhelm contract momentum.
More News
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
- How Muse could be coming next for Apple's golden goose
- United Therapeutics CEO Martine Rothblatt disposes of $3.9m in stock
- RBC Capital raises Skyworks Solutions price target on deal approval
- Cantor Fitzgerald reiterates United Therapeutics stock rating after patent win
- Cantor Fitzgerald reiterates Nvidia stock rating on AI demand growth