
Intel's Recovery Has Moved From Survival To Factory Economics
Source: seekingalpha.com
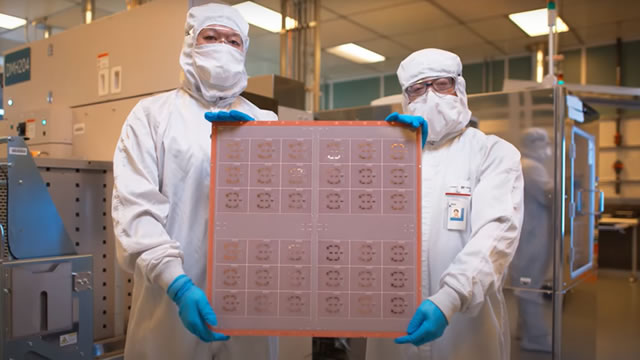
Intel is assigned a speculative Buy rating based on potential upside if competitive processor growth and manufacturing-yield improvements drive earnings growth faster than sales. The investment case depends on improved factory economics and maintaining or expanding high-margin server processor share, while advanced packaging could add incremental revenue. Sustainable profitability is viewed as primarily dependent on Intel's internal execution rather than external foundry or packaging customer wins.
Analysis
Near term, the stock can rally on any evidence of a gross-margin trough and credible management commentary on yield learning, making upside potentially sharper than revenue growth alone. Over the next 1-3 months, earnings guidance, server-share disclosures, and capex/free-cash-flow commentary are the key catalysts; over 6-18 months, the thesis depends on whether new nodes reach volume production without another schedule slip. The bullish case is falsified by renewed gross-margin deterioration, a material increase in capex without a corresponding foundry-customer commitment, or continued server-share losses to AMD despite new product availability.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- Keep INTC on a tactical long watch rather than establish a full fundamental position before the next earnings release; initiate only if management guides to sequential gross-margin improvement and reiterates node-volume timing. The upside setup is operating-leverage driven, but a guidance miss would likely reprice both earnings power and execution credibility simultaneously.
- Express the competitive CPU view as long AMD / short INTC over the next 1-3 months if Intel cannot provide independently measurable yield, cost, and server-share milestones. This pair reduces broad semiconductor-beta exposure; exit if Intel reports material server-share stabilization and a clear gross-margin inflection.
- For a higher-risk event expression, consider defined-risk INTC call spreads dated 3-6 months beyond the next earnings report only after checking implied volatility and strike skew. The trade requires enough time for product and manufacturing evidence to emerge, while limiting loss if the market again discounts execution promises.
- Monitor Intel quarterly gross margin, Data Center revenue/share trends, capex-to-revenue, free cash flow, and any disclosed external foundry commitments. Treat packaging revenue claims as non-thesis-confirming until they demonstrate margin contribution and repeat customer volume.
More News
- Synopsys, Amazon Web Services sign chip design licensing deal worth more than $1 billion
- +35%, +33%: AI chip and infrastructure stocks cap a blockbuster Sep, here’s why
- Spectre bug is back, this time to haunt JIT engines
- Wall Street is closing out a strong quarter. Plus, Lilly's mixed obesity drug trial data
- Six tech and healthcare picks up 18%–32% this month - the leader is up 34%
- South Korea’s exports hit record high on AI boom