
NonPublic delivers over 10x return on SpaceX investments for early investors
Source: PRWeb
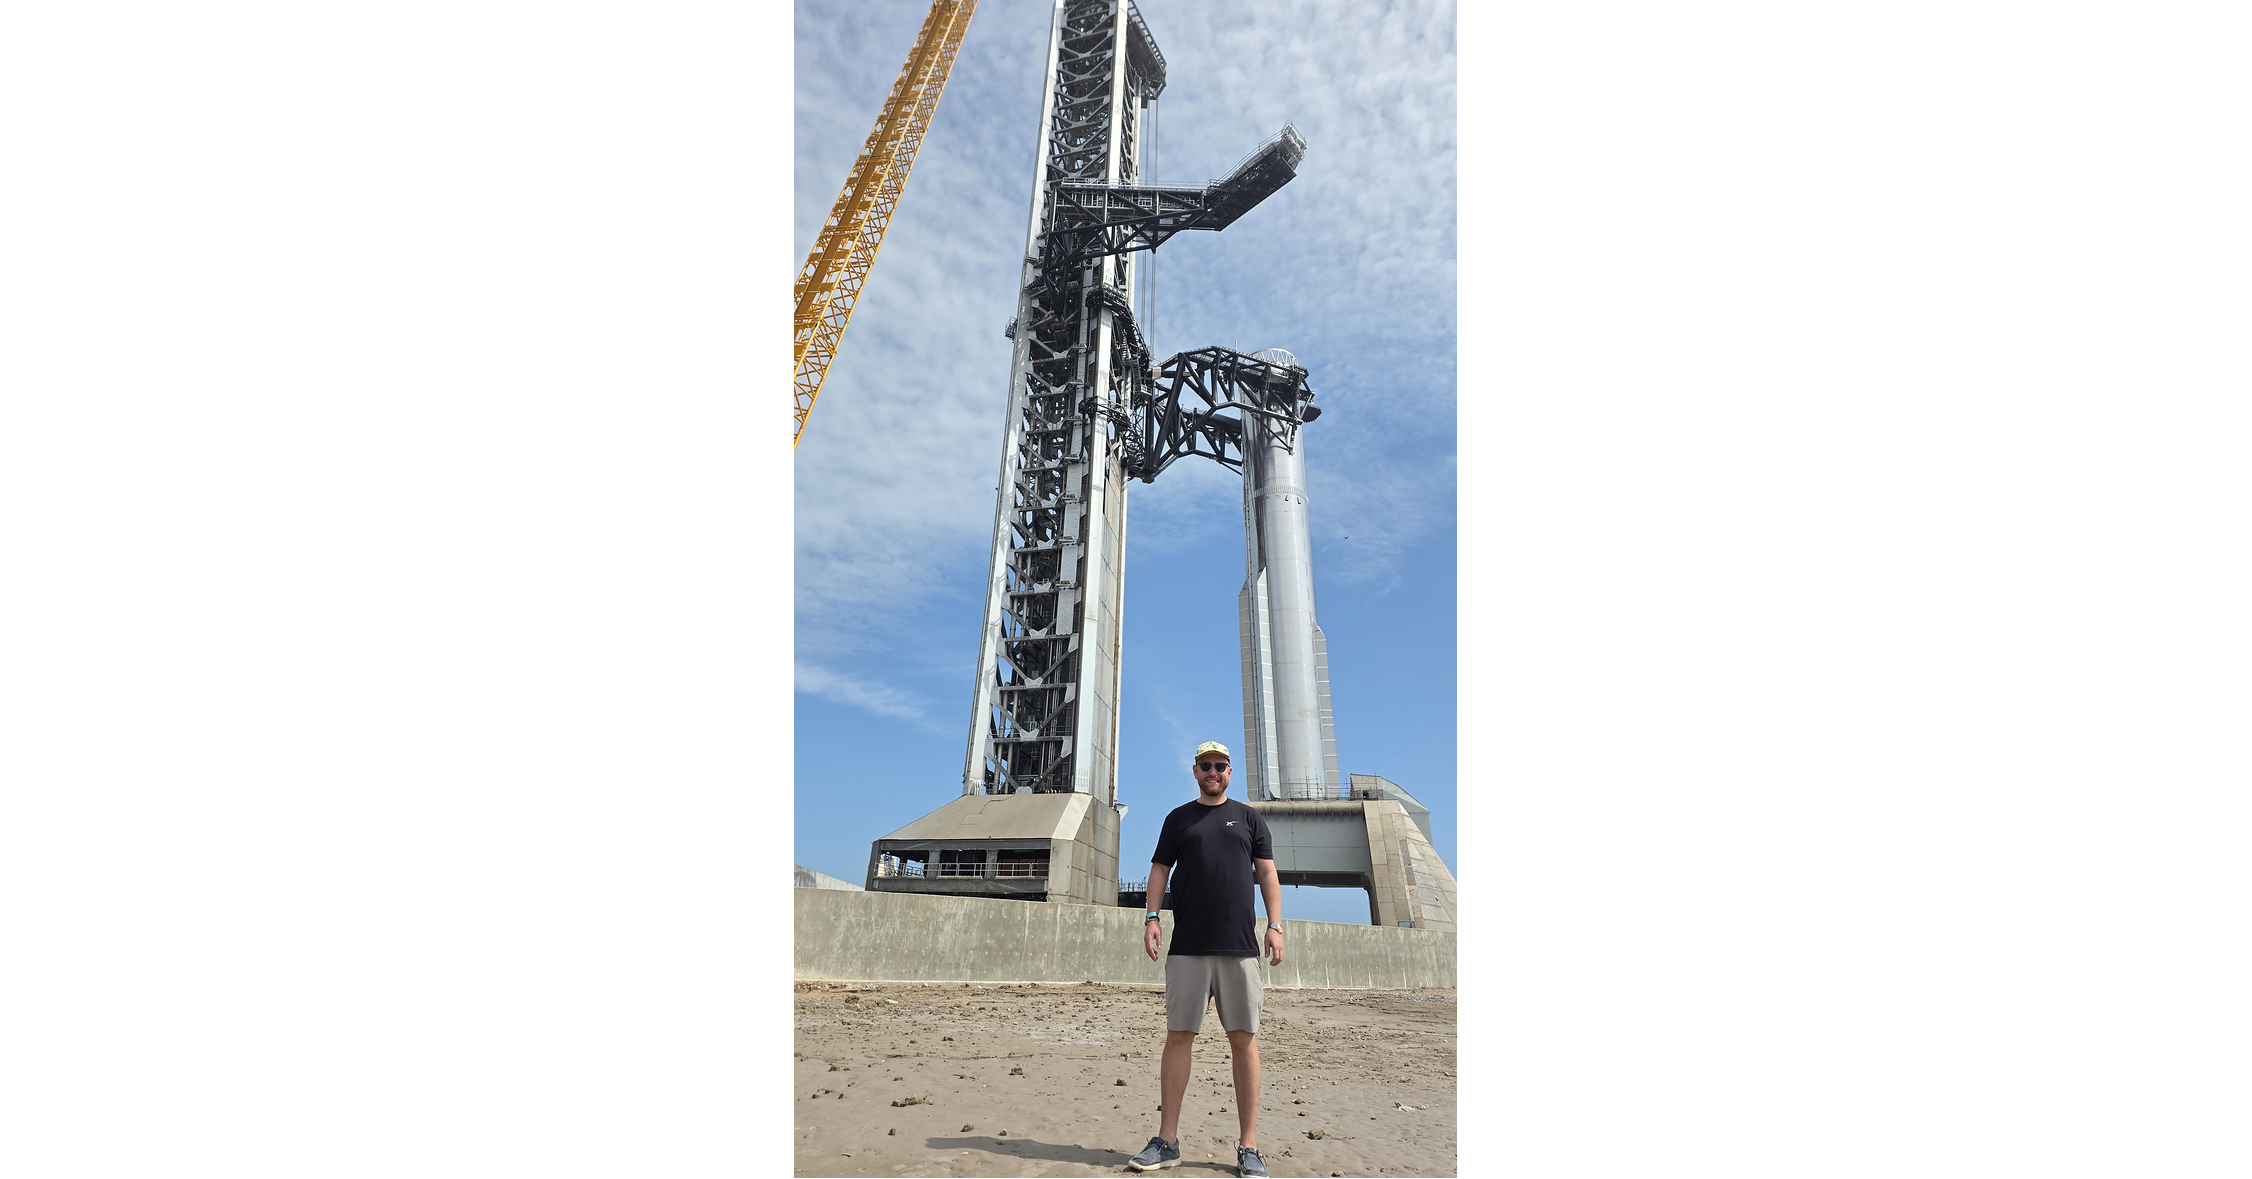
NonPublic said early investors delivered over a 10x return through 14 pooled vehicles covering SpaceX (and xAI into SpaceX), converting US$4.4M of investor capital into ~US$16M at the IPO price and ~US$24M at the June peak (before fees). SpaceX’s valuation rose to a peak of US$2.6T after what it calls the biggest IPO in history, and the stock surged 67% above the IPO valuation within days. The piece emphasizes that an SPV structure enabled eligible Australian wholesale investors to access US private placements despite typical SEC/qualified-purchaser and deal-size constraints.
Analysis
The investable signal here is not the trophy valuation; it is the migration of upside into the private phase of the cycle. That structurally favors secondary-liquidity venues, private-market administrators, and platforms that intermediate accredited capital, while making public-market IPO investors more dependent on what is left after the value creation has already been harvested. In other words, the winner is less the issuer than the infrastructure around access and liquidity.
Near term, this kind of announcement is more likely to change sentiment than fundamentals. The risk is reflexive: glossy returns can pull incremental capital into private vehicles just as dispersion between mark-to-model and realizable exit value is widening, especially if one or two marquee holdings reset lower. The real 1-3 month catalyst is hard evidence of monetization — secondary turnover, fund inflows, or fresh pre-IPO allocations — not PR-driven headlines.
The contrarian read is that the article extrapolates one exceptional outcome into a regime shift. Most late-stage private assets do not compound in a straight line into public-market premiums; once lockups, disclosure, and index inclusion hit, a lot of paper gains get repriced. That argues for caution on promotion-sensitive proxies and for waiting for observable cash-flow or transaction data before underwriting a durable private-markets boom.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No direct trade in AIKO on this headline; treat it as sentiment beta only and avoid chasing. Reassess only if the company has measurable exposure to private-market flows or secondary liquidity.
- Tactical pair for 1-3 months: long FRGE / short IPO if private-market enthusiasm translates into real secondary volume. Target 15-20% relative outperformance; stop if FRGE volumes and AUM fail to inflect by next quarter.
- Watch NDAQ as a delayed beneficiary, but only buy on a pullback if IPO issuance data improves. Falsify the thesis if next earnings show flat fee revenue and no pickup in listing activity.
- If expressing the theme, use call spreads rather than outright longs in high-beta innovation proxies over 6-12 weeks; the upside is sentiment-driven, but reversal risk is high if private markups cool.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Analyze SEC Filings With AI: A Verification-First Guide
- AI for IR Street Intelligence: Notes, Estimates, and Peers