
BOXABL Announces Multiyear Purchase Agreement with National Multifamily Developer LC Vegas Acquisitions, LLC for Up to 1,500 Homes
Source: PR Newswire
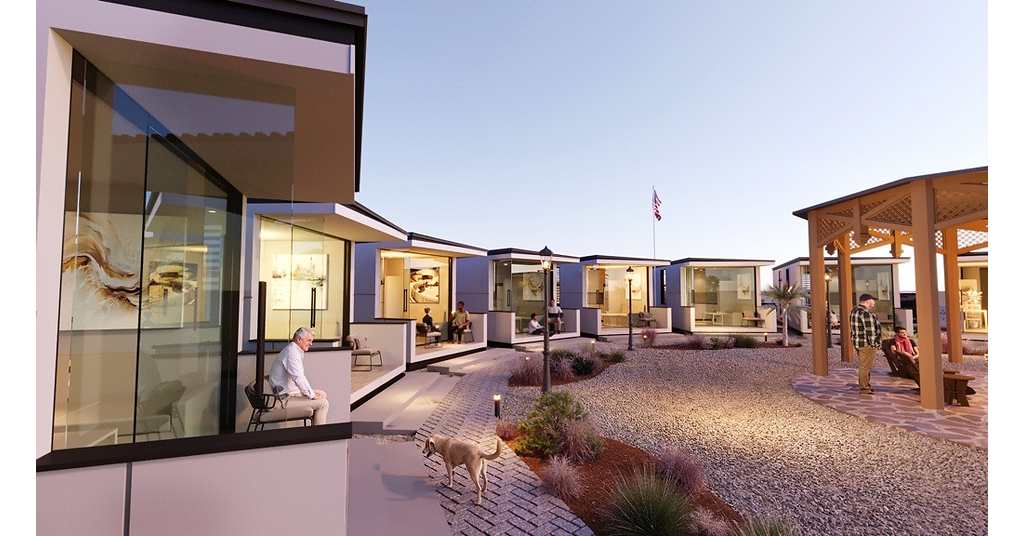
BOXABL (Nasdaq: BXBL) announced a multiyear purchase agreement for up to 1,500 homes over three years with LC Vegas Acquisitions, implying ~500 homes per year on a phased basis, subject to site readiness and regulatory approvals. The company framed this as its largest announced residential purchase arrangement to date, supporting scalability of its factory-built housing platform. However, purchases are conditional and there’s no assurance all units will be bought, manufactured, or delivered, which limits near-term certainty for revenue timing.
Analysis
This is more financing optionality than fundamental confirmation. For BXBL, the market should treat the announcement as a call option on conversion: the stock can re-rate on momentum if management later shows deposits, bookings, and installed revenue, but absent that, the economic value is still highly contingent on site readiness, approvals, and customer follow-through. The near-term winner is sentiment and potentially capital-access; the real loser would be anyone underwriting the story as if it were already backlog.
Second-order, the message is more important than the unit count: if a larger, better-capitalized developer is willing to pilot factory-built product at scale, that improves the probability that modular housing moves from novelty to a credible procurement channel for land developers. Over 6-18 months, that could pressure labor-intensive homebuilders and elevate interest in industrialized housing inputs, but only if BXBL proves repeatable margins and working-capital discipline. The key falsifier is weak conversion in the next two filings: if revenue, gross margin, or cash burn don’t improve despite headline agreements, the equity is likely just trading on promotional elasticity.
Contrarian view: the consensus may be underestimating how little of a press-release purchase agreement translates into EBITDA. In microcap housing names, the gap between stated demand and shippable demand is usually the whole story; the price can overshoot on narrative, then mean-revert when execution timelines slip. The most likely regime is a short-lived squeeze, not a durable rerating, until the company proves it can manufacture, deliver, and collect at scale.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Do not chase BXBL on the headline; treat as a watch item until the next filing shows booked revenue, deposits, and gross margin conversion. Near-term upside is mostly sentiment-driven, while downside re-opens quickly if delivery timing slips.
- If BXBL gaps materially higher and borrow remains tight, consider a small tactical fade after the first 1-2 sessions of volume exhaustion; the risk/reward is better for shorting hype than underwriting a multi-year operating story without proof.
- Set an alert on BXBL’s next 10-Q/8-K for: customer deposits, backlog recognition, and cash burn per delivered unit. A clean inflection there would be the first point to reassess a long; absent it, the trade remains promotional rather than fundamental.
More News
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes