
GLOBAL HOTELIER DANIEL SHAMOON PARTNERS WITH ORANGE LIMITED TO DEVELOP LUXURY BOUTIQUE RESORT AT PEARNS POINT IN ANTIGUA
Source: PR Newswire
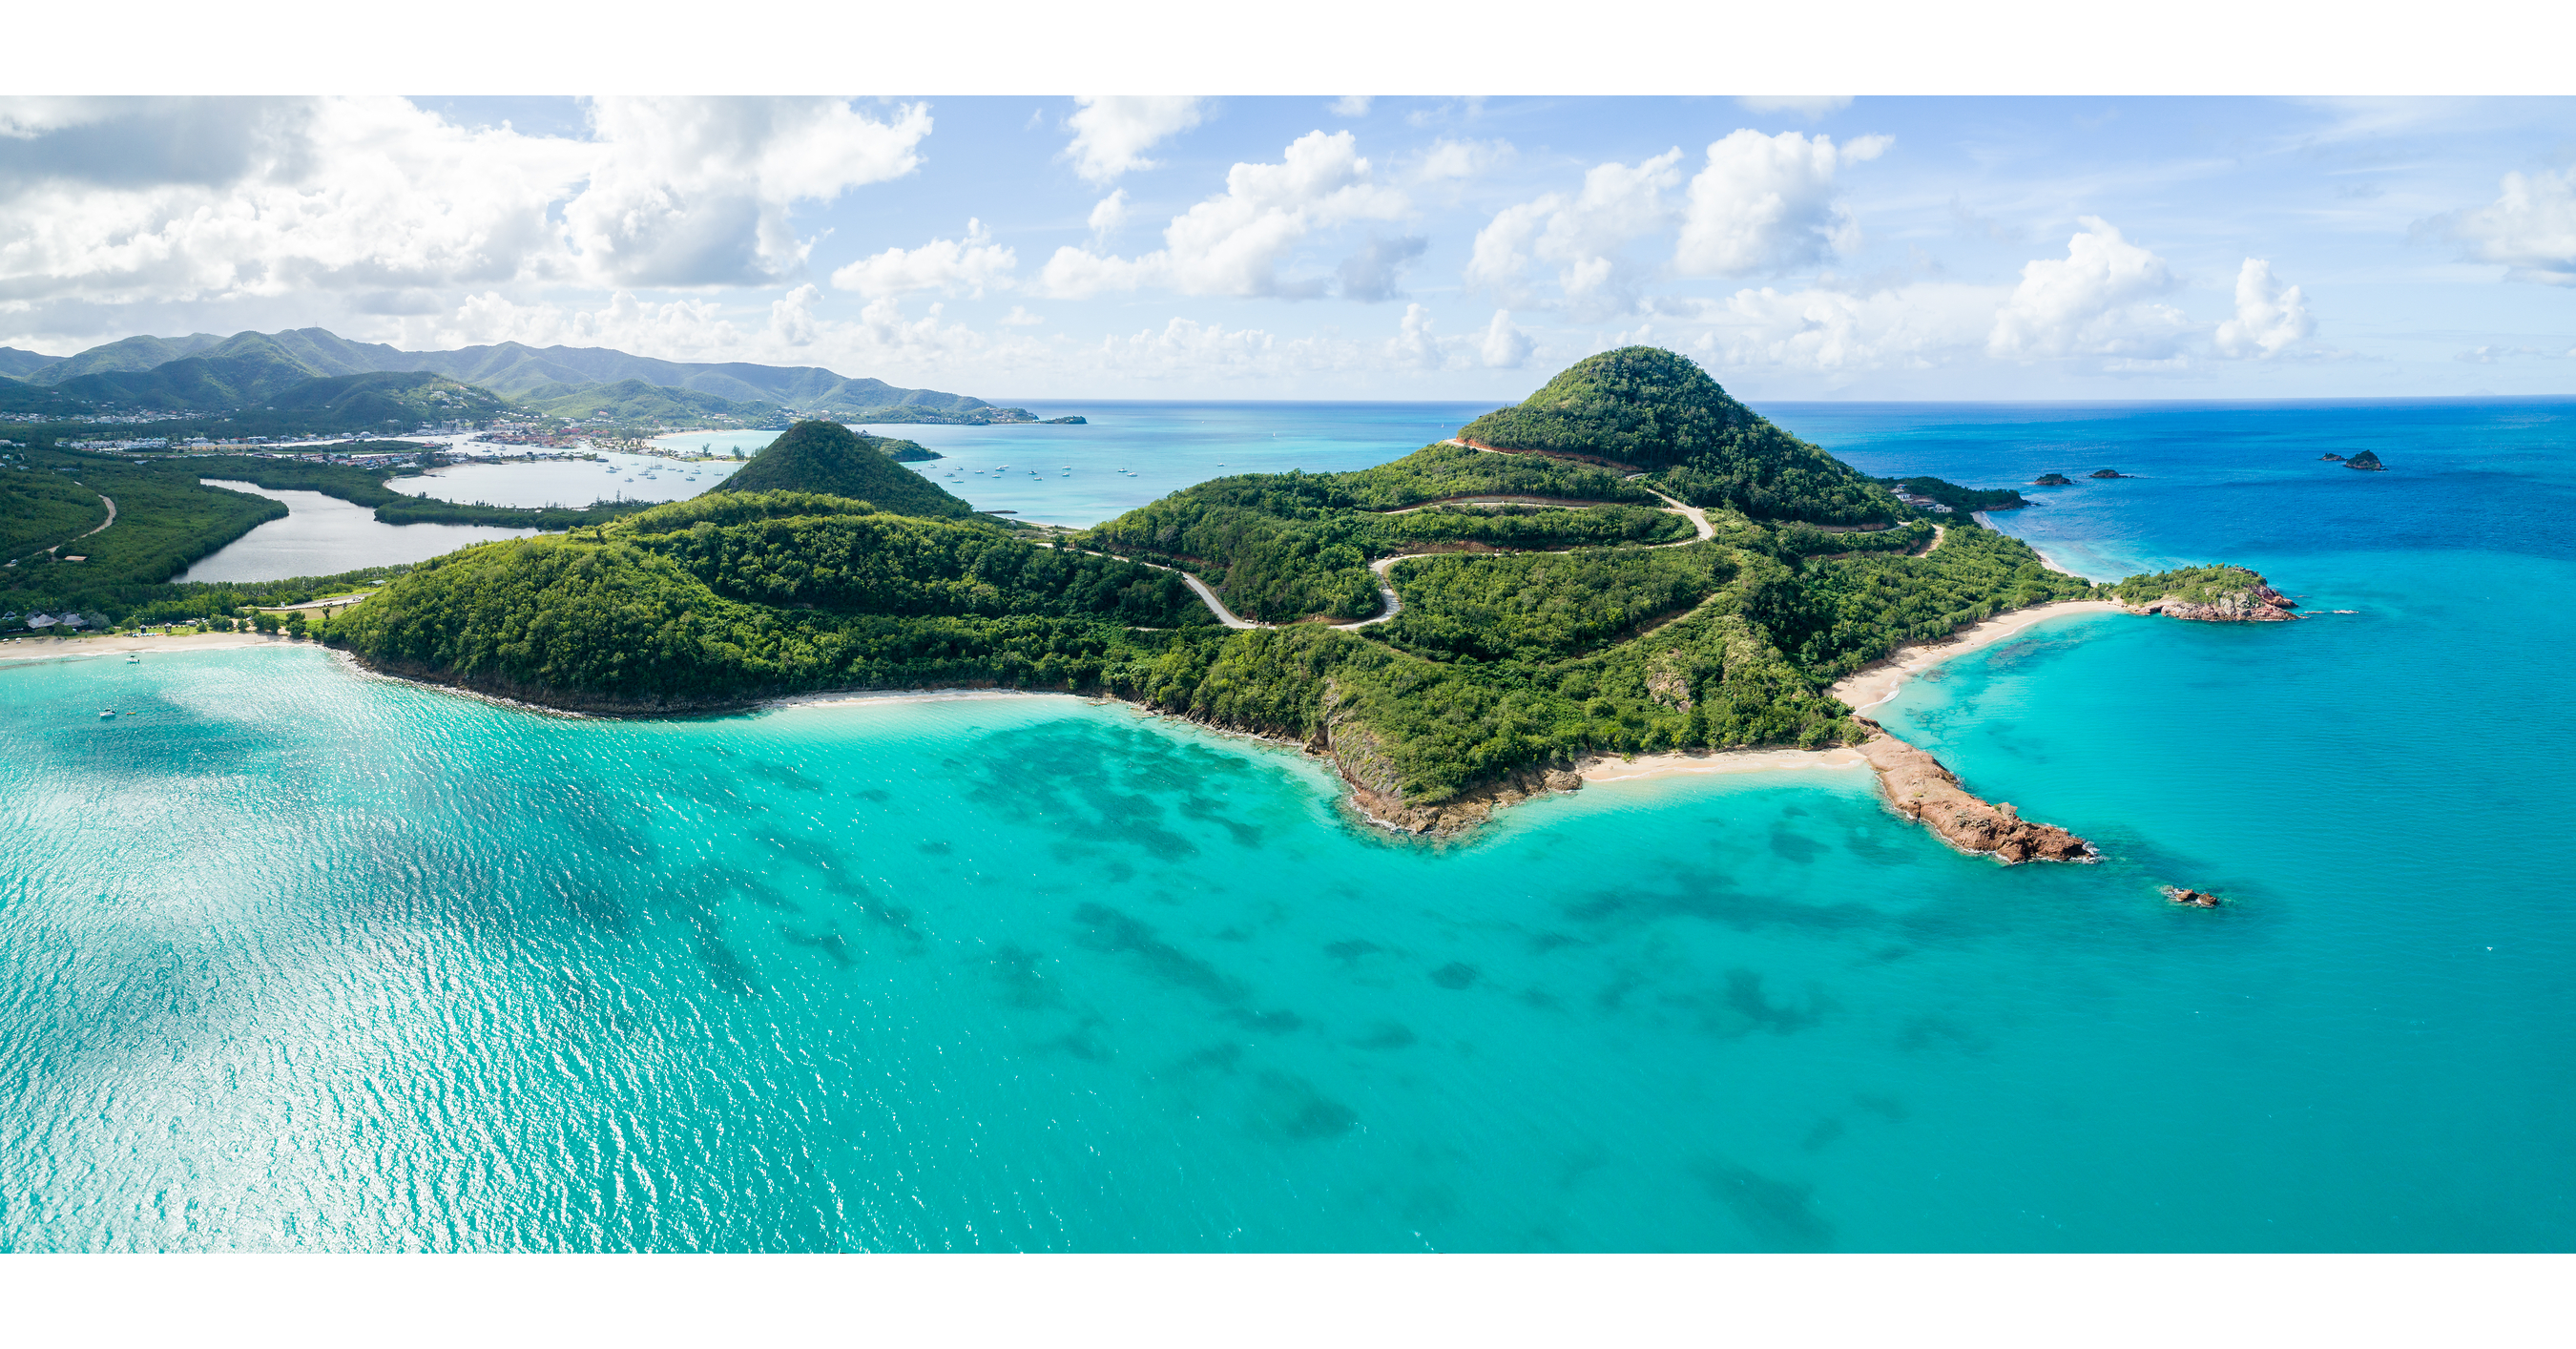
Pearns Point in Antigua will add a new luxury boutique resort via a joint venture between Daniel Shamoon and Dutch developer Albert Hartog, integrating 20 single-story suites and 20 two-bedroom villas plus 36 three- and four-bedroom villas onto a 160-acre peninsula. Villas for sale are priced at $3M–$6M, with early sales reported at 26 lots totaling $50M, signaling solid demand for the broader community (homesites from $2M; turnkey from $4M; finished homes from $20M). The announcement is primarily a real-estate/hospitality growth story with limited immediate public-market impact.
Analysis
This is more a signaling event than a fundamentally material one for public equities. The real market mechanism is luxury-demand validation: if a branded hospitality product can still anchor $3-6M villas in a small Caribbean market, it supports the idea that UHNW leisure/second-home spending remains resilient even as broader housing affordability weakens. The investable read-through is to luxury travel operators and booking intermediaries, but only at the margin; the asset is too small to move earnings.
The second-order benefit is to the ecosystem around the peninsula: local contractors, marine services, private aviation, high-end food/beverage, and any operator with exposure to boutique destination spend. The more important constraint is financing and absorption—this buyer pool is thin, so the project’s economics will depend on pre-sales cadence and funding terms, not press-release brand halo. If rates stay elevated or global risk assets wobble, this kind of trophy inventory can stall quickly.
Contrarian angle: the market may overestimate the value of the hotelier name and underestimate infrastructure, permitting, and exclusivity as the true drivers of residual land value. The public-beach-access language is also a clue that preservation optics matter, which can cap the pure luxury scarcity premium. Over 6-18 months, the decisive data will be whether phase-one inventory is absorbed without discounting; if not, the luxury Caribbean trade is probably being priced too optimistically.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No direct trade in CUPUF/IUSDF/PPMH; the project is too small and the listed-sympathy bid is likely illiquid. Treat this as a watch item, not a conviction position.
- For liquid proxy exposure, consider a small long in HLT or MAR on any 2-4% pullback over the next 1-3 months; the thesis is resilient premium-leisure demand, but keep sizing modest because the incremental read-through is sentiment-driven, not earnings-changing.
- Use BKNG and ABNB as monitoring vehicles into the next earnings cycle: if they show continued strength in high-end leisure ADRs/booking mix, the Caribbean luxury thesis is confirmed; if management commentary softens, fade the read-through.
- Set a 6-9 month alert on pre-sales and financing disclosures from Pearns Point. If absorption slips or development funding tightens, the right expression is to short luxury-asset/speculative-development proxies rather than the hotel narrative itself.
- If you want a cleaner pair, prefer long global luxury travel exposure (HLT/MAR) versus a broad consumer discretionary basket, because the upside is concentrated in affluent travel resilience while the downside is a normalization in aspirational spend.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard