
L'IAA va démarrer à Hanovre -- Présentation du plan de développement mondial systématique de FOTON
Source: PR Newswire
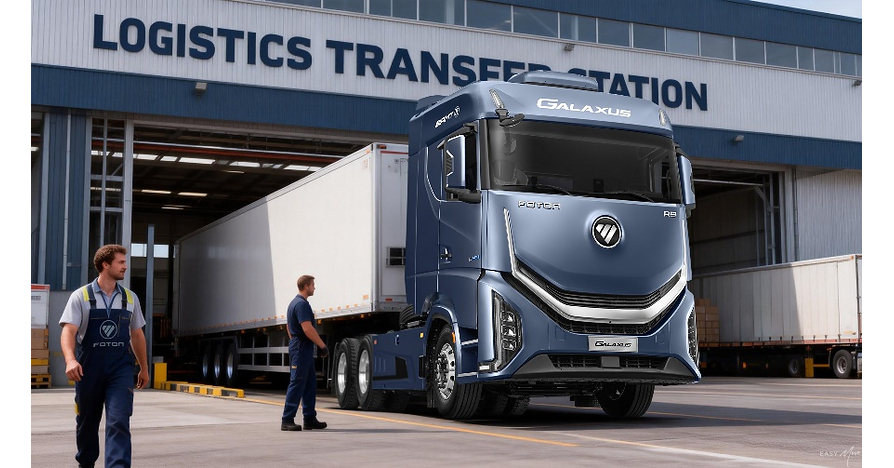
FOTON reported January-August 2026 export volumes of 149,000 vehicles, up 44.3% year over year, supported by its expanding overseas manufacturing, supply-chain and service network. The company will unveil its European strategy at IAA Transportation in Hanover on September 14 and make the international debut of the CAVAN BEACON heavy truck, compatible with both battery-electric and hydrogen fuel-cell powertrains. FOTON has secured European WVTA and VECTO certifications for several electric light-commercial vehicles and is deploying its CAVAN New Energy products across 15 European countries.
Analysis
The investable implication is less about FOTON's near-term valuation and more about whether Chinese commercial-vehicle OEMs can convert low-cost hardware into European fleet uptime credibility. A credible local parts-and-service footprint reduces the historical residual-value and downtime discount attached to Chinese trucks; if fleet tenders begin to reflect this, pricing pressure should migrate first to European light-commercial-vehicle and urban-delivery incumbents rather than premium long-haul platforms. Daimler Truck (DTG.DE), TRATON (8TRA.DE), Volvo (VOLV-B.ST) and Iveco (IVG.MI) have materially greater installed-base economics, but their electrification margins are most exposed where procurement is standardized and total-cost-of-ownership dominates brand preference.
The September trade-show event is unlikely by itself to alter earnings estimates. The relevant 1-3 month catalyst is independently disclosed European order intake, leasing partnerships, fleet trials, and evidence that warranty reserves remain contained; absent these, the announcement is principally marketing. Over 6-18 months, a successful Chinese entry would strengthen demand for China-based battery, power-electronics and charging suppliers while compressing European OEM content margins and potentially forcing higher dealer/service investment. The key reversal risk is EU trade enforcement: tariffs, local-content rules, procurement restrictions, or homologation scrutiny could preserve incumbent pricing power even if vehicle sticker prices are lower.
Consensus may overstate the threat to premium heavy-duty OEMs and understate the pressure on van and municipal-fleet economics. Fleet buyers will not switch solely on acquisition cost: financing, residual values, repair-cycle data, telematics integration and charging support determine adoption. That makes this a monitorable competitive inflection, not a standalone directional catalyst until contract wins demonstrate that the service proposition is accepted by European fleet operators.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Key Decisions for Investors
- No immediate directional trade on the launch; set a 30-90 day alert for disclosed European fleet orders, financing/lease partners and independently reported delivery volumes. Treat recurring fleet contracts rather than showroom expansion as confirmation of competitive displacement.
- Watch-list pair for confirmation: long Volvo B (VOLV-B.ST) / short Iveco Group (IVG.MI) over 6-12 months if Chinese entrants gain European urban-delivery share. Iveco's smaller scale and greater exposure to price-sensitive commercial segments make it the cleaner relative short; exit if EU protection measures materially raise landed costs or Iveco sustains order-book and pricing guidance.
- For a higher-beta expression only after verified European orders, consider short IVG.MI versus long CATL (3750.HK) for 6-18 months: the mechanism is OEM margin pressure versus rising battery-content demand. Do not initiate without data on battery sourcing and European production/local-content requirements, which could invalidate the supplier leg.
- Maintain a policy trigger around EU trade actions and national fleet-procurement rules. A formal restrictive action would likely favor DTG.DE and 8TRA.DE relative to Chinese export exposure; conversely, an absence of restrictions alongside measurable tender wins would warrant reducing European commercial-vehicle margin assumptions.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- EU entering winter with lowest gas reserves on record, IEA boss warns
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- U.S. oil holds above $100, Brent at five-month high as Iran says it’s prepared for warfare
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- AI Software for Buy-Side Teams: Build the Research Stack