
L'usine GAC Cambodia KD démarre sa production et établit une nouvelle référence en matière de fabrication locale
Source: PR Newswire
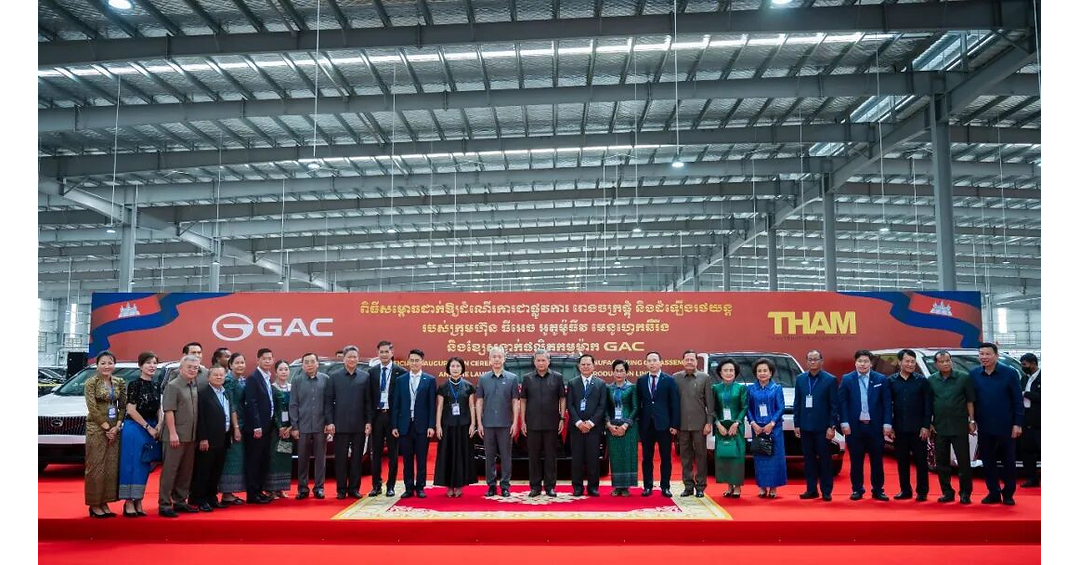
GAC and Cambodian partner TH Group inaugurated the GAC Cambodia KD assembly plant in Kampong Chhnang, shifting GAC from fully built vehicle imports to local CKD assembly. The plant is designed for annual capacity of about 10,000 vehicles, while GAC's TRUMPCHI brand has reported a CAGR above 300% in Cambodia over the past three years and ranked first among Chinese auto brands in the country in 2025. The investment expands GAC's Southeast Asian manufacturing footprint and supports Cambodia's industrial-upgrading strategy, though the direct market impact is likely limited to the companies and local auto sector.
Analysis
The relevant equity read-through is GAC Group (601238 CH/2238 HK), not the supplied TH ticker: the Cambodian operating partner appears privately held, so TH should not be traded on this news without entity verification. A local CKD footprint can improve landed-cost competitiveness versus CBU imports if it captures tariff/VAT treatment and shortens inventory cycles, but the addressable market is too small for this plant alone to alter consolidated earnings or valuation over the next 12 months.
The more important signal is strategic: China OEMs are using ASEAN assembly to build tariff-resilient distribution hubs while maintaining Chinese component content. BYD, Geely and Great Wall face a similar incentive to localize, making this less a durable GAC moat than a potential pricing escalation in entry-level ICE and EV segments; any initial GAC margin benefit is likely competed away as capacity follows demand.
Near-term, treat company-reported growth claims as a distribution-data point rather than evidence of profitable share gains. The key 1-3 month watch items are verified registration share, dealer inventory days, CKD duty treatment and financing penetration; weak utilization would turn fixed assembly costs into a margin drag. Over 6-18 months, the thesis improves only if Cambodia becomes an export-capable ASEAN node or if local sourcing meaningfully raises content eligibility under regional trade rules.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No position in TH until the ticker/entity linkage is independently verified; the named Cambodian assembler is not clearly a listed-company exposure.
- Keep GAC Group (601238 CH/2238 HK) on watch, not as a standalone catalyst trade. Consider a small long only after two consecutive quarters of Southeast Asia volume growth with stable dealer inventory and no deterioration in vehicle gross margin; falsify on rising incentives or utilization below economically viable levels.
- For a broader ASEAN-localization theme, prefer a relative-value basket long BYD (1211 HK) versus short a higher-cost regional incumbent only after confirmation of tariff advantages and registration data; this announcement alone does not justify entry.
- Monitor Cambodian automotive-duty policy and ASEAN rules-of-origin changes over the next 6-12 months. A removal of CKD advantages or broad competitor localization would eliminate the principal economic rationale for the plant.
More News
- Das GAC-KD-Werk in Kambodscha nimmt die Produktion auf und setzt damit neue Maßstäbe für die lokale Fertigung
- Chinese biopharma stocks jump as U.S. weighs keeping door open to drug deals
- Oil falls as crude flows remain 'surprisingly strong'
- Trump & Xi to Meet Amidst Friction on Wars, Tech, Trade
- Here are the 3 big things we're watching in the stock market this week
- Tech leads shares higher in Asia, oil eases
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital IQ Alternatives for Research and Deal Work
- Research Workflows, Report Format Selection, and Interactive Synthesis