
Macau Gaming Revenue Decline Extends Despite Golden Week Boost
Source: Bloomberg
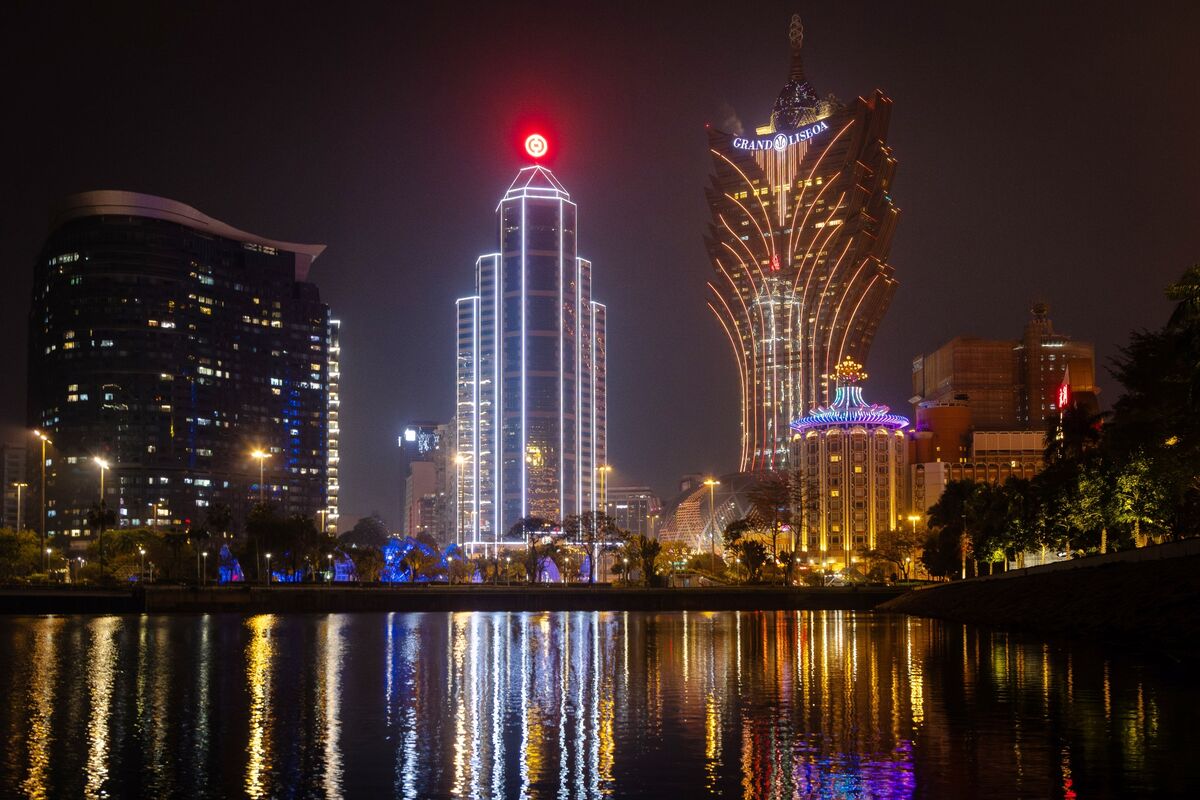
Macau gross gaming revenue fell 10% year over year to 21.68 billion patacas ($2.68 billion) in October, marking a fifth consecutive monthly decline despite a surge in Golden Week visitors. The drop matched the median analyst estimate and left revenue about 18% below its pre-pandemic level in 2019, as weak high-end player spending offset visitor growth.
Analysis
The key signal is the disconnect between visitor volume and spend: a holiday travel surge did not translate into stronger gaming receipts, pointing to weaker conversion or lower spend per visitor rather than a simple lack of foot traffic. That challenges the thesis that tourism normalization alone can restore Macau earnings; operators may need to spend more on promotions and non-gaming attractions to capture demand, potentially limiting operating leverage even if visitation holds up. High-end weakness also matters beyond casino floors: it can pressure premium hotel, retail, and service demand in Macau.
Because the decline matched expectations, the immediate read-through is more confirmation than a fresh negative surprise. Over the next 1–3 months, monthly revenue and operator commentary on mass-market versus premium play, spend per visitor, and promotional intensity should matter more than headline arrivals. Over 6–18 months, sustained weakness in premium demand would imply a slower earnings recovery and a risk that investors have overestimated the value of tourism growth. The countercase is that holiday timing and noisy monthly data obscure an eventual recovery; policy support or improving household confidence in China could lift spending. Do not infer company-level winners from the aggregate figure without segment disclosures.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.30
Key Decisions for Investors
- Avoid adding broad Macau casino exposure solely on visitor-growth narratives. Treat the October print as a reason to wait for evidence that visitation is converting into spend, not as a standalone short signal given the in-line result.
- For the next 1–3 months, monitor Macau monthly revenue alongside operator disclosures on premium play, mass-market spend per visitor, and promotions. A further deterioration in spend despite stable arrivals would strengthen an underweight thesis across Macau operators; improving spend and lower promotional intensity would weaken it.
- Keep any relative-value trade conditional: compare operator exposure to premium versus mass-market customers using reported segment data before favoring one of Galaxy Entertainment, Sands China, Wynn Macau, MGM China, SJM Holdings, or Melco Resorts. The aggregate release does not establish which operator is best positioned.
- Falsifiers: a sustained recovery in revenue and spend per visitor, supported by operator commentary rather than arrivals alone, would challenge the cautious view. Conversely, continued revenue weakness or rising promotional intensity despite resilient visitation would increase downside risk to earnings expectations.
More News
- Why Wendy’s is losing the burger wars—and is now a takeover target for Nelson Peltz
- Companies promised AI gains— here's how the payoff showed up in earnings
- FBI blames North Korea for record $6.3bn crypto heist
- Binance to resume crypto withdrawals in phases after record $6 billion hack
- Bangladesh forms wage board as garment workers protest
- AWS grows 39% and Amazon will spend even more on AI in 2027