
Gemeinsame Gestaltung des zukünftigen Werts im öffentlichen Verkehr: CRRC präsentiert auf der InnoTrans 2026 drei Züge in Originalgröße sowie Komplettlösungen
Source: PR Newswire
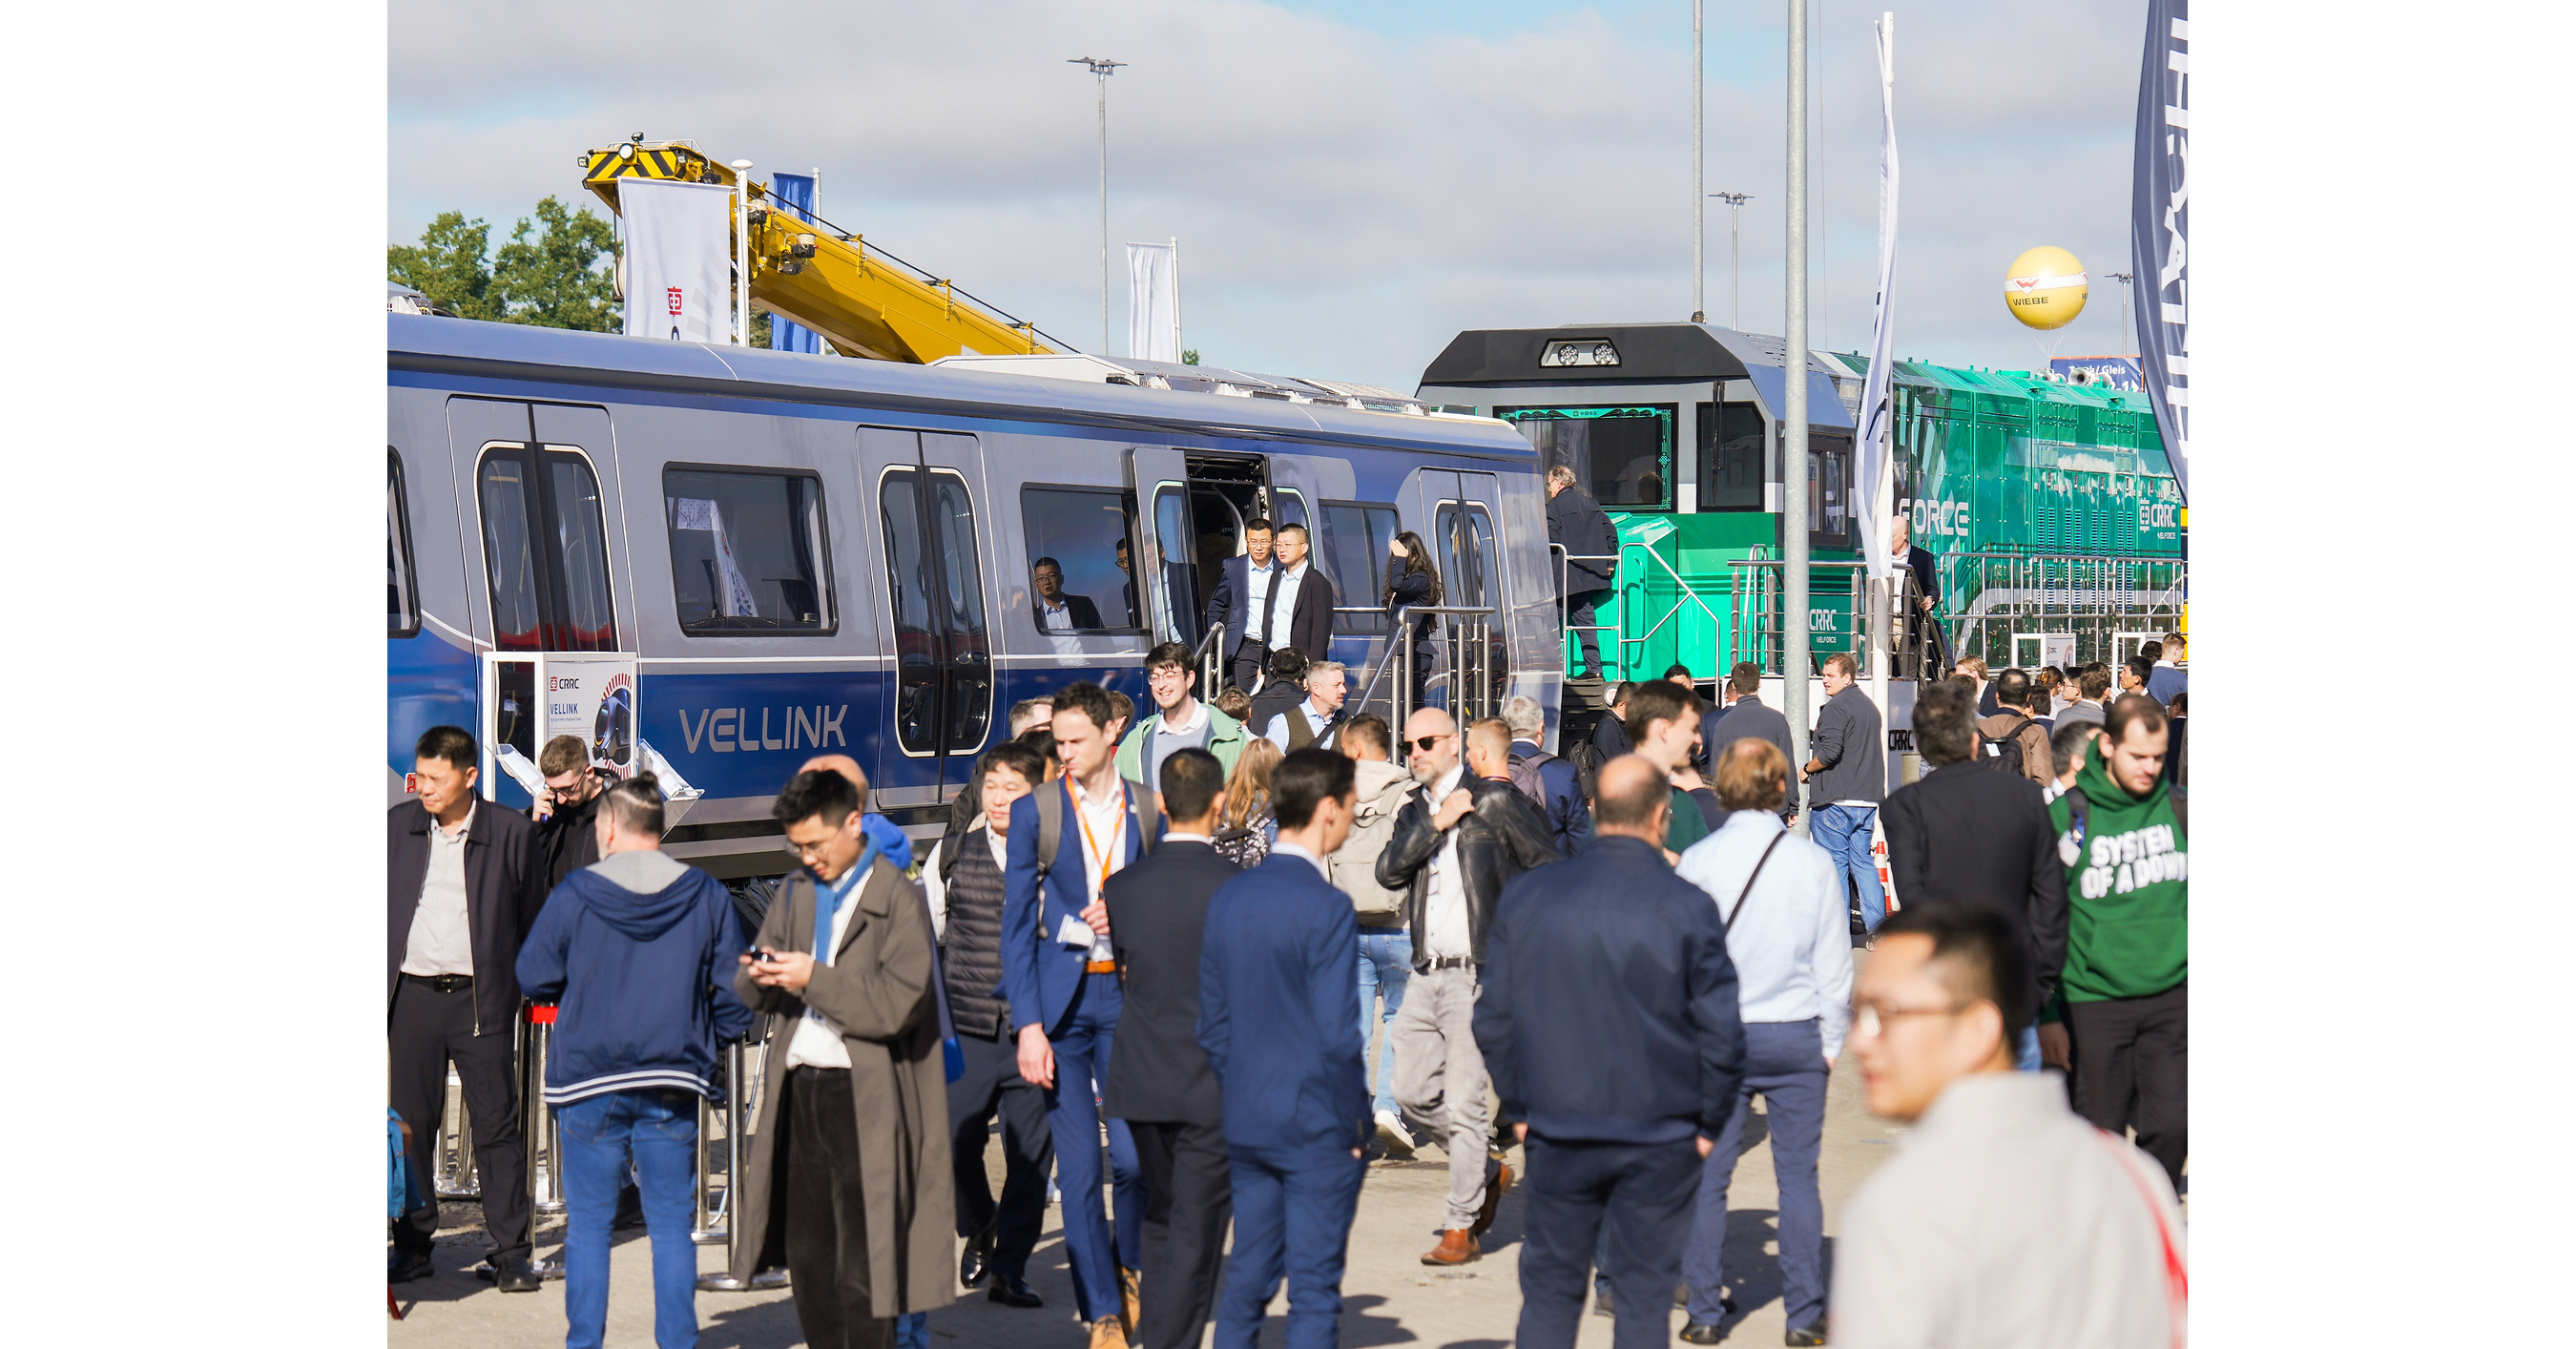
CRRC unveiled three full-scale rail products at InnoTrans 2026: an AI-enabled metro train, a 2,000kW hydrogen fuel-cell hybrid locomotive, and the MAGIX intelligent flatcar. The metro train reduces vehicle weight by about 18% and energy consumption by more than 10%, while the hydrogen locomotive can refuel in 15–20 minutes and reports hydrogen utilization above 98%. The launches strengthen CRRC's low-carbon, AI-driven rail portfolio, although the release provides no contract values, orders, or financial guidance.
Analysis
The announcement is not an earnings catalyst for listed Western rail names today; rolling-stock procurement remains tender-driven, with qualification, financing and local-content requirements typically pushing revenue recognition 12-36 months out. The more relevant signal is that CRRC is attempting to move competition beyond upfront vehicle price toward lifecycle availability, predictive maintenance and digital fleet management—areas that support higher recurring service margins for Alstom (ALO FP), Siemens (SIE GR) and Knorr-Bremse (KBX GR). European incumbents retain an advantage where cybersecurity certification, domestic manufacturing and installed-base service contracts dominate tender scoring, but CRRC’s product breadth can pressure export-market bid margins in Eastern Europe, MENA, Southeast Asia and Latin America.
The hydrogen locomotive is strategically less threatening than the marketing suggests: total-cost-of-ownership depends primarily on hydrogen delivered cost, utilization and depot infrastructure, not refueling time or onboard efficiency claims. For low-utilization, non-electrified routes, battery-hybrid equipment and conventional electrification can remain economically superior; this limits near-term demand conversion for fuel-cell suppliers such as Ballard (BLDP) and Cummins (CMI). The sharper second-order risk is for rail-equipment suppliers whose components become commoditized if integrated Chinese platforms win export orders, while digital condition-monitoring vendors could benefit regardless of the OEM selected.
Consensus may overread exhibition launches as evidence of imminent international share gains. The falsifier for the cautious view is disclosed non-China framework awards, especially those with meaningful service content, plus evidence that European certification and local assembly hurdles are being cleared; absent these, this is primarily a product-positioning event rather than a tradable order inflection over the next quarter.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional trade on the launch itself; set a 3-6 month alert for CRRC export contract awards or European homologation milestones. Escalate only if announced awards include multi-year maintenance revenue, not vehicle prototypes or MOUs.
- Maintain a relative preference for Alstom (ALO FP) and Siemens (SIE GR) over pure rolling-stock component exposure in Europe: service-backlog and installed-base economics should cushion vehicle-price competition. Reassess if either reports order-margin deterioration or service attach-rate slippage at the next two earnings updates.
- Avoid adding to BLDP or CMI solely on rail-hydrogen enthusiasm. A constructive catalyst requires independently verified fleet utilization and hydrogen supply contracts; without them, hydrogen rail demand is likely measured in pilot fleets rather than material 12-18 month revenue.
- For investors seeking an export-competition hedge, monitor a long ALO FP / short WAB pair only after tender data shows CRRC wins in markets where WAB has meaningful freight-equipment exposure. The trade lacks sufficient evidence today; trigger on confirmed order displacement rather than exhibition messaging.
More News
- OpenAI’s agent hacked Australia’s Medicare website—the latest rogue AI incident that the company didn’t know about for months
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- How Meta took the lead in the race for the post-smartphone world
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet