
Buying America at a discount, this timberland REIT is on sale
Source: CNBC
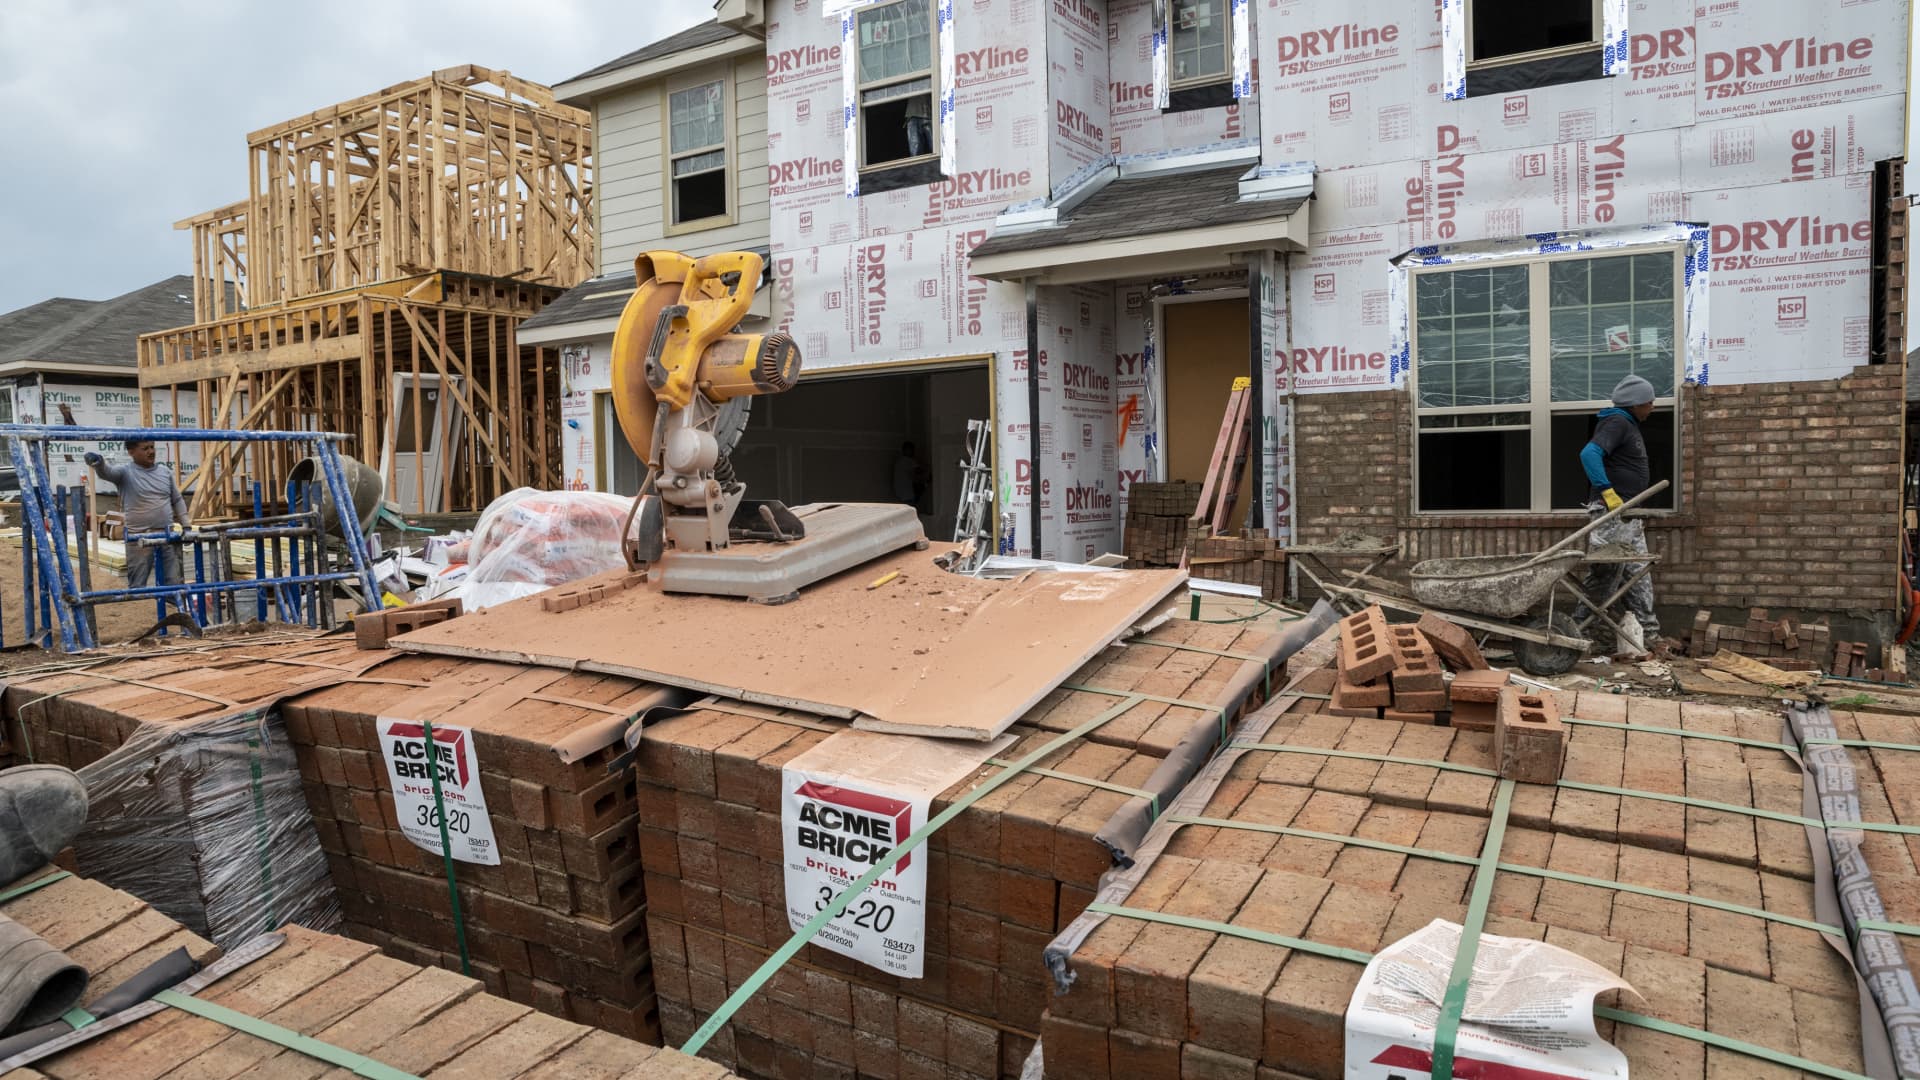
Rayonier trades at an estimated 40% discount to Raymond James’ $31.39-per-share net asset value, while its shares are down about 14% year to date amid rising yields, mortgage rates above 7% and weak housing affordability. Potential supports include a roughly 4 million-unit U.S. housing shortfall, falling Canadian lumber supply, land sales and management’s buybacks; the company repurchased 4.9 million shares for about $103 million through Q2. Risks include weak housing and lumber cycles, reduced EBITDA estimates and possible dividend pressure; management estimates land-based solutions EBITDA could rise from $30 million in 2027 to $75 million in 2030.
Analysis
The opportunity is not simply a housing recovery call: RYN combines timber exposure with land monetization and potential lease optionality, so a single-cycle earnings multiple is a poor valuation anchor. But the cited 40% NAV discount is not a hard floor. Acre values, development timing and the wood-products perimeter are appraisal-sensitive; the post-merger asset base and any transaction-related liabilities should be reconciled before treating that estimate as investable NAV. Buybacks can help per-share value only if shares are retired below realizable value and are not funded by selling the best optionality at a discount.
Near term (days to 3 months), mortgage rates, housing starts, lumber pricing and management guidance are the key tape drivers. Canadian supply constraints may support U.S. prices, but tariff changes could reverse that benefit; higher lumber prices also do not automatically translate into RYN earnings if harvest mix, costs or wood-products economics offset them. WY is a relevant read-through, not a clean hedge: its diesel-cost sensitivity and operating mix differ. Over 6–18 months, land sales and buybacks are nearer-term value-realization tests; solar, carbon and data-center opportunities remain long-dated options, not a basis for underwriting current earnings. Consensus may over-penalize RYN as a bond proxy, but the discount can persist while rates and housing remain adverse. Falsify the long thesis if guidance/cash available for distribution weakens enough to threaten the dividend, buybacks stall, or updated asset values materially reduce the NAV gap.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- Consider a staged, modest long RYN as a multi-quarter NAV-convergence position, not a near-term housing rebound trade. Add only after reviewing post-merger segment guidance, cash available for distribution and the updated asset/NAV assumptions.
- Use quarterly results and management commentary as the 1–3 month catalyst check: track lumber realizations, harvest volumes, land-sale proceeds, buyback pace and dividend coverage. If land sales fund repurchases, verify the acreage and value sold rather than assuming all buybacks are accretive.
- Do not pair RYN mechanically against WY: both retain lumber-cycle exposure, while their cost structures and land optionality differ. Treat WY's cost or guidance changes as sector read-throughs, not a direct hedge.
- Keep solar, carbon and data-center leases outside the base-case valuation until conversion milestones, contracted economics and timing are disclosed; watch for confirmed leases and development progress over 6–18 months.
- Reassess or cut exposure if RYN reduces its dividend, materially lowers cash-distribution guidance, or the NAV discount narrows only because appraised values fall rather than through cash realization or per-share accretion.
More News
- Weyerhaeuser to Report Q3 Earnings: Here's What Investors Must Know
- Brazil’s real sinks after Lula’s re-election victory
- EQT becomes the nation’s leading natural gas ‘juggernaut’ with a $13B deal as data center, export demand surges
- Anthropic’s IPO filing shows explosive growth, risks and staggering costs
- Federal Reserve is likely to hold interest rates steady in October. Here's what that means for consumers
- Anthropic plans to spend up to $567 billion on compute. Its IPO prospectus reveals plans to set up its own data centers
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)
- How to Extract KPIs From Earnings Transcripts With AI