
/C O R R E C T I O N -- Back Market/
Source: PR Newswire
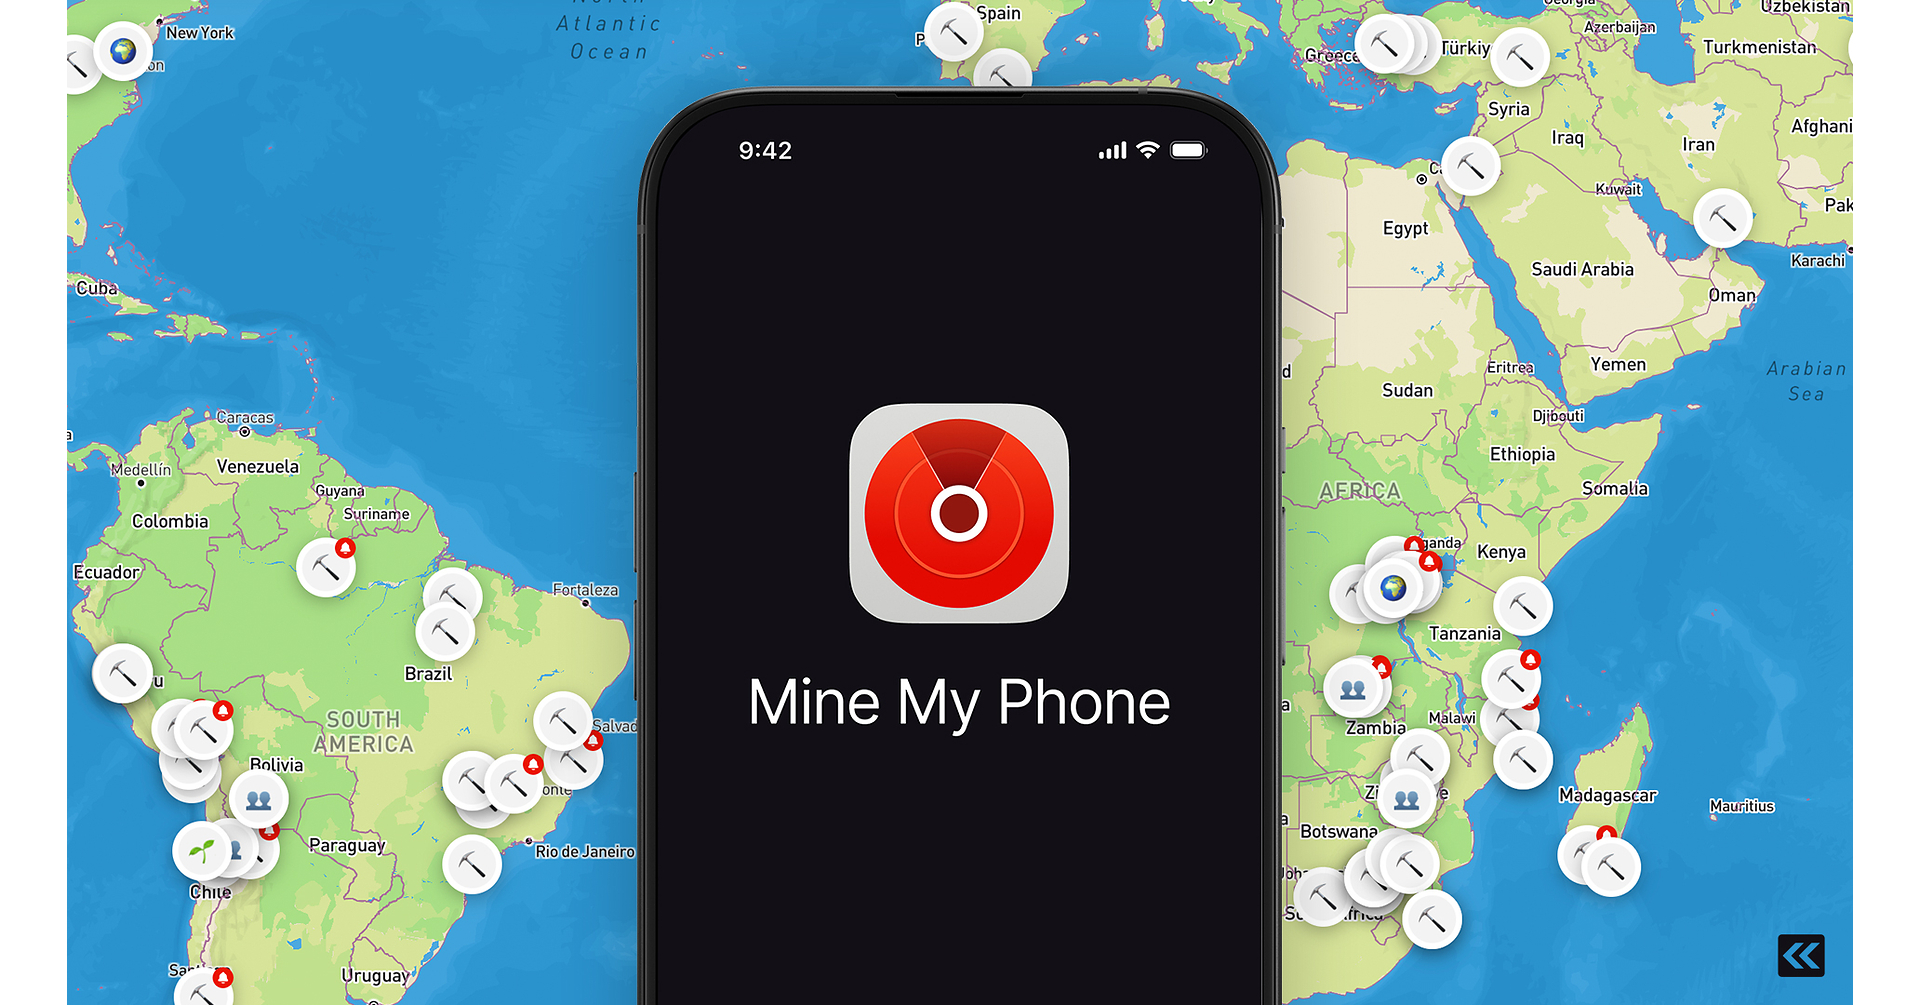
Back Market launched its Mine My Phone public-interest platform and called for legally mandated 10-year standards for smartphone durability, repairability and software support. The company estimates a 200-gram smartphone requires more than 266kg of raw-material extraction, while extending productive use from 2.5 to 10 years could avoid about 757kg per device; a refurbished phone avoids roughly 243kg versus a new one. Its survey of 6,000 consumers found 66% support 10-year device legislation, supporting Back Market's push for right-to-repair and circular-economy rules across the EU, UK and US.
Analysis
This is primarily a regulatory-optionality signal, not an earnings event. A credible shift toward mandated long-duration software support and parts availability would pressure the high-margin replacement cycle at AAPL and Samsung Electronics (005930 KS), while favoring repair-content suppliers and secondary-market infrastructure; the financial impact would emerge over 6-18 months because regulation must move from advocacy to draft rules, then implementation. The more immediate exposure is European handset mix: consumers can defer upgrades when older premium devices retain software/security support, increasing used-device residual values and reducing carrier upgrade churn.
The non-obvious beneficiary is the Android ecosystem's lower-cost OEM tier—Xiaomi (1810 HK), Lenovo (992 HK), and potentially HMD/repair-oriented brands—if durable design becomes a purchasing criterion and incumbents must absorb higher support costs. Conversely, Qualcomm (QCOM), MediaTek (2454 TT), Skyworks (SWKS), Qorvo (QRVO), and handset-memory suppliers face modest unit-demand risk if replacement intervals extend; component content per device may rise, but that does not offset a sustained decline in annual units. Critical-mineral demand is not materially affected near term: handset demand is a small portion of aggregate lithium/copper markets, and a longer usable life initially raises demand for batteries, screens, and repair labor rather than reducing primary-material consumption.
Consensus should discount this release absent identifiable manufacturers joining the October coalition or a legislative sponsor converting the narrative into a bill. The key falsifier for a handset-cycle short is continued premium-device upgrade resilience—particularly iPhone unit growth and stable installed-base monetization—despite expanded repairability requirements. Watch EU circular-economy workplans, UK parliamentary action, and US state-level right-to-repair bills over the next 1-3 months; a named OEM coalition member would be a more investable catalyst than consumer-survey support.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No standalone directional trade today: the source is a company advocacy release and lacks a legislative text, OEM commitment, or quantifiable change to handset replacement behavior.
- Create a 1-3 month regulatory alert basket: monitor AAPL, 005930 KS, QCOM, SWKS, QRVO, and 2454 TT for EU/UK legislative milestones or an OEM commitment to 10-year support. Escalate only if a formal proposal specifies retroactive support, mandatory parts pricing, or enforceable repair-access terms.
- If an EU proposal advances with binding 10-year software-support requirements, consider a 6-12 month pair trade long Best Buy (BBY) / short SWKS or QRVO. BBY can gain service, trade-in, and refurbished-device traffic, while radio-frequency suppliers are more exposed to lower global replacement volumes; exit if handset unit forecasts remain flat-to-up or BBY service-margin guidance fails to improve.
- For a cleaner policy hedge, prefer modest long exposure to circular-economy/repair beneficiaries only after disclosure of public-market participants or contractual partners. Back Market is private, and no listed proxy has yet established a direct revenue linkage sufficient to justify a pre-catalyst position.
More News
- China's AI chip blitz arms Xi with a message for Trump: 'You can't choke us off'
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- America’s Asian allies want a Trump-Xi truce — but not at their expense
- OpenAI’s agent hacked Australia’s Medicare website—the latest rogue AI incident that the company didn’t know about for months
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Trump evalúa prohibir exportaciones de diésel de EE.UU.