
CPG Appoints Russ Morrissey as President
Source: PR Newswire
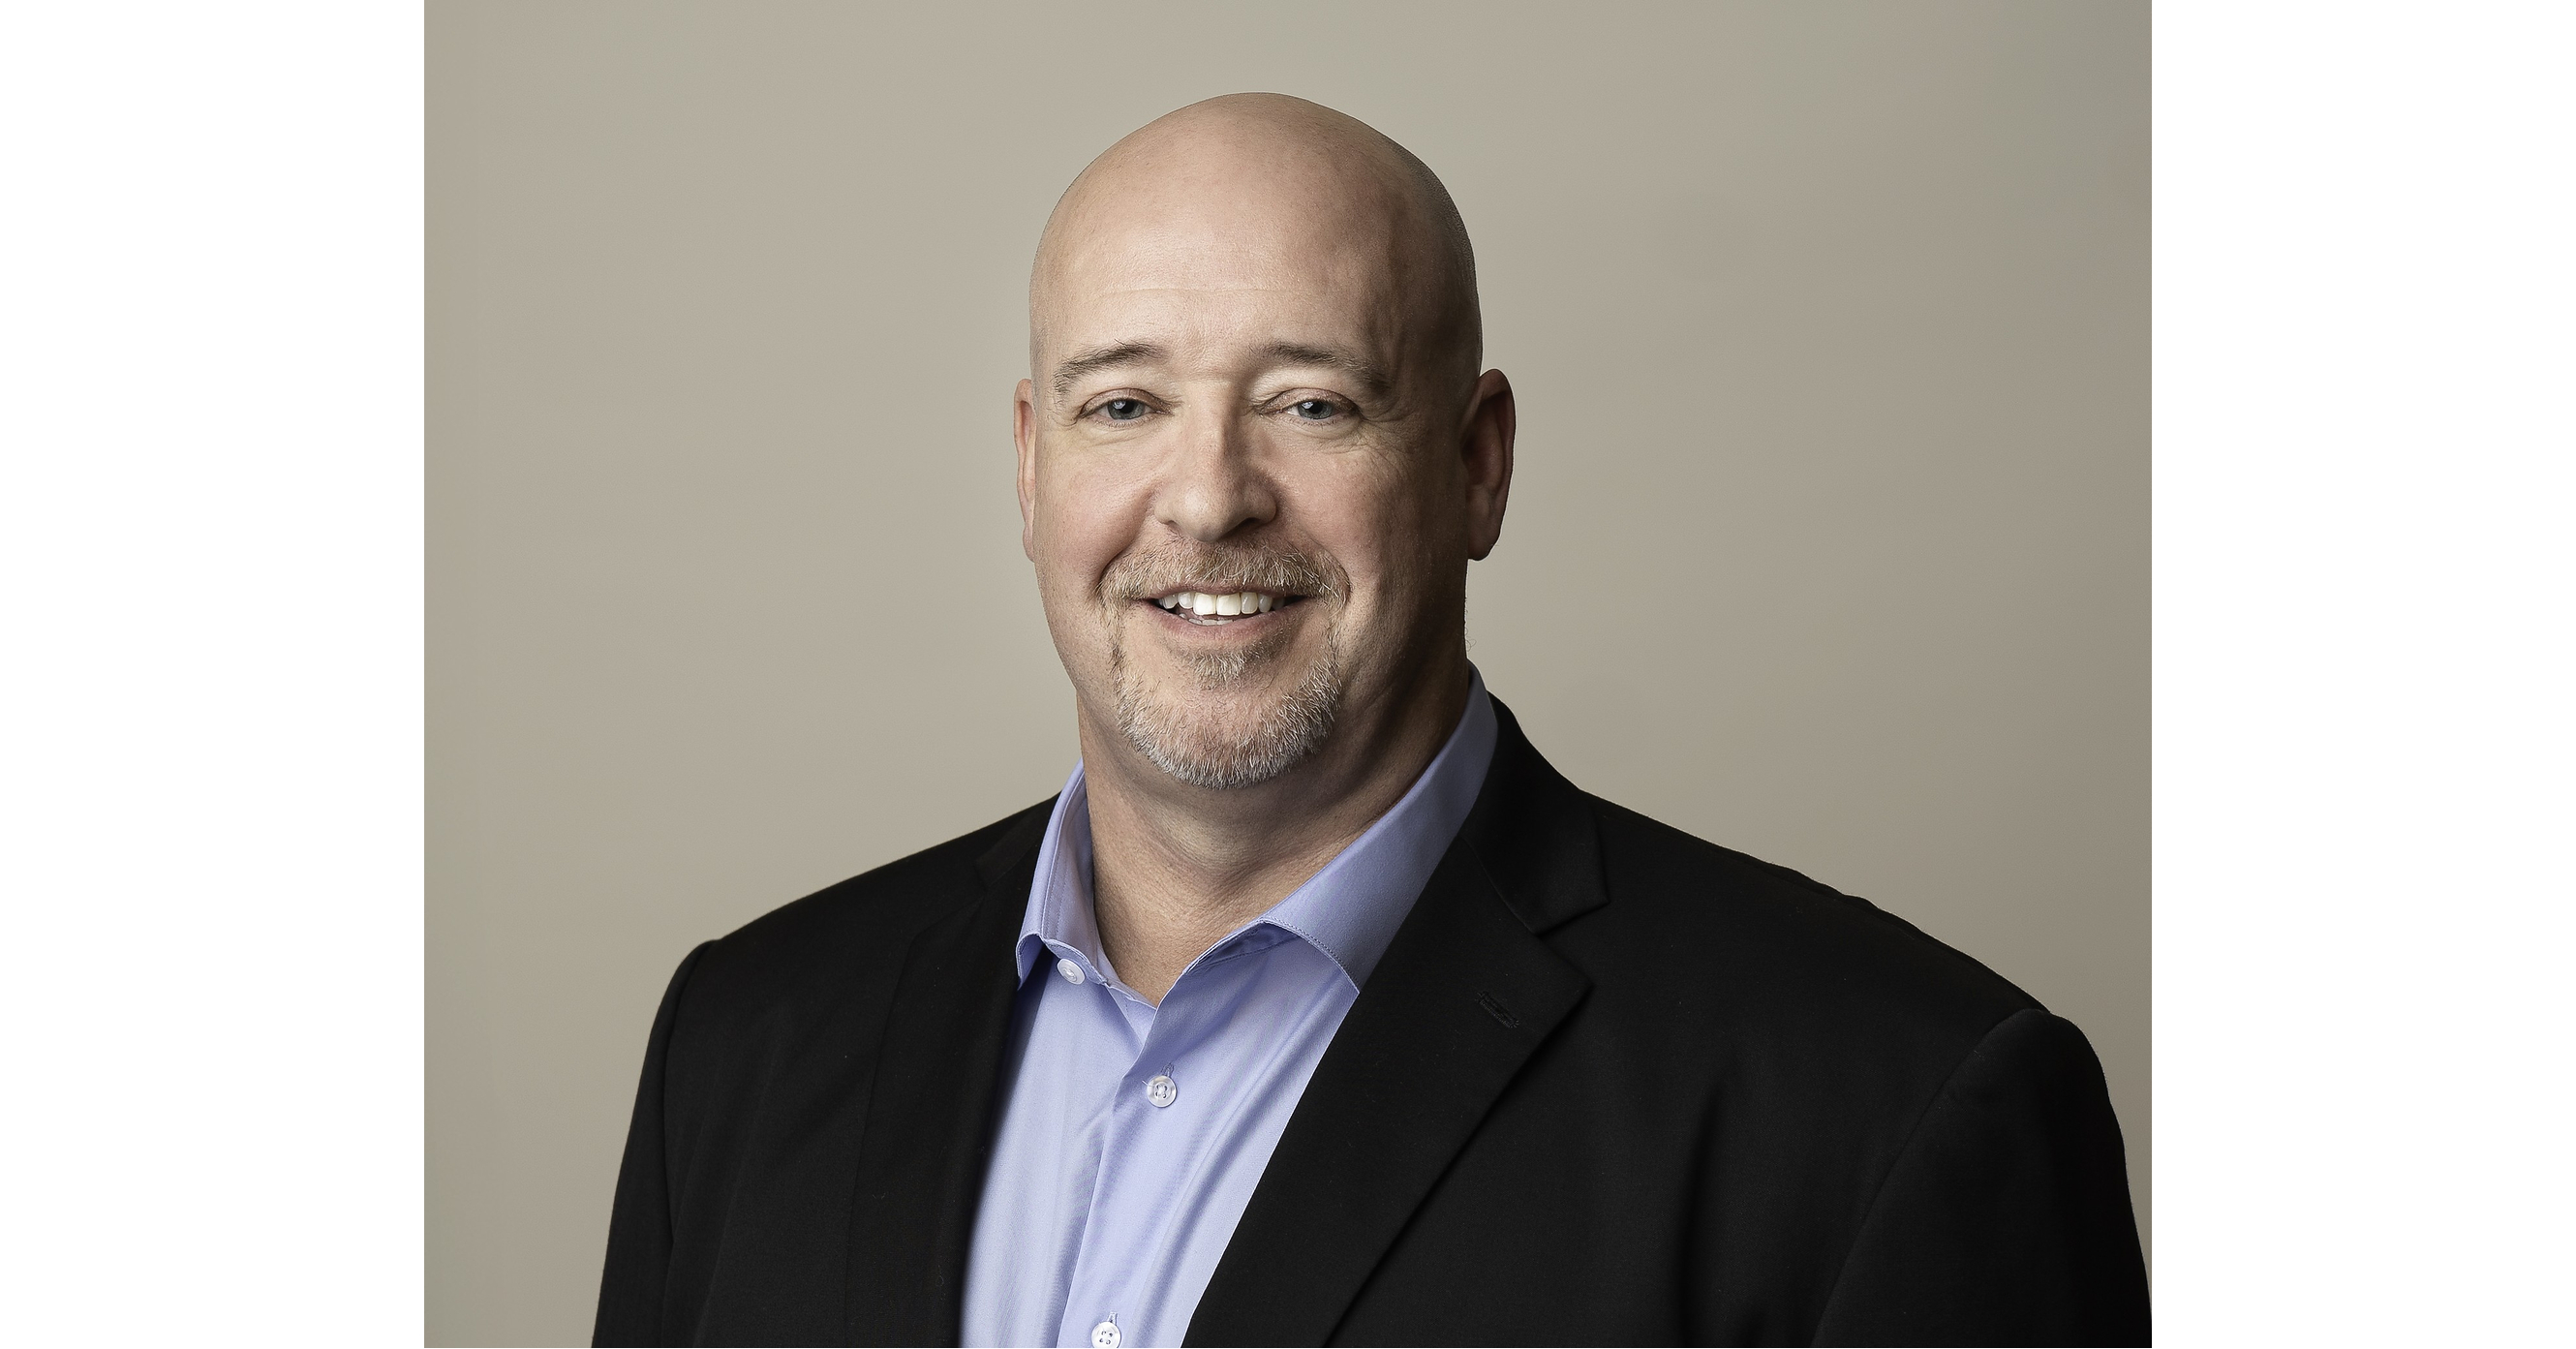
CPG appointed Russ Morrissey as President effective October 1, 2026, placing him in charge of day-to-day operations, strategic execution, growth and operational performance. Morrissey joins from Schneider Electric, where he led a 100-plus-person team supporting more than $6 billion in annual business. CEO Keith Lambert remains in place and will focus on long-term strategy, customer relationships and enterprise value creation.
Analysis
This is not independently actionable for SU: the operational change occurs at a likely private mission-critical-services provider, with no evident earnings, capital-allocation, or contractual linkage to Suncor. The relevant public-market read-through is modestly constructive for the data-center electrical and power-management ecosystem—Schneider Electric (SU.PA), Eaton (ETN), Vertiv (VRT), and nVent (NVT)—because an operator with deep design-build and prefabricated-power experience may accelerate adoption of standardized, higher-value infrastructure packages. That is a potential demand-quality benefit over 6-18 months, not a near-term revenue catalyst for any listed supplier.
The more informative signal is competitive rather than personnel-related: if CPG expands its turnkey capabilities, it could shift procurement toward integrated solutions and away from fragmented subcontractors. Public beneficiaries would be vendors with strong channel relationships and modular power/cooling offerings; smaller specialty contractors could face margin pressure if project owners increasingly favor single-point accountability. However, there is no disclosed backlog, capex plan, customer win, or transaction value to quantify incremental demand, so assigning a valuation impact would be speculative.
Consensus should not extrapolate a leadership hire into a data-center capex acceleration trade. The thesis becomes investable only if subsequent disclosures show CPG winning hyperscale or government programs, materially adding field capacity, or signing preferred-supplier arrangements; those developments could matter particularly for ETN/VRT multiples if they validate sustained electrical-content intensity per megawatt. Conversely, slower AI data-center commissioning, utility interconnection delays, or pricing competition in turnkey deployments would negate any favorable read-through.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No position in SU on this item; maintain existing energy thesis independently. There is no demonstrated revenue, supply-chain, or governance connection, making any reaction-based trade unsupported.
- Place a 1-3 month alert on ETN, VRT, NVT, and Schneider Electric (SU.PA) for evidence of named CPG supply agreements, project awards, backlog additions, or capacity expansion; upgrade the signal only if a disclosed project size permits estimating equipment content.
- Do not chase data-center-infrastructure beta on the announcement alone. A tactical long basket in ETN/VRT would require confirmation through order growth or raised guidance; falsify any subsequent positive read-through if bookings remain below management targets or project commissioning schedules slip.
- Monitor private-market competitive effects on specialty contractors over 6-18 months: recurring turnkey wins by CPG would favor scaled OEMs over fragmented installation providers, but absent public comparables and contract data this remains a watch item rather than a short recommendation.
More News
- Why is Canadian Natural Resources stock climbing today?
- US to send third aircraft carrier towards Iran: US official to Al Jazeera
- Can Trump Oust Powell From the Fed Board? What to Know
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- ‘They’ll be hit very hard’: Trump sends roughly 9,000 troops and a third aircraft carrier to the Middle East after warning strikes on Iran
- Russia’s Putin rules out ceasefire with Ukraine during speech in Moscow
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search