
U.S. economy is gathering steam. This is the chief reason why.
Source: marketwatch.com
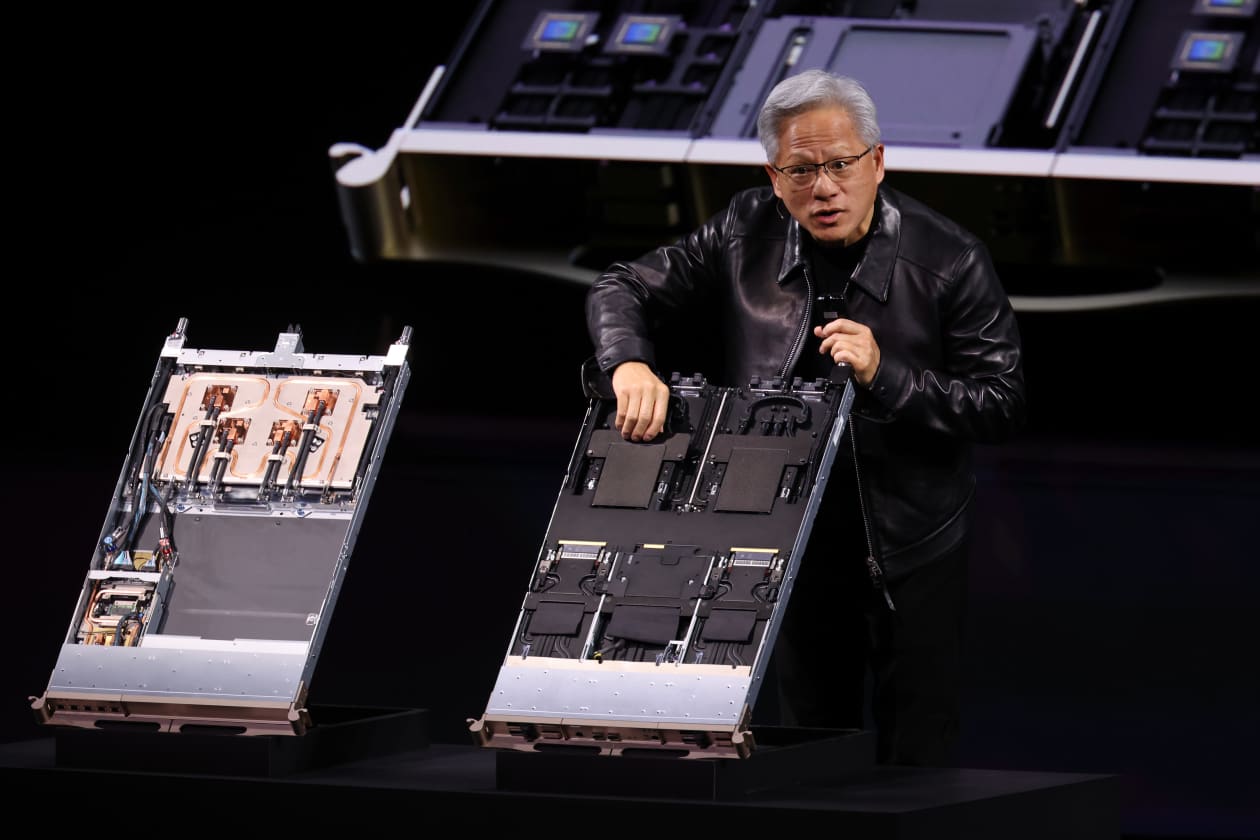
Anthropic and Meta are aiming to raise up to $200 billion to expand AI capabilities, adding to hundreds of billions of dollars U.S. companies have already spent on AI. The investment is driving demand for chips, computers, electrical equipment, power turbines, and data-center construction materials, which the article identifies as a key reason the U.S. economy is gathering steam.
Analysis
The investable implication is not simply “AI is good for tech”: spending on facilities and power infrastructure can accrue to a different supplier set, and on a different timeline, than returns from AI applications. Grid equipment, cooling, electrical systems and data-center construction may see order visibility before AI monetization is clear; watch whether supplier backlogs convert to revenue and whether delivery lead times or power access constrain projects. For Meta, the second-order trade-off is strategic capacity versus rising capital intensity: more infrastructure can strengthen its competitive position, but depreciation and operating costs could pressure free cash flow if monetization lags. The near-term macro boost from investment is not proof of attractive project returns. Over 1–3 months, validate the thesis with hyperscaler capex guidance, durable-goods and construction data, and supplier backlog commentary. Over 6–18 months, the key risk is a buildout ahead of utilization, compounded by financing costs, grid bottlenecks or power-price increases. The contrarian point: AI investment can support GDP while still producing weak returns for the companies funding it. The article provides no valuation, order or utilization data to establish that supplier equities—or META—are mispriced.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Prefer a staged, relative-value exposure to data-center electrical and grid-enablement suppliers such as Eaton, Vertiv and Quanta Services over a broad, undifferentiated AI trade; add only if reported backlog conversion and guidance confirm demand, rather than relying on announced spending plans.
- Keep META as a watch/hold rather than adding on this macro narrative alone. Reassess on its next capex and monetization disclosures: rising infrastructure spend without corresponding revenue or cash-flow evidence would weaken the equity case.
- Use the next 1–3 months of hyperscaler guidance, supplier order commentary and power-availability updates as catalysts. A capex slowdown, backlog cancellations, or evidence that data-center utilization is lagging would falsify the supplier-overweight thesis.
- Avoid extrapolating investment-led GDP strength into broad cyclical exposure: if rates rise or power and construction constraints delay projects, spending can remain announced while supplier revenue realization and investor returns disappoint.
More News
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Indian investors rush to Nvidia, SpaceX, Apple as local trading apps roll out access to U.S. stocks
- AI debt fears ease ahead of Oracle, Alphabet and Amazon updates. Here's what to watch.
- Meta Boosts Equity Offering to $98 Billion, Raising Its AI Bet
- What's behind the AI trade comeback — plus, our take on Intel's latest deal
- Nvidia to invest $3 billion in Meta as tech giants deepen AI partnership