
Saipem Lands $350M Contract for West Hub Tails Project in Angola
Source: zacks.com
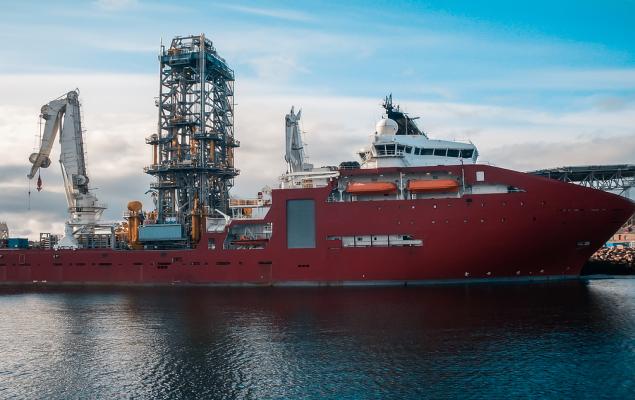
Saipem secured an approximately $350 million subsea engineering, fabrication and installation contract for Azule Energy's West Hub Tails project offshore Angola, with execution expected to last nearly 2.5 years. The scope includes 62 km of flowlines, risers and umbilicals tied to the Agogo FPSO, redirecting four mature fields from the aging Ngoma FPSO. The project extends field life and recovery while using Agogo's newer, lower-emissions operating infrastructure, providing a meaningful incremental backlog win for Saipem.
Analysis
This is immaterial to BP’s consolidated earnings but incrementally valuable as a capital-efficiency signal: redeploying existing offshore resources through shared processing infrastructure should carry lower unit development costs and lower execution risk than a greenfield hub. The more relevant read-through is for Eni and BP’s ability to sustain Angolan cash flows without committing to a new FPSO; any evidence of repeat brownfield tie-backs could support upstream decline-rate expectations over the next 6-18 months.
For Saipem (SPM), the economic value depends on backlog quality rather than headline contract value. Integrated engineering, fabrication and installation work raises vessel utilization and absorbs fixed yard costs, but offshore EPC margin can be impaired by weather, vessel downtime, local-content execution and change-order disputes. The 2.5-year duration means little near-term EPS effect; the 1-3 month catalyst is management disclosure of contract margin, working-capital terms and whether the award improves bidding discipline or merely fills capacity.
The non-obvious beneficiary is the broader subsea-services complex: brownfield life-extension projects are typically less oil-price sensitive than frontier exploration because they monetize sunk infrastructure and can proceed at lower breakevens. This favors diversified offshore contractors and equipment suppliers over refiners such as VLO and PARR, whose economics remain driven by crack spreads and regional product balances rather than upstream African capex. Consensus may overread the award as a standalone equity catalyst; without confirmation that it lifts annual backlog conversion or EBITDA guidance, the appropriate response is monitoring rather than chasing SPM.
Thesis falsifiers are a material reduction in BP/Eni upstream capital allocations, Brent weakness sufficient to trigger project deferral, or Saipem reporting low-margin backlog conversion and elevated working-capital absorption. Conversely, follow-on African awards, improving vessel utilization, and disclosed margin above Saipem’s existing offshore-engineering run rate would justify rerating the contract’s contribution.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in SPM on this announcement; place a 1-3 month alert around results for backlog, offshore EBITDA-margin and net-working-capital guidance. Consider a tactical long only if management quantifies margin/accretive backlog and the stock has not already rerated; exit on evidence of negative working-capital or execution-cost pressure.
- Maintain BP exposure only as part of a broader integrated-oil allocation, not as an Angola catalyst trade. Reassess over 6-18 months if BP demonstrates that brownfield tie-backs stabilize upstream production while holding capital intensity flat; reduced upstream guidance would invalidate the premise.
- Avoid using VLO or PARR as read-through vehicles. Their 1-3 month risk/reward is governed by crack spreads, crude differentials and refined-product demand; use them only where independent refining indicators are supportive.
- Screen offshore peers and suppliers for unpriced African brownfield backlog exposure; a long diversified offshore-services basket versus a short broad energy-equity proxy becomes actionable only if multiple follow-on awards confirm a regional capex cycle and Brent remains supportive.
More News
- Delek US Holdings EVP, refining Russell sells $407,096 in stock
- Northwest European gasoline margins drop over $7 on crude surge
- Bernstein Flags Five Stocks to Benefit as Europe Faces Tighter Gas Market
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Asian markets make nervous start ahead of Fed decision
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital IQ Alternatives for Research and Deal Work
- Research Workflows, Report Format Selection, and Interactive Synthesis