
Sportball Accelerates U.S. Expansion with New Locations in Dallas-Plano and Frisco-McKinney, Texas
Source: PR Newswire
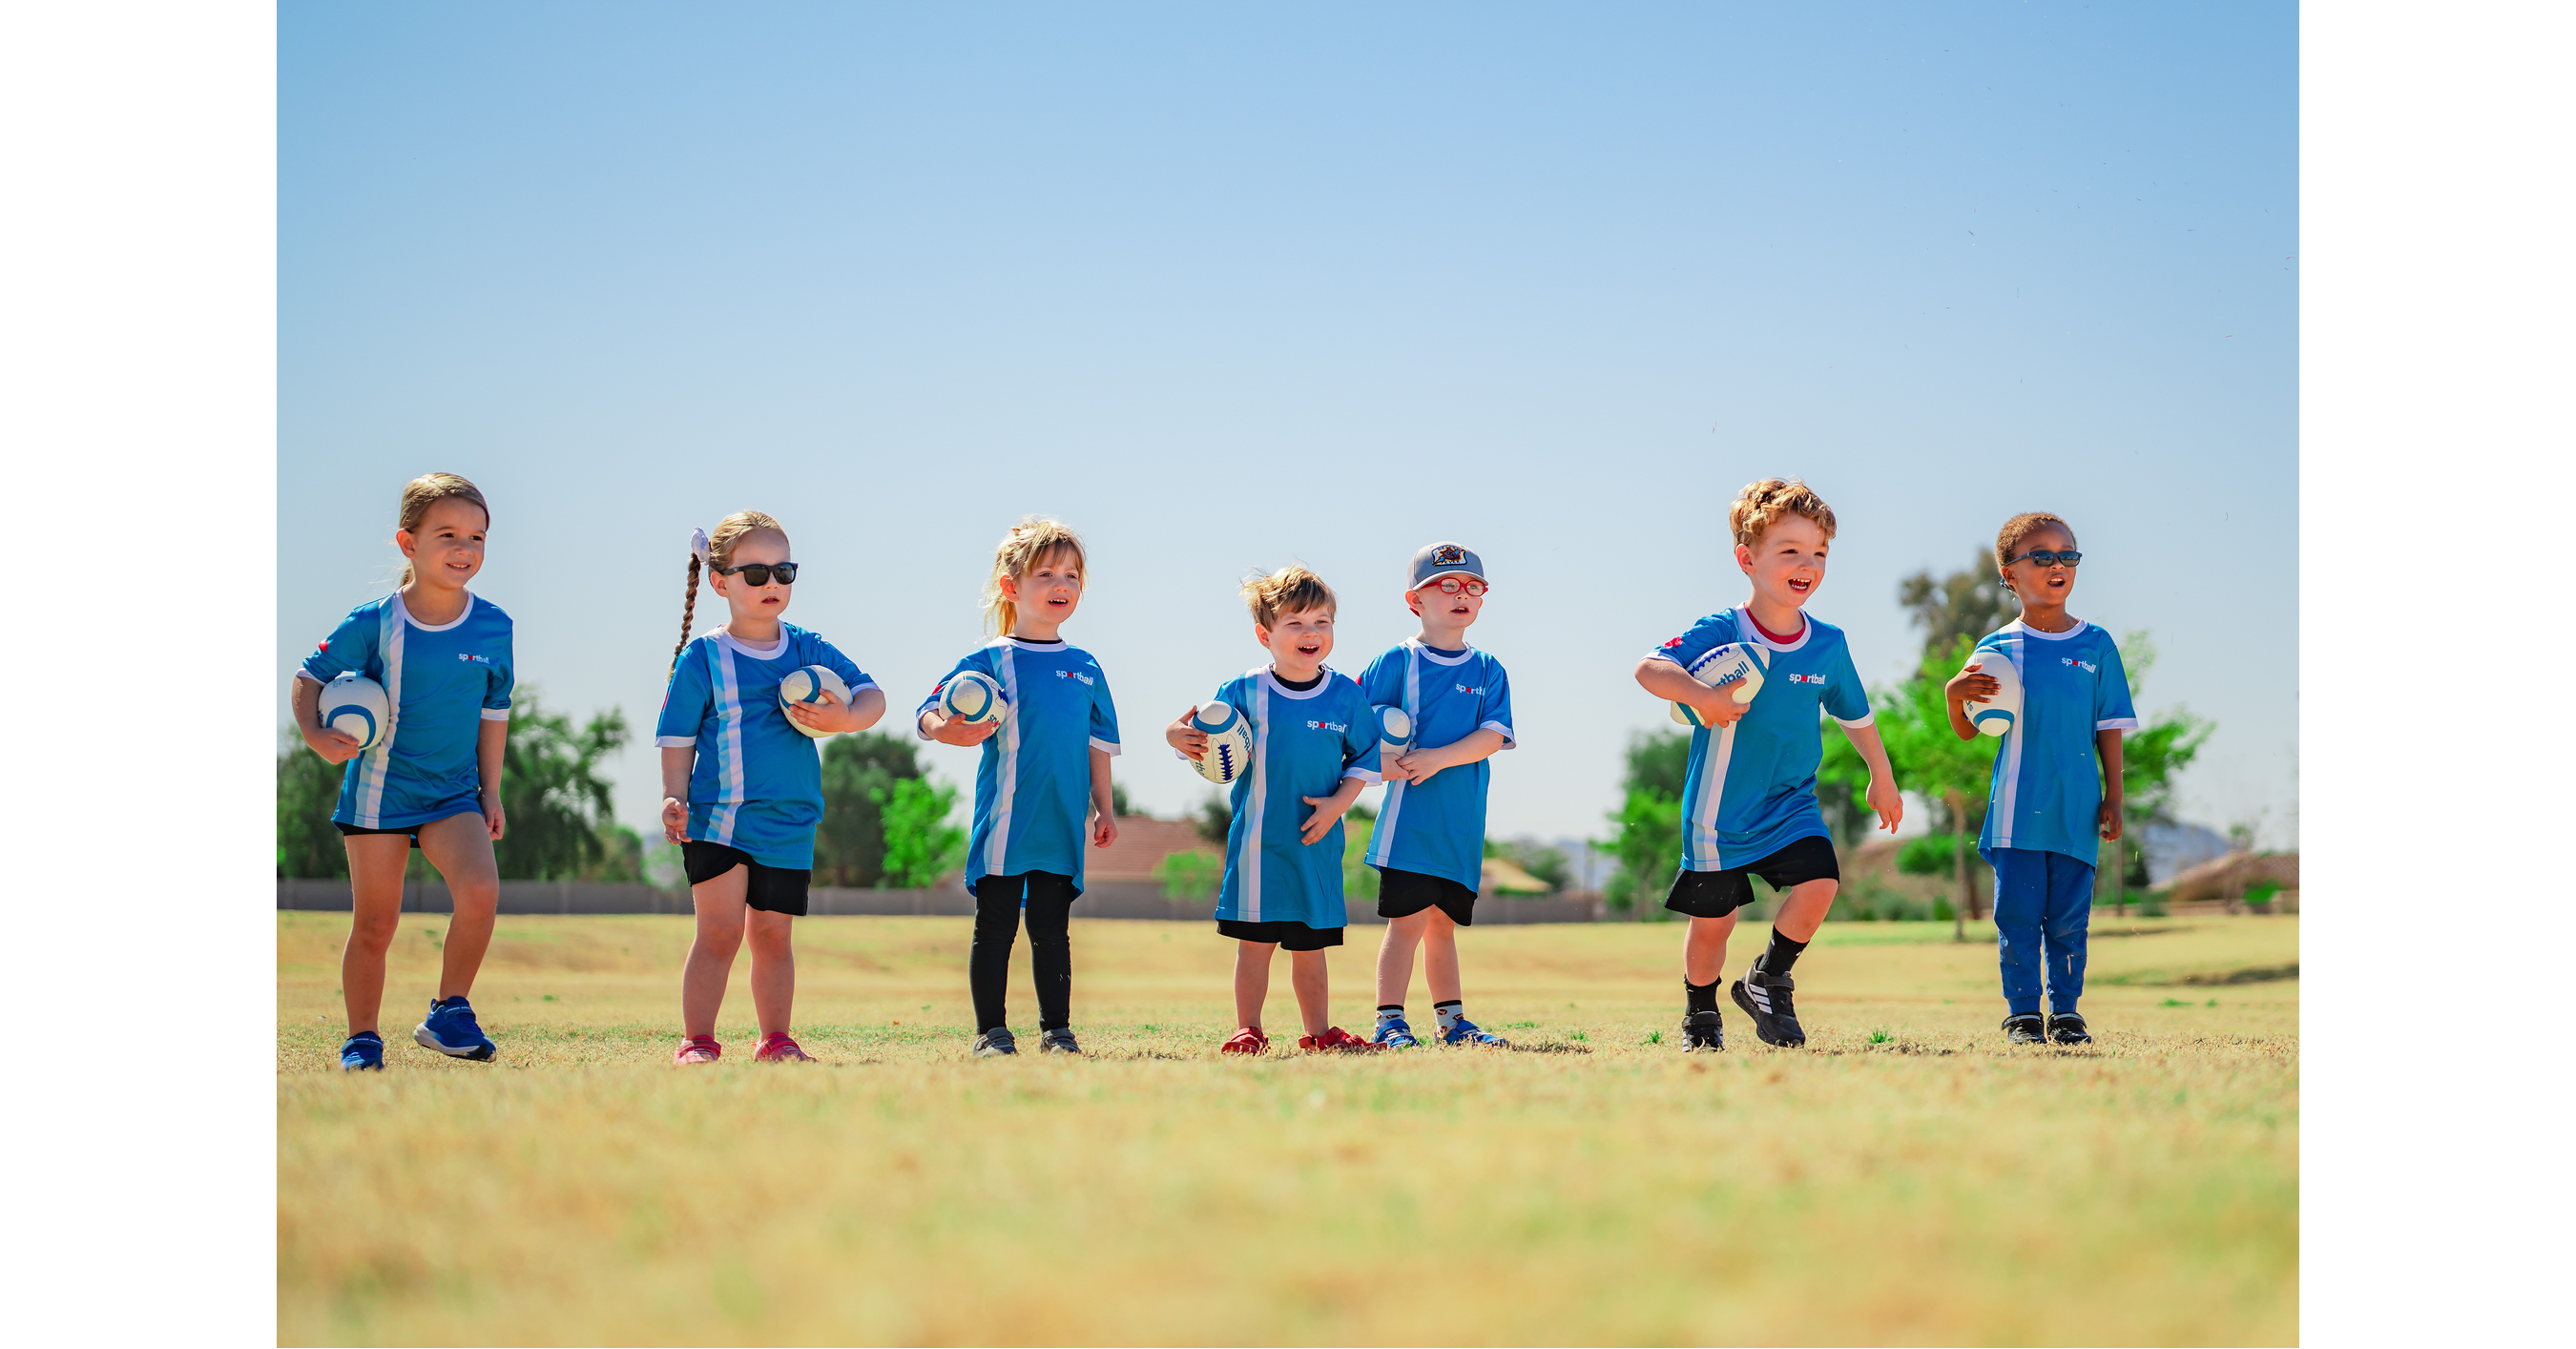
Sportball will open its first U.S. corporate-operated location in Dallas-Plano in fall 2026, launching classes on October 10, and plans a Frisco-McKinney franchise opening in early 2027. The expansion strengthens Texas as a growth market, adding to four existing state locations and supporting a broader U.S. strategy combining corporate investment with franchising. Sportball operates more than 900 locations across four countries and serves over 70,000 children annually.
Analysis
This is not investable public-equity news by itself, but it is a modest datapoint on parents' willingness to spend on structured, low-ticket youth enrichment despite broader discretionary-pressure concerns. The corporate unit is strategically more important than its near-term revenue: it can establish a U.S. unit-economics template, localize programming and pricing, and improve franchise sales conversion if its economics are demonstrably superior. Until enrollment, retention, instructor utilization and four-wall contribution are disclosed, the expansion claim remains unverified.
The more relevant public-market read-through is for asset-light youth activity and franchise ecosystems rather than broad leisure. In a resilient suburban household-spend environment, franchisors with recurring royalty streams and local operator funding—particularly Xponential Fitness (XPOF), despite its different customer base—could benefit from evidence that experiential services retain wallet share. Conversely, the competitive set is fragmented and venue access is a binding constraint: schools, recreation centers and childcare facilities can capture a meaningful portion of economics or limit expansion velocity, making rapid network scaling less likely than headline location counts imply.
Over the next 1-3 months, this has no likely catalyst for listed securities. Over 6-18 months, a sustained shift from single-sport specialization toward multi-activity programs could pressure narrow-format youth operators and favor providers with flexible curricula, but there is no clean listed proxy. The contrarian view is that Texas participation gaps may reflect time, transport and affordability constraints rather than unmet demand; adding capacity would then dilute local franchisee economics rather than unlock incremental demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No standalone position: treat this as a private-market/franchise-industry datapoint, not a catalyst for public consumer-leisure equities.
- Add XPOF to a watchlist rather than buy on this signal; require improving same-store sales, franchise studio openings and stable closure rates in the next two earnings reports before using youth-enrichment resilience as a broader experiential-demand thesis.
- For consumer-discretionary exposure, monitor Dallas-Fort Worth youth-program enrollment and local childcare/rec-center pricing over the next two quarters. A weak enrollment ramp or elevated promotional activity would support the view that household time constraints, not latent demand, limit category growth.
- If private-market diligence becomes available, require Dallas-Plano cohort retention, instructor labor as a percent of sales, facility revenue-share terms and franchisee payback period before assigning value to the corporate-unit expansion model.
More News
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Trump Says US Team Met With Iranians at UNGA
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Heidi CEO on AI in Healthcare, $900M valuation
- Australia’s IDP shares drop after rejecting $494 mln Blackstone offer
- Meta’s Muse AI is exploding in popularity—and already drawing heated backlash from another tech giant