
Snap Shares More Details About $2,195 Specs AR Glasses, Plus Verizon Partnership
Source: Bloomberg
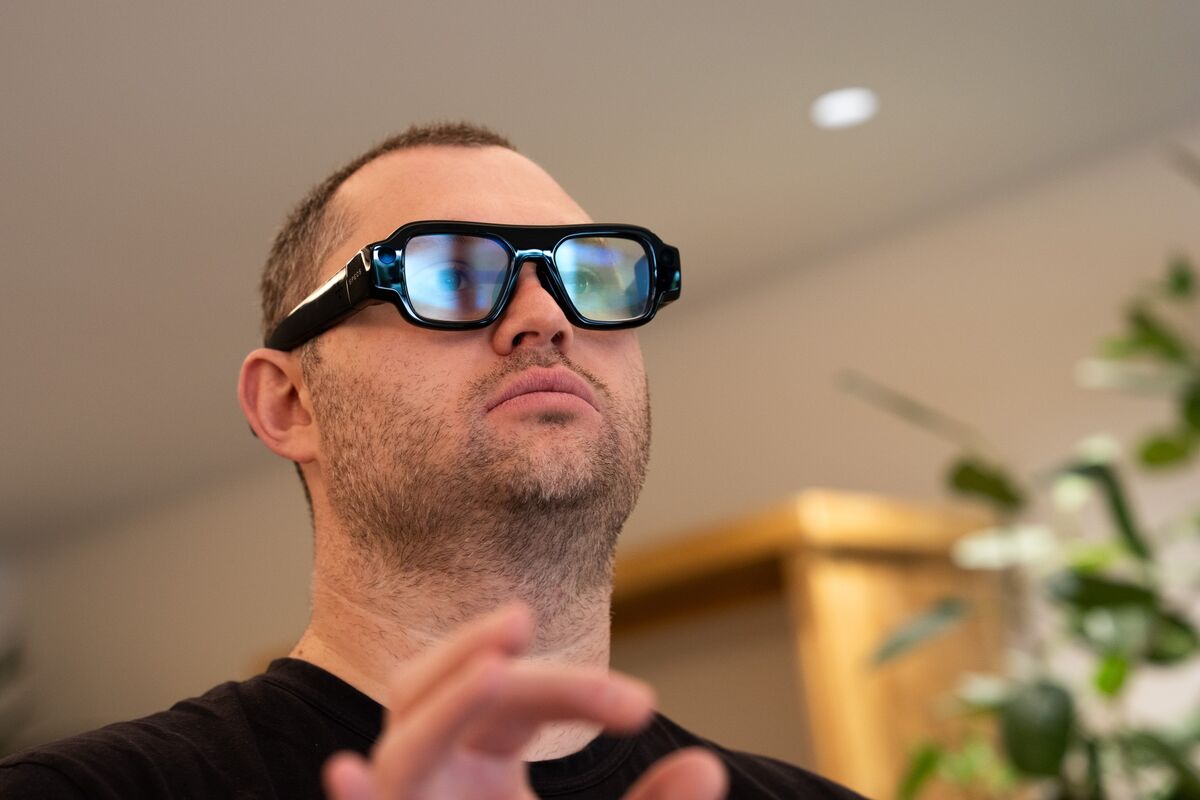
Snap is preparing to launch its $2,195 Specs augmented-reality glasses later this year, targeting early adopters with an integrated-display, self-contained wearable design. A new Verizon partnership will provide in-store product trials at select locations and custom wireless data plans, potentially improving retail distribution and connectivity adoption. The premium price point leaves broad consumer-demand traction uncertain.
Analysis
For SNAP, the relevant valuation question is not initial hardware revenue but whether a wearable endpoint lowers content-creation friction enough to expand daily engagement and advertiser inventory. At a premium price point, early unit volumes are unlikely to move consolidated revenue or EBITDA over the next 1-3 quarters; hardware gross margin, return rates and support costs could instead dilute margins. The strategic upside is a proprietary distribution layer for AR experiences, but this remains a multi-year option whose value depends on repeat usage rather than launch-week sell-through.
VZ gains a modest retail traffic and device-attachment opportunity, but the economics are unlikely to be material unless plans are priced as incremental connected-device ARPU rather than bundled concessions. The more important read-through is competitive: META has substantially greater consumer-wearable distribution, developer funding and ability to subsidize hardware through its advertising base. A credible SNAP consumer launch could nonetheless pressure META to accelerate feature releases and marketing, raising category awareness while likely leaving SNAP with the weaker unit-economics position.
Consensus may overvalue the store partnership as demand validation. Carrier placement reduces purchase friction, but it also creates an observable near-term test: weak availability expansion, heavy promotional support, or muted commentary from VZ would indicate that the device is a demo product rather than a scalable consumer platform. The thesis turns more constructive only if SNAP discloses preorder conversion, recurring software/services monetization, or engagement retention that supports an advertising uplift within 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No directional SNAP position ahead of launch; treat the product as an optionality catalyst rather than an earnings catalyst until management provides unit volume, gross-margin and retention data. A post-launch long is actionable only if guidance implies a measurable revenue contribution without incremental EBITDA-margin deterioration.
- Use SNAP versus META as a tactical relative-value watch: if SNAP rallies more than 15-20% on launch publicity without raised revenue guidance, consider short SNAP / long META for a 1-3 month normalization trade. Falsify if SNAP reports strong reorder demand or demonstrates material AR-ad monetization.
- Do not underwrite VZ earnings upside from the arrangement. Maintain any VZ exposure on wireless cash-flow and capital-return fundamentals; reassess only if VZ discloses connected-device net-adds or premium-plan ARPU attributable to the wearable program.
- Monitor Verizon-store availability, promotional intensity and early return/review patterns during the first 30-60 days. Broad rollout at stable pricing would support category demand; discounting or limited-store containment would be a negative signal for SNAP's hardware-margin and consumer-adoption case.
More News
- Snap tries to bring AR glasses to enterprise market, partnering with Nvidia, AWS and Salesforce
- Why is Snap stock climbing after-hours today?
- Snap launches $2,195 Specs augmented-reality glasses as AI push expands
- Snap tries to make the case again for its $2,200 smart glasses
- Snap launches SPECS Intelligence AI service across devices
- Lagging sector looks poised for a rebound. Here's how Mike Khouw is trading it