
Prediction: Here's What a $1,000 Investment in Archer Aviation Will Be Worth by 2030
Source: fool.com
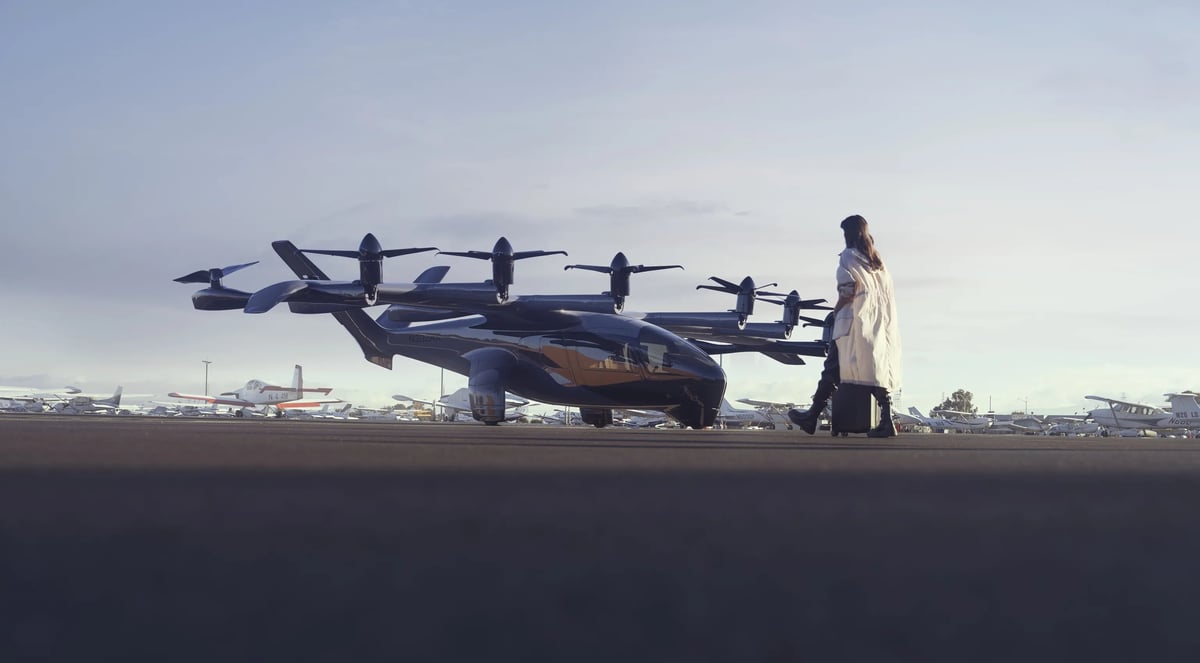
Archer Aviation trades below $4 per share, down from its $9.90 opening price after its Sept. 16, 2021 SPAC merger, amid ongoing losses, no near-term commercial revenue, pending FAA approval and competition from Joby Aviation. Analysts expect revenue to rise from less than $1 million in 2025 to $507 million in 2028; at a $3 billion market cap, the stock trades at six times estimated 2028 sales. A scenario based on meeting estimates, 20% revenue CAGR through 2030 and a 10-times sales valuation implies a potential market cap of $14.6 billion, nearly five times current value, but depends on certification, production ramp-up, backlog conversion and resolving legal disputes.
Analysis
The core risk is not simply a delayed launch: each certification or production slip can extend cash burn before meaningful revenue, increasing the chance that shareholders absorb dilution or that the company must slow its ramp. Verify cash runway, committed funding, and the conditions attached to Stellantis’ manufacturing support; the article does not establish how much production risk Stellantis has actually assumed. Even after certification, aircraft deliveries do not prove attractive route-level economics: utilization, operating costs, infrastructure, and passenger adoption determine whether United Airlines’ intended service becomes a repeatable business or remains a limited deployment.
Joby Aviation’s reported certification lead and aircraft comparisons strengthen its relative position, but do not establish commercial profitability. A sustained lead could help Joby secure early customer confidence and supplier capacity; conversely, an industry-wide certification or infrastructure bottleneck could delay both and blunt the competitive advantage. Archer’s litigation with Joby and Vertical Aerospace adds time and execution uncertainty, not a reliable near-term catalyst in either direction.
The 2030 upside case is a chain of conditional assumptions, including certification, manufacturing scale, backlog conversion, and a generous future sales multiple. Treat it as a scenario, not a valuation floor. Over days, the stock may react to milestone headlines; over 1–3 months, certification progress, cash/runway disclosures, and production evidence matter more than backlog announcements. Over 6–18 months, certification and repeatable production economics are the structural tests. The contrarian point: early aircraft orders and partners can create a perception of de-risking before regulatory approval and unit economics are demonstrated.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Ticker Sentiment
Key Decisions for Investors
- Avoid underwriting ACHR’s long-dated upside scenario as the base case. Keep exposure small until there is verifiable FAA progress and evidence that manufacturing can scale; reassess on certification milestones, production updates, and cash-runway disclosures.
- For a relative-value expression, consider a small, hedged long JOBY / short ACHR position only while the reported certification gap persists and is confirmed by subsequent FAA milestones. Both remain exposed to sector-wide delay; exit or reassess if Archer closes the gap or Joby’s lead fails to translate into commercial progress.
- Do not treat United Airlines’ intended use or Stellantis’ manufacturing role as near-term earnings support for either company. Track actual aircraft delivery commitments, production responsibilities, and route economics before assigning material value to those relationships.
- Falsification / alert: reduce the bearish ACHR view if it obtains certification, demonstrates repeatable production and customer deliveries, and funds the ramp without materially dilutive financing. Escalate caution if FAA milestones slip, cash runway shortens, or manufacturing guidance is deferred.
More News
- Musk's clash with Ukraine accelerates demand for Starlink alternatives. Few exist
- Ukraine Starlink slowdown raises business risks for Elon Musk partners
- Why is JetBlue Airways stock sliding today?
- Cruise lines chase luxury travelers with suites for up to $25,000 a night
- ‘Historic Fuel Cost Pressure' Has American Airlines Slashing Its Forecasts
- Airline Stocks Rise After Southwest's Strong Q3 Results