
HiTHIUM ocupa el segundo puesto a nivel mundial en envíos de baterías para almacenamiento de energía
Source: PR Newswire
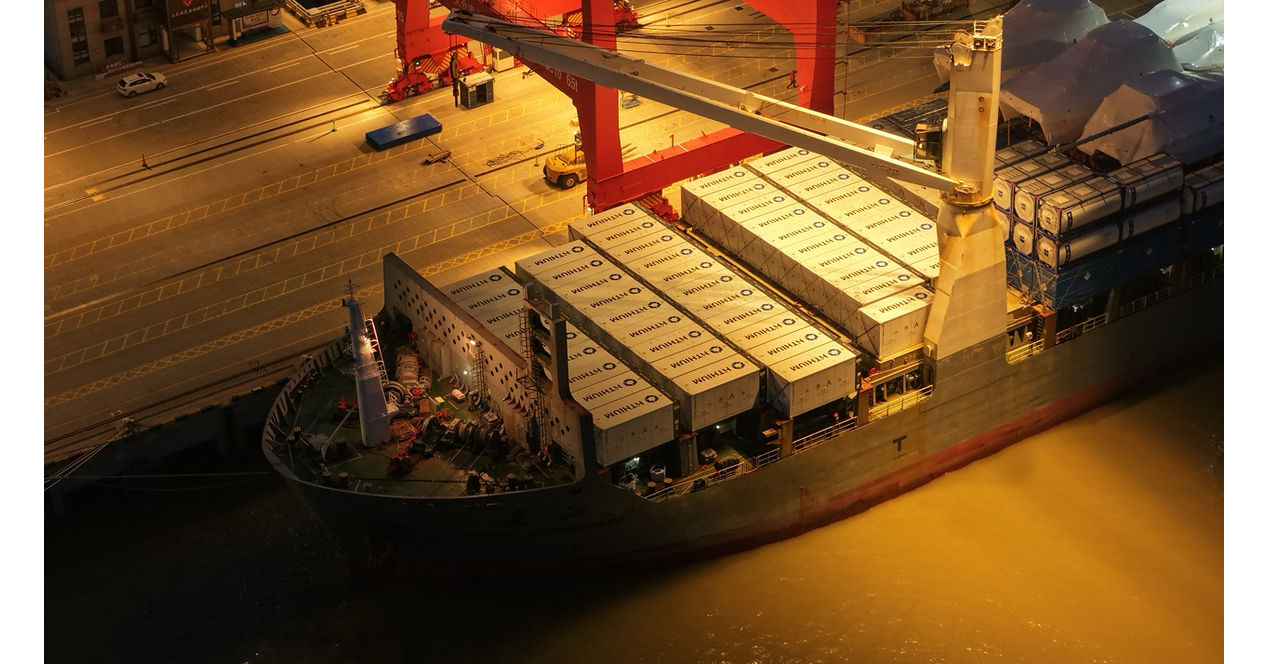
HiTHIUM volvió a ocupar el segundo puesto mundial en envíos de baterías para almacenamiento de energía en el 1S 2026, manteniendo el top-2 por segundo año consecutivo. El mercado creció a 467,84 GWh (+94,76% interanual) y la compañía atribuye su desempeño a capacidades integradas (I+D, fabricación, integración y distribución) con foco en LDES de 4 a 8 horas. En la ejecución industrial, certificó la planta de Chongqing como “Fábrica Faro” (ene-2026), inició producción en el parque integrado de Heze (ago-2026) y comenzó producción en Texas, con planta en España en construcción; el impacto esperado es más de señal estratégica que de movimiento inmediato de mercado.
Analysis
HiTHIUM's ranking matters less than the signal it sends about the supply curve: long-duration storage is moving into a procurement market where delivered cost, bankability, and local assembly will decide share. That is bearish for subscale Western integrators like FLNC, STEM, and EOSE because Chinese leaders can keep pushing pack prices lower while using U.S./Europe footprints to blunt tariff and shipping friction; the margin impact should show up first in bid discipline and backlog quality, then in gross margin over the next 1-3 quarters. The cleaner beneficiaries are grid-adjacent infrastructure names such as ETN and PWR, plus utilities with large renewable portfolios like NEE and AES that can now firm more MW at lower storage cost.
The second-order effect is a shift in the bottleneck: if 4-8 hour systems get cheaper, interconnection, transformers, and permitting become the scarce resources, not cells. That favors the picks-and-shovels around electrification while creating a risk that project developers see returns compressed if storage ASPs fall faster than contracted tariffs; in that case, the market may be underpricing future cannibalization of storage economics even as shipment growth stays strong.
Contrarian view: this is bullish for storage adoption, but not necessarily for public storage equities. The consensus may be extrapolating volume growth without respecting commoditization risk; the better trade is on infrastructure monetizing deployment, not on capital-light hardware assemblers. The thesis is falsified if U.S./EU domestic-content rules tighten enough to protect local incumbents, or if upcoming earnings show ASPs stabilizing and margins expanding despite the competitive backdrop.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- Short FLNC on rallies into the next earnings window (1-3 months); target 15-25% downside if gross margin or backlog mix deteriorates. Falsify if management raises margin guidance or wins materially more domestic-content contracts.
- Pair long ETN or PWR vs short FLNC/STEM over 3-6 months. Rationale: grid equipment monetizes the storage buildout while storage hardware faces price compression; reward/risk is roughly 2:1 if capex demand stays firm.
- Set a watch alert on TSLA energy segment commentary rather than initiating a large position. Long TSLA only makes sense if Megapack growth converts into segment margin expansion; otherwise the storage optionality is too small to matter at the equity level.
- Avoid chasing broad clean-energy ETFs such as ICLN or PBW solely on the headline growth rate; wait for evidence that storage ASPs are holding. If bid prices start falling faster than utilization rises, those ETFs can give back gains quickly.
More News
- Iran-backed Houthis strike Yemen’s Aden: What that means
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- IMF urges support for poorer nations facing high inflation, war spillovers
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)
- AI for M&A Target Screening: From Universe to Deal File