
Einer von dreien: Während Europa auf Elektromobilität umsteigt, baut VinFast für die Zukunft
Source: PR Newswire
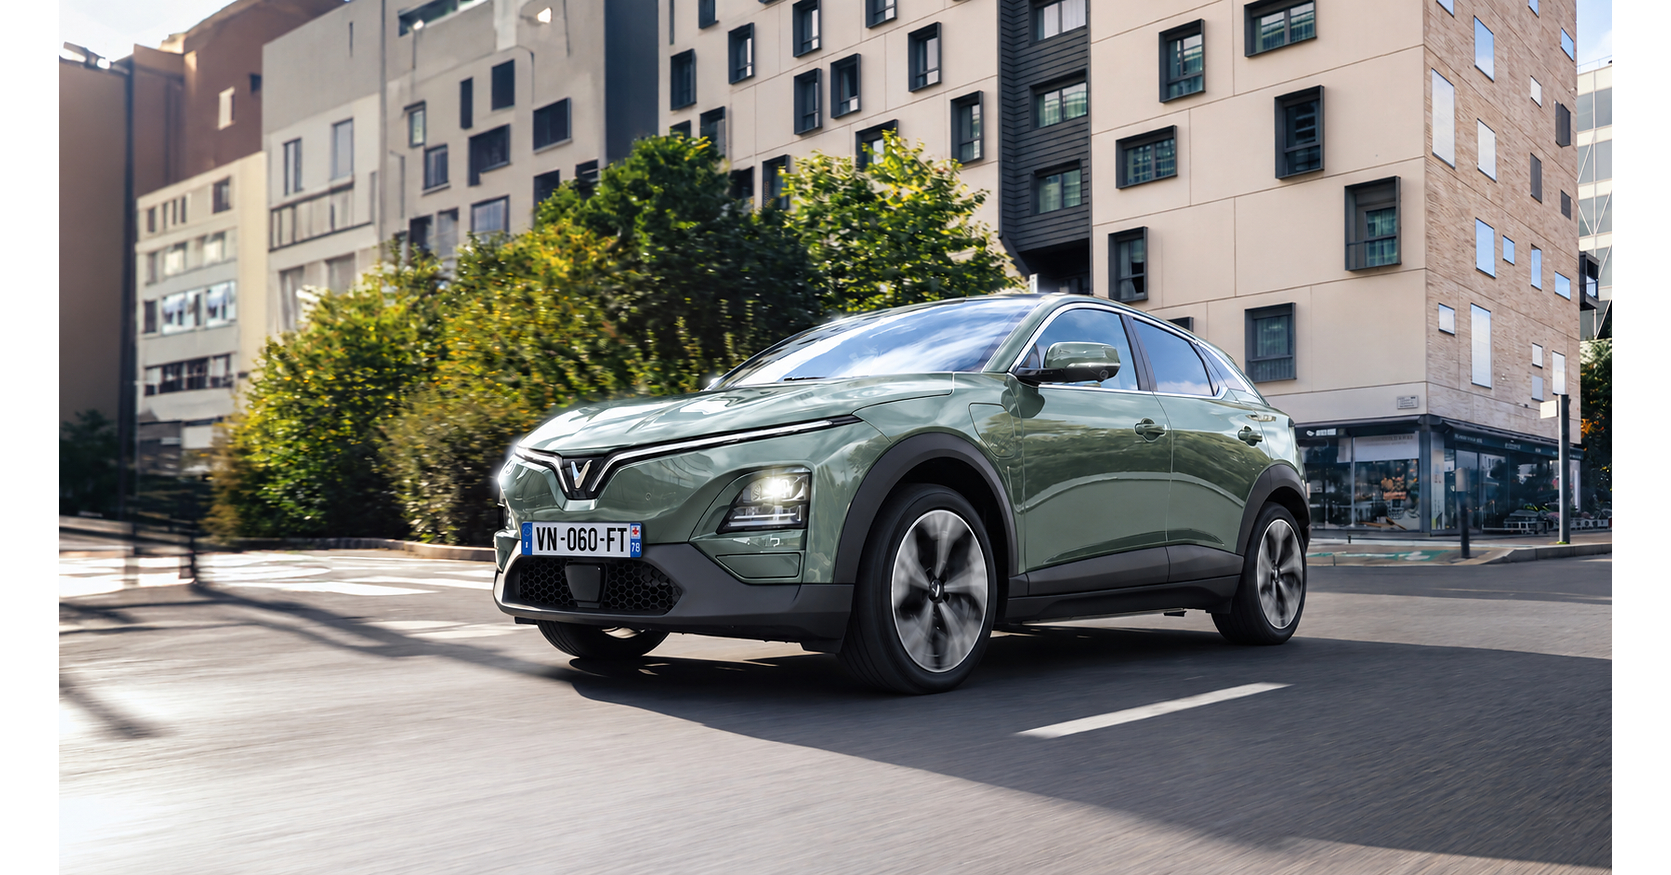
Battery-electric vehicles reached a 30.5% share of new-car registrations across 16 major European markets in August, totaling 202,833 vehicles and rising 54.2% year over year. VinFast is positioning its VF 6 electric SUV and EB 8/EB 12 electric buses for this expanding market, with the EB 12 receiving full European certification and the company building dealer and service partnerships. The announcement supports VinFast's longer-term European expansion narrative, though it provides no sales, financial, delivery, or profitability targets.
Analysis
This is promotional positioning rather than evidence of incremental orders, funded capacity, dealer economics, or service-network density; it should not change VFS estimates absent disclosed European registrations, fleet contracts, and warranty/residual-value data. Europe’s faster BEV adoption expands the addressable market, but it also shifts the bottleneck from product availability to homologation, parts availability, financing, and uptime—areas where incumbents and scaled Chinese exporters have materially stronger local infrastructure.
For VFS, the bus initiative is strategically more consequential than consumer vehicles over 6-18 months: municipal procurement can create visible multi-year volume, service revenue, and reference customers. But public tenders are lengthy and price-led; winning certified access is not equivalent to winning contracts. The likely near-term beneficiaries of accelerating European electrification remain suppliers with regional content and installed bases—VOW3, RNO, STLA, VLVLY and bus incumbents Daimler Truck (DTG) and Traton (8TRA)—rather than a new entrant whose European fixed-cost and working-capital needs could rise ahead of revenue.
Consensus may overvalue the headline market-share growth while underweighting competitive intensity. As EU demand broadens, OEMs can use BEV mix to satisfy fleet-emissions requirements, sustaining discounting and residual-value pressure; that is unfavorable for unproven brands dependent on attractive lease payments. A credible VFS re-rating needs independently reported quarterly European deliveries, named dealer/service partners, tender wins with unit and value disclosure, and evidence that gross margin does not deteriorate as European launch costs scale.
Over days, this is likely a low-quality sentiment catalyst for VFS given the absence of a quantified commercial event. Over 1-3 months, monitor European registration data and procurement databases for validation; over 6-18 months, the key question is whether fleet sales cover local service, inventory, and spare-parts investment before additional external financing is required. The bearish operational thesis is falsified by repeat fleet awards, rising European registrations without elevated incentives, and disclosed gross-margin resilience.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No new directional VFS position on this release. Create a 1-3 month alert for disclosed European registrations, signed municipal bus awards, dealer count, and warranty/service provisions; absent these, treat any rally as liquidity-driven rather than fundamental.
- If VFS rallies more than 20% on Europe narrative without a named order or delivery guidance increase, consider a small tactical short or put spread, sized for high volatility and borrow risk. Cover on a disclosed fleet contract with contract value/units or a material upward revision to delivery guidance.
- For a cleaner 6-18 month electrification exposure, favor long VLVLY or DTG versus short VFS only after confirming comparable valuation and borrow availability: incumbents monetize installed service networks and fleet uptime requirements, while VFS bears market-entry working-capital risk.
- Watch European BEV incentive changes and lease residual-value data over the next two quarters. A renewed subsidy regime or materially improving residual values would reduce price competition and weaken the short-VFS/long-incumbent relative thesis.
More News
- States, cities sue U.S. agencies over weaker vehicle fuel economy rules
- Trump vs Europe as US presses for release of emergency diesel stocks
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- FAA says Boeing 737 Max software glitch not a flight-safety issue
- Paramount and Warner Bros. Discovery to Merge Into Skydance (SKYD). Will Skydance Achieve David Ellison’s "Quality Storytelling" Vision?
- Hackers Breached Propulsion System of US-Bound Oil Tanker