
Envision Energy uvádza na trh pevninskú veternú turbínu Model T - EN175/8.0, ktorá zlepšuje optimalizáciu celej elektrárne a zvyšuje hodnotu životného cyklu budúcich energetických systémov
Source: PR Newswire
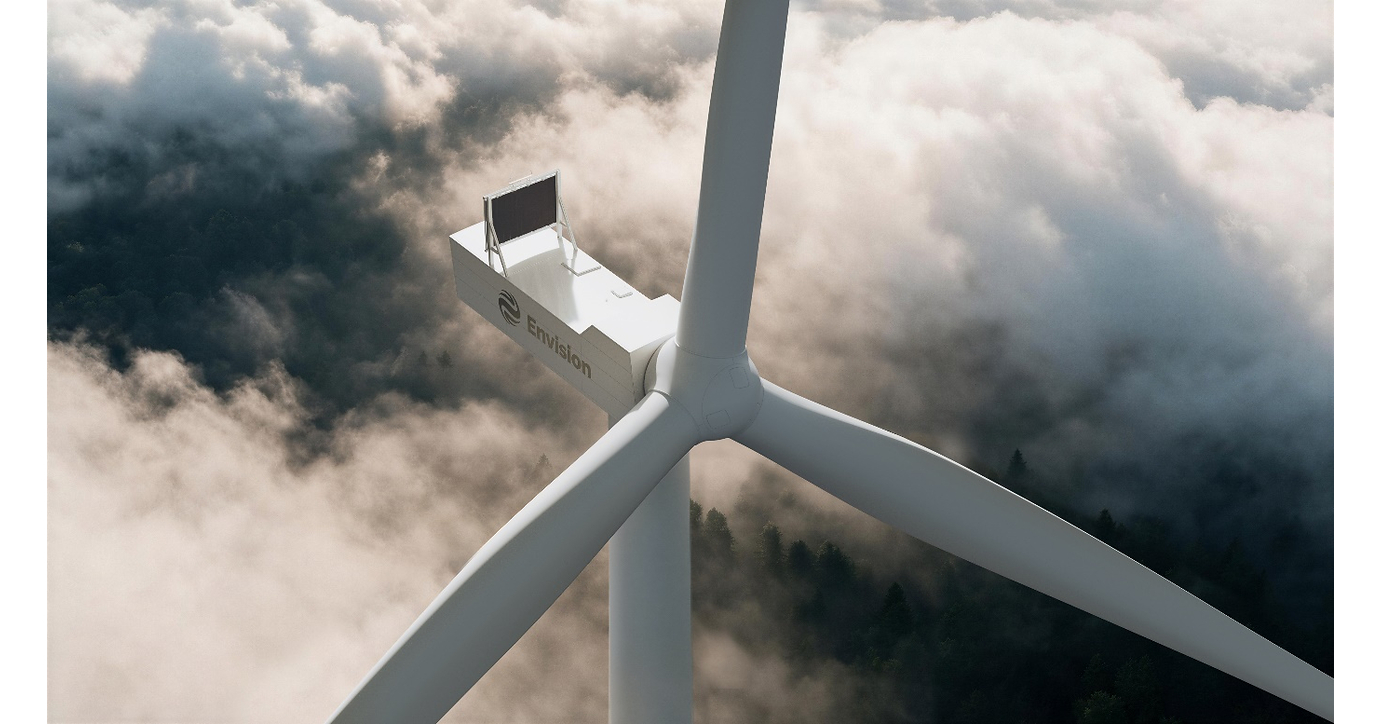
Envision Energy launched its Model T EN175/8.0 onshore wind turbine, featuring 8 MW capacity and a 175-meter rotor, targeting medium-wind and complex operating sites. The company says the turbine can raise energy yield by 2%-12% versus existing models, while AI-driven Galileo controls autonomously optimize operations using real-time weather and energy-system data. Built on a platform with more than 4,000 units ordered and about 1,500 installed, the product adds grid-forming capabilities, low-noise operation targeting 107 dB(A), and optional cold-climate and anti-icing configurations.
Analysis
This is primarily a competitive tender signal rather than an investable earnings catalyst: a credible 8MW onshore offering raises the performance threshold in medium-wind projects, where balance-of-plant costs and permitting constraints make rotor sweep and availability more valuable than nameplate capacity. The likely pressure falls on Western OEMs Vestas (VWS.CO) and Nordex (NDX1.DE) in export-eligible markets, particularly if Envision can pair turbine pricing with internal component supply and financing. Siemens Energy (ENR.DE) is less directly exposed in onshore volume but could face pricing pressure where customers value grid-forming capability.
The important unverified variable is field availability, not claimed energy-yield uplift. Larger rotors increase logistics, blade-erosion and drivetrain-load risk; any warranty reserve or commissioning issue would rapidly offset nominal LCOE gains. Over the next 1-3 months, monitor disclosed European order intake, certification milestones, local-content arrangements and bankability endorsements. Without those, the launch should not change consensus estimates or justify a directional sector position.
Over 6-18 months, grid-support functionality may shift procurement toward OEMs that can guarantee plant-level performance rather than sell hardware at low gross margins. That is potentially positive for grid-equipment vendors ABB (ABBN.SW), Schneider Electric (SU.PA) and Hitachi Energy-related supply chains, as weak-grid projects require more power electronics, controls and interconnection equipment. Contrarian view: AI optimization is unlikely to earn a standalone valuation premium; developers will demand contractual availability and production guarantees, leaving much of the economic benefit with project owners unless the OEM can demonstrate lower service cost and accept limited performance-risk exposure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No immediate directional trade: treat the announcement as an order-intake watch item, not a forecast-changing event. Reassess after independently disclosed European awards or certification; absent these within 6-12 months, competitive impact is likely limited.
- Establish a 3-6 month relative-value watchlist: long ABBN.SW or SU.PA versus short VWS.CO only if European onshore tender specifications increasingly require grid-forming or weak-grid capability. Target 10-15% relative upside; exit if Vestas order pricing/EBIT margin remains stable or improves.
- For VWS.CO and NDX1.DE, monitor next two quarterly order books for declining average selling prices, higher warranty provisions, or margin-guide cuts. A combined 100bp gross-margin deterioration tied to Chinese competition would validate a tactical underweight; stable pricing falsifies the thesis.
- Avoid extrapolating AI claims into AI-software exposure. The investable confirmation would be disclosed service-margin expansion, lower unplanned-maintenance rates, or contractual production guarantees—not turbine marketing metrics.
More News
- Trump-Xi summit analysis: 'Tangible outcomes' needed for U.S.-China truce to hold
- Anthropic CEO Amodei to have dinner with Trump at White House
- Here are the 4 big things we're watching in the stock market in the week ahead
- The U.S. economy is running hot and stuck on a hamster wheel as GDP growth must outpace borrowing costs—or else get sucked into a debt spiral
- Debt-hungry AI companies face increased risk as bond yields spike
- Yemen government forces widen attacks against Houthis: What we know
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More
- AI Tools for Family Offices: A Stack by Decision Type