
Miral investiert 12 Milliarden AED, um die nächste Wachstumsphase von Yas Island zu gestalten
Source: PR Newswire
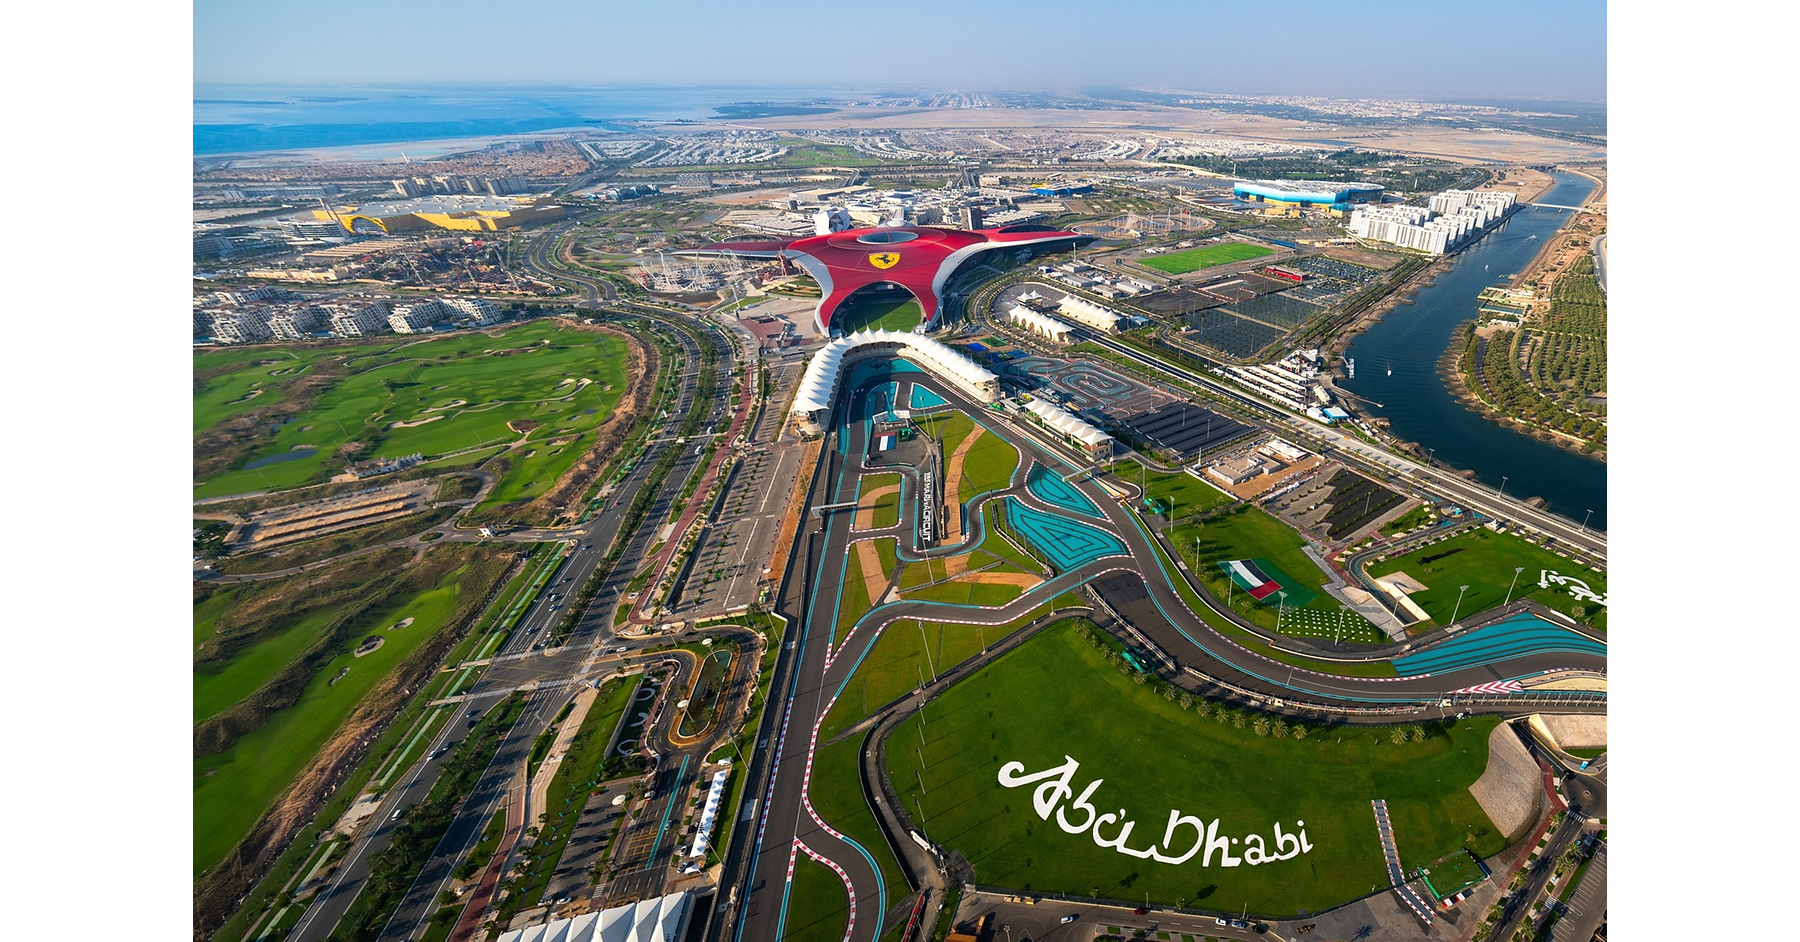
Miral will invest more than AED 12 billion over the next five years to expand Yas Island’s theme parks, attractions, hospitality capacity, dining and leisure offerings. The spending, separate from the previously announced Disney project, supports Abu Dhabi Tourism Strategy 2030 and is intended to increase visitor appeal, create jobs and deepen the emirate’s tourism-led economic diversification. The program is a material positive catalyst for Yas Island’s leisure and hospitality ecosystem, though it is primarily a long-term private development initiative rather than a broad public-market driver.
Analysis
The read-through for DIS is strategically positive but financially immaterial near term: a larger destination ecosystem should raise the value of Disney’s regional intellectual-property presence, extend guest length of stay, and improve the economics of future licensing, merchandise, and hotel-adjacent revenue without requiring Disney to fund local infrastructure. The key distinction is that Miral-funded surrounding capacity can improve the eventual Disney project’s ramp profile, but it does not justify changing DIS consolidated EPS estimates before contractual royalty terms, opening dates, or attendance assumptions are disclosed.
The more investable second-order effect is a Middle East leisure-capacity arms race. Abu Dhabi is attempting to convert transit and luxury travel demand into multi-night family stays, pressuring Dubai’s incumbent attractions and hotels at the margin while increasing regional demand for global brands, operators, and airline connectivity. HLT and MAR may benefit through management/franchise fees if branded rooms are part of the buildout, but neither has sufficient disclosed exposure for an immediate earnings trade; UAE construction beneficiaries are mostly private or not cleanly accessible through U.S.-listed equities.
Consensus may overstate the near-term Disney catalyst because destination construction has long permitting, design, and phased-opening cycles. Over 1-3 months, this is primarily narrative support for DIS’s Experiences multiple; over 6-18 months, the relevant catalyst is evidence that the regional platform creates incremental, rather than substituted, international visitation. A weaker oil-price environment, reduced Gulf consumer spending, airline-capacity constraints, or evidence of discounting at competing regional parks would challenge the assumed premium-demand model.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Maintain, do not add to, DIS on this announcement alone; treat it as a 6-18 month valuation-support datapoint rather than an earnings catalyst. Add only if management discloses minimum guarantees, royalty economics, or a funded opening timetable that can support measurable Experiences revenue estimates.
- Set a DIS watch trigger around quarterly Experiences guidance: upgrade the regional thesis only if management attributes incremental international licensing or consumer-products growth to the Middle East while domestic parks pricing remains resilient. Falsifier: guidance indicates higher international development expense, weaker park margins, or no monetization disclosure.
- Avoid a directional HLT or MAR trade until property flags, room counts, and ownership/management structures are published. A viable 12-24 month relative-value expression would be long the operator securing the largest fee-bearing Yas Island pipeline versus the other, contingent on disclosed pipeline additions and RevPAR assumptions.
- For portfolios already long DIS, fund any incremental exposure by reducing a more purely domestic discretionary leisure holding rather than adding gross beta: regional development diversifies Disney’s long-duration Experiences narrative, but its near-term cash-flow contribution remains too uncertain to warrant a standalone event position.
More News
- In pro sports, even the superrich are being priced out of owning a team
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- The UK cuts energy bills, taxes banks and boosts defense in high-stakes budget
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off