
The U.S. budget deficit just hit almost $2 trillion — and Washington isn’t doing much about it
Source: MarketWatch
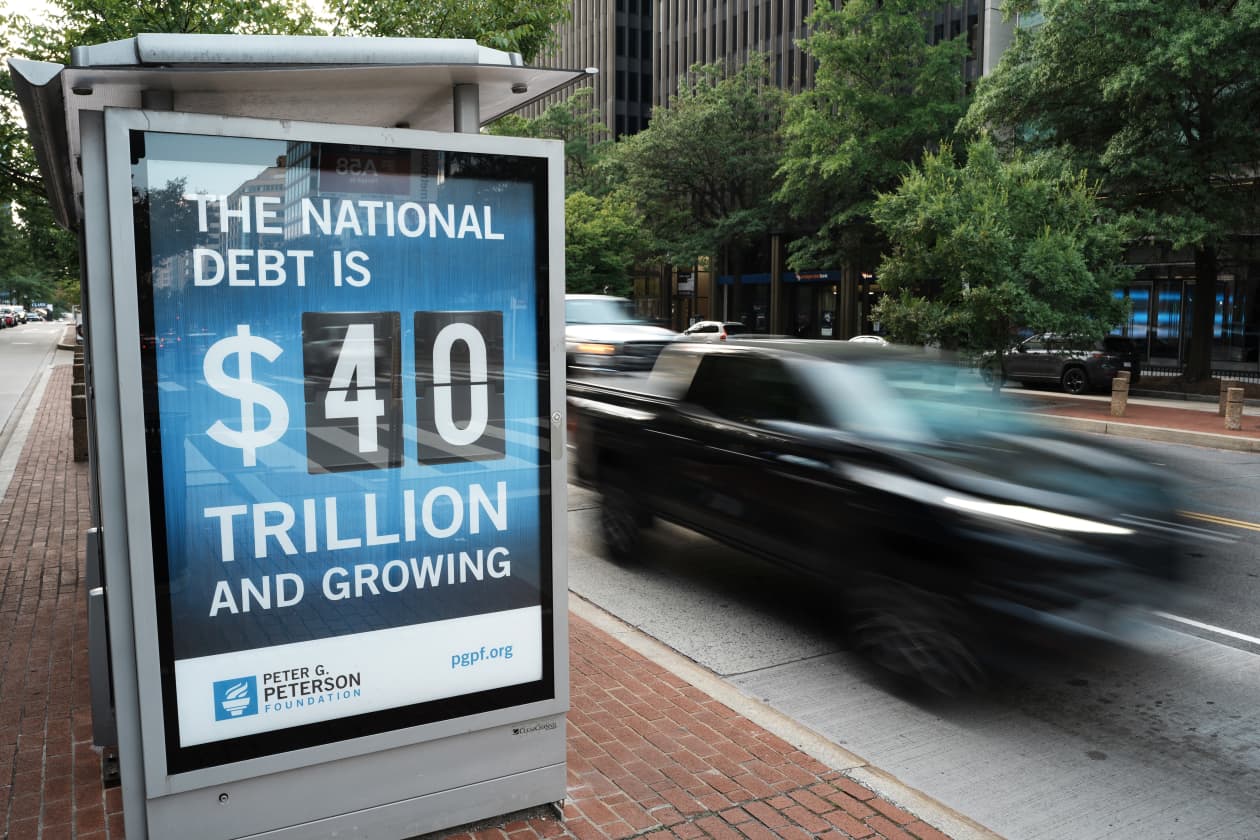
The U.S. federal budget deficit reached $1.992 trillion in the fiscal year ended Sept. 30, the largest since 2021, according to the Treasury Department. Treasury officials estimated the deficit at 6.2% of GDP; the article says Washington is not doing much to address it.
Analysis
The key market channel is marginal Treasury absorption, not the headline deficit figure itself. Persistent heavy borrowing—especially alongside ongoing balance-sheet runoff—could lift term premium and make long-duration assets more vulnerable even if the Federal Reserve cuts short rates. That creates a potential headwind for long-duration equities and rate-sensitive borrowers, but the effect is not automatic: weaker growth, safe-haven demand, or strong auction demand could pull yields lower and overwhelm the supply impulse.
Over the next 1–3 months, watch auction tails and bid-to-cover, refunding guidance, term-premium estimates, and the 5s30s curve. These will show whether fiscal supply is changing the clearing price or merely reinforcing a concern already reflected in rates. Over 6–18 months, persistent deficits could increase sensitivity to inflation surprises and constrain policy flexibility; a credible fiscal plan or sustained private demand for duration would weaken that thesis.
Contrarian view: a large deficit is not, by itself, a near-term Treasury short. Growth or inflation disappointment can still produce a rally, and the fiscal concern may already be priced. Keep any expression modest and define the reversal in market terms rather than assuming a political response.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Key Decisions for Investors
- Consider a modest, DV01-neutral 5s30s Treasury steepener, preferably on a long-end rally or auction concession rather than chasing a selloff. The thesis is rising long-end term premium relative to policy-sensitive yields; reduce or exit if long-end auction demand strengthens persistently and the curve flattens.
- Avoid adding unhedged long-duration equity exposure solely on the assumption that policy-rate cuts will lower discount rates. Favor balance sheets and cash flows less sensitive to long-term financing costs; reassess if long yields fall alongside softer inflation and growth data.
- Treat a sustained rise in auction tails or term premium as a confirmation signal, not the deficit headline. If auctions clear firmly and term premium declines, the supply-driven bearish-rates thesis is not working and the steepener should be cut.
- No immediate broad USD or inflation trade is justified by this report alone; verify issuance composition, foreign and domestic auction demand, and inflation expectations before expressing those secondary effects.
More News
- U.S. budget deficit swells to almost $2 trillion for fiscal 2026, up 12% in a single year
- For one grocery chain, the cost to ship lettuce now tops the lettuce itself, showing how high fuel prices are sinking their teeth across the economy
- How Iran messaging highlights cost of war ahead of US midterm elections
- Major earnings reports are due next week, but strong results may not be enough to quell market fears
- Why is SPDR S&P 500 ETF Trust sliding today?
- Banking tax raid fears hit London lenders' shares ahead of crucial budget