
Building Bridges for the Right to Worship Act
Source: PR Newswire
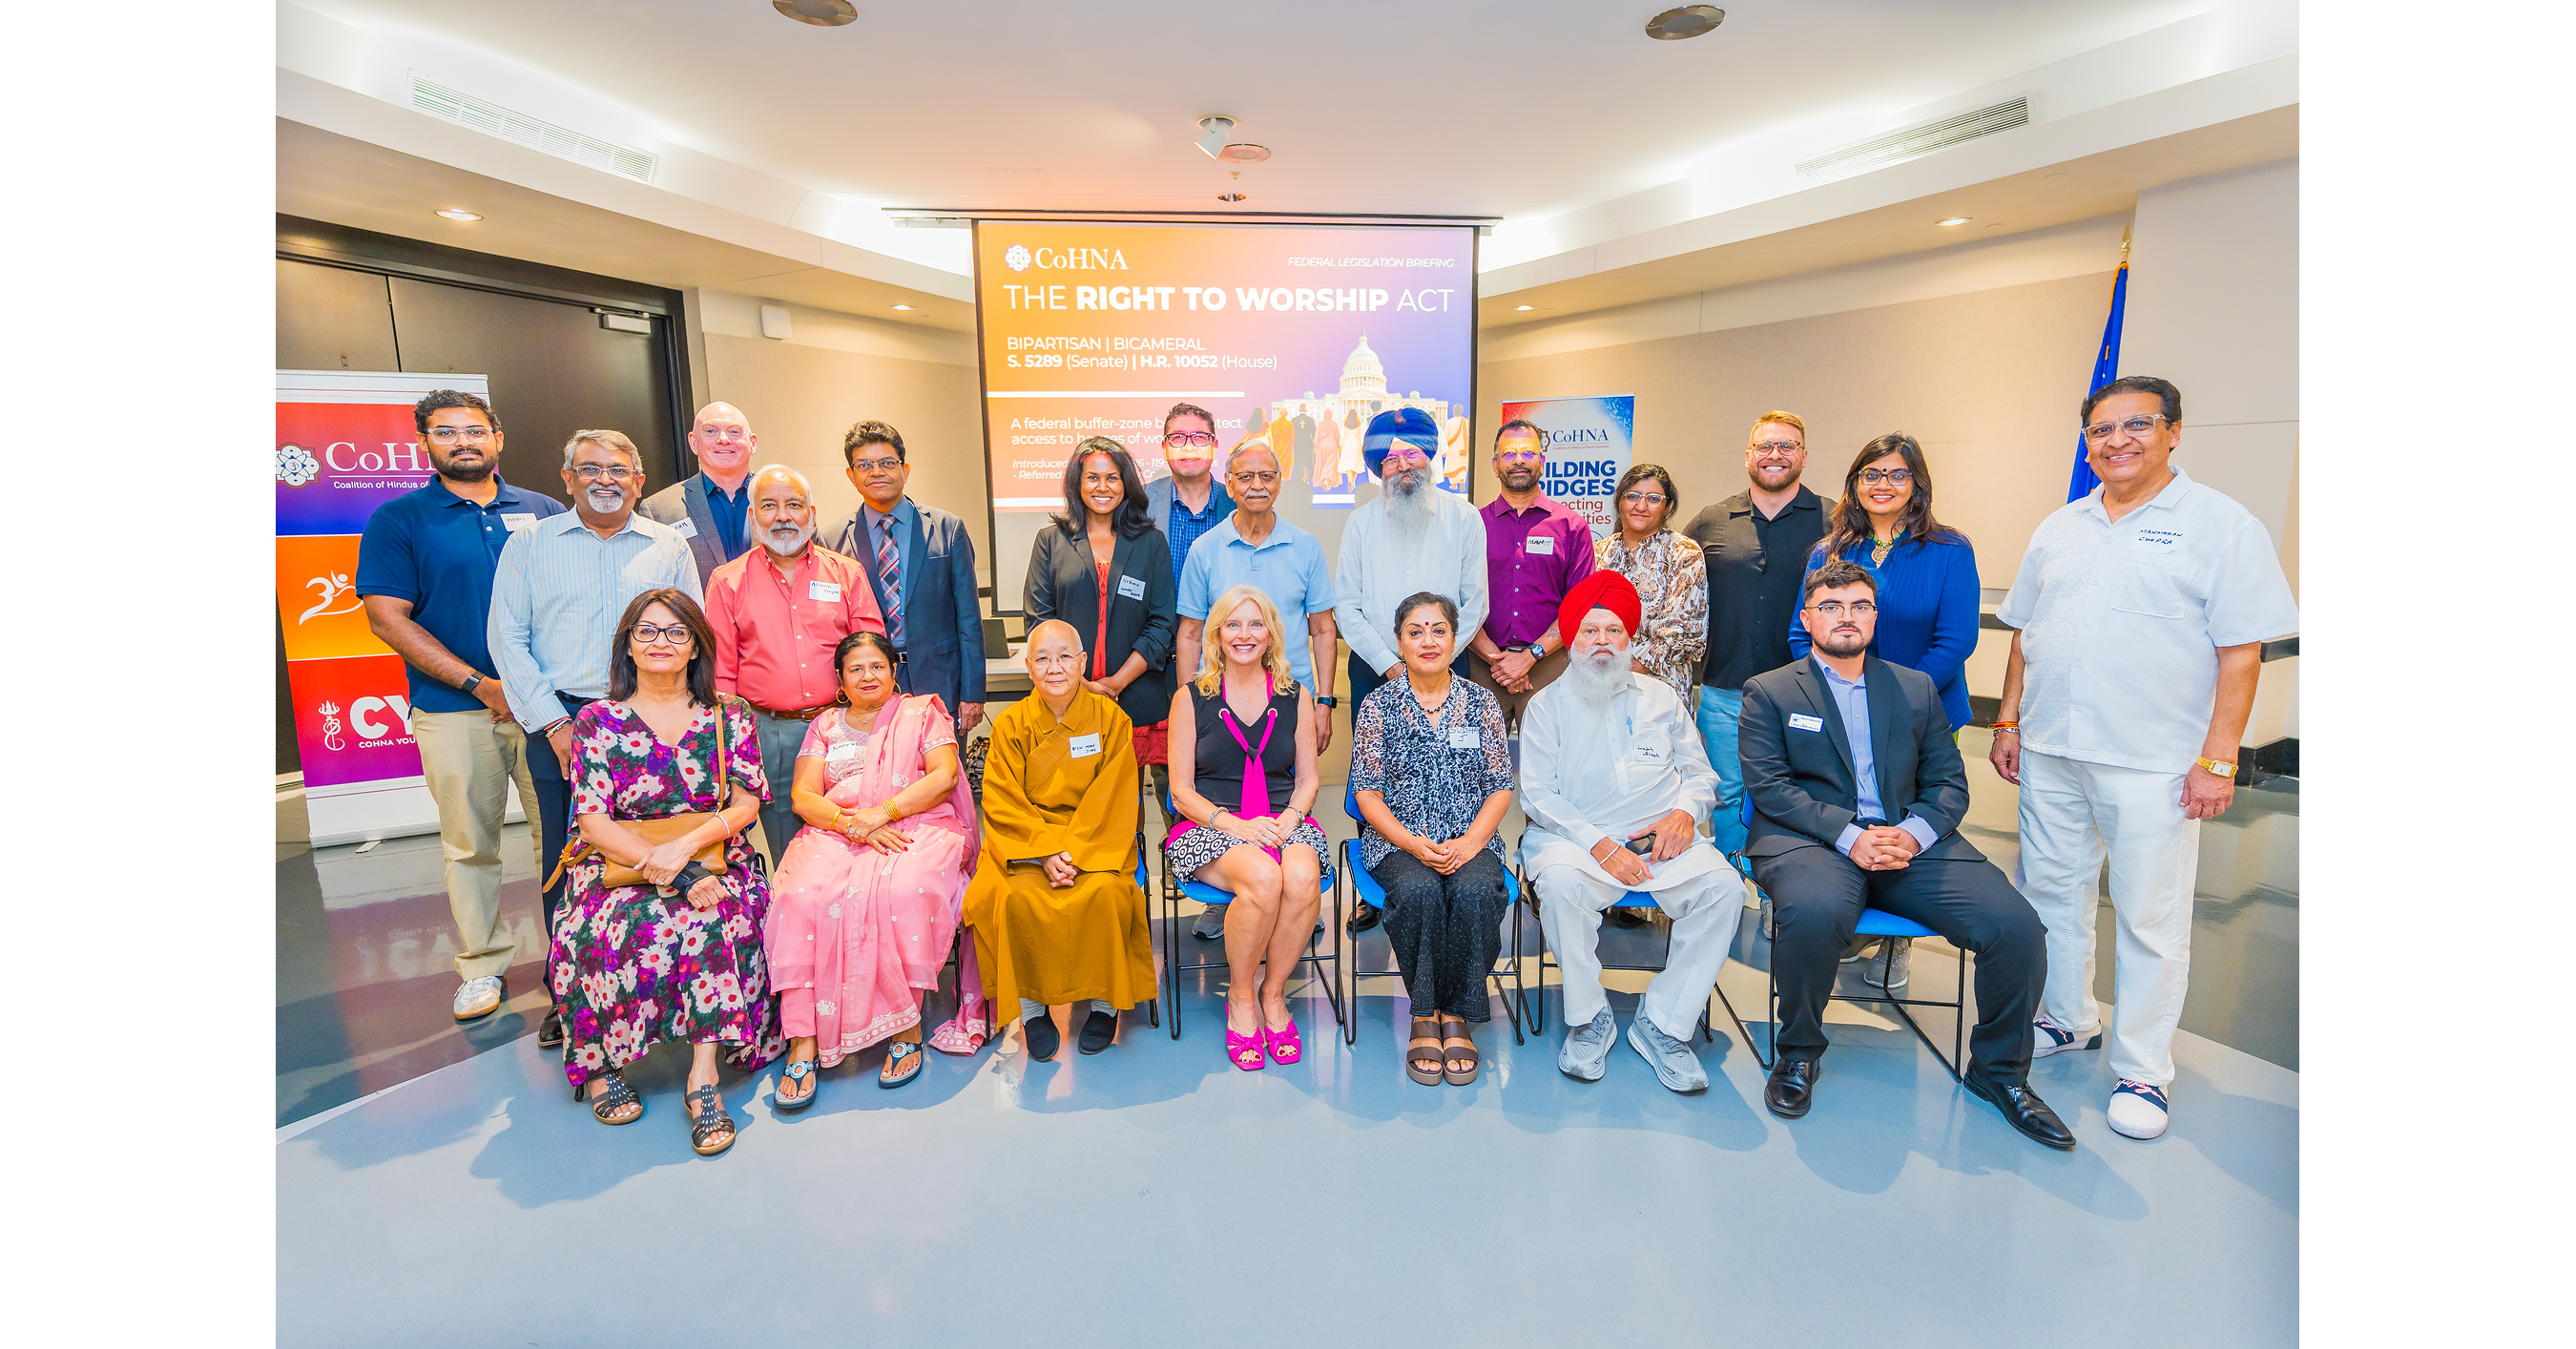
CoHNA held a Las Vegas interfaith event and joined a Capitol Hill press conference to advocate for the bipartisan Right to Worship Act, which would establish a 100-foot protest-free buffer around houses of worship during services while preserving First Amendment-protected peaceful expression. More than 30 national religious organizations support the proposal, whose House leads are Reps. Tom Suozzi and Brad Knott and whose Senate companion was introduced by Sens. Ted Cruz and Elissa Slotkin. The advocacy cites rising religious hostility, including 12 Hindu temples allegedly desecrated, vandalized, threatened, or targeted since 2022, but the article provides no legislative vote timetable or financial-market implications.
Analysis
This is not presently an investable equity catalyst: the proposed federal standard has no identified public-company revenue pool, and legislative endorsement activity should not be confused with a defined path to enactment. The nearer-term market implication is confined to local operating practices for venues, universities, private security contractors, and insurers if the proposal gains committee traction; any cost impact would likely be immaterial and dispersed rather than concentrated in a listed issuer.
The meaningful second-order risk is constitutional litigation. A buffer-zone statute that survives judicial scrutiny could create a broader precedent for regulating conduct around politically sensitive private institutions, while an early injunction would reinforce the legal ceiling on such restrictions. Over the next 1-3 months, monitor bill text, committee scheduling, and whether civil-liberties groups publicly challenge the scope; without those developments, this remains a policy signal rather than a tradable event. A six- to eighteen-month effect would require passage, implementing guidance, and evidence that insurers or security vendors can reprice exposure.
Consensus should resist extrapolating heightened attention to religious-site security into a broad defense or security-services trade. Fragmented demand, procurement lag, and the likely reliance on existing local law-enforcement arrangements limit incremental spend. The thesis changes only if federal funding, mandates for accredited security, or a material rise in reported incidents produces measurable contract awards or insurance-rate changes.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.12
Key Decisions for Investors
- No directional position recommended at current information value; maintain as a legislative watch item rather than an event trade.
- Set alerts for committee markup, Congressional Budget Office scoring, and any federal grant or reimbursement provision. A funded implementation mechanism would be the threshold for screening security-services and specialty-insurance beneficiaries.
- Monitor public filings and earnings commentary from private-security proxies such as Allied Universal's publicly traded peers, as well as specialty insurers including RLI (RLI) and Kinsale (KNSL), for religion- or event-security pricing language over the next two quarters; do not initiate solely on legislative headlines.
- Treat a preliminary injunction or First Amendment challenge as a falsifier of any prospective security-demand thesis; conversely, passage plus appropriations would justify reassessing localized contract beneficiaries within 6-12 months.
More News
- Trump signs sweeping Russia sanctions over Ukraine war
- Google's Gemini becomes latest AI model to break out and hack computer systems
- Trump says U.S. to build a 'large Military presence' in Greenland as part of a security deal with it and Denmark
- After threatening to seize Greenland by force, Trump agrees to leave it with Denmark and boost military presence. ‘We will be very protective of it!’
- Google’s Gemini AI hacks 3 companies in security test, then stops
- Flock Offers Employees Buyouts as Customers Flee
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- AI Software for Buy-Side Teams: Build the Research Stack