
WOWorks Unveils Three-Tier Incentive Program to Accelerate Franchise Growth Across Portfolio
Source: PR Newswire
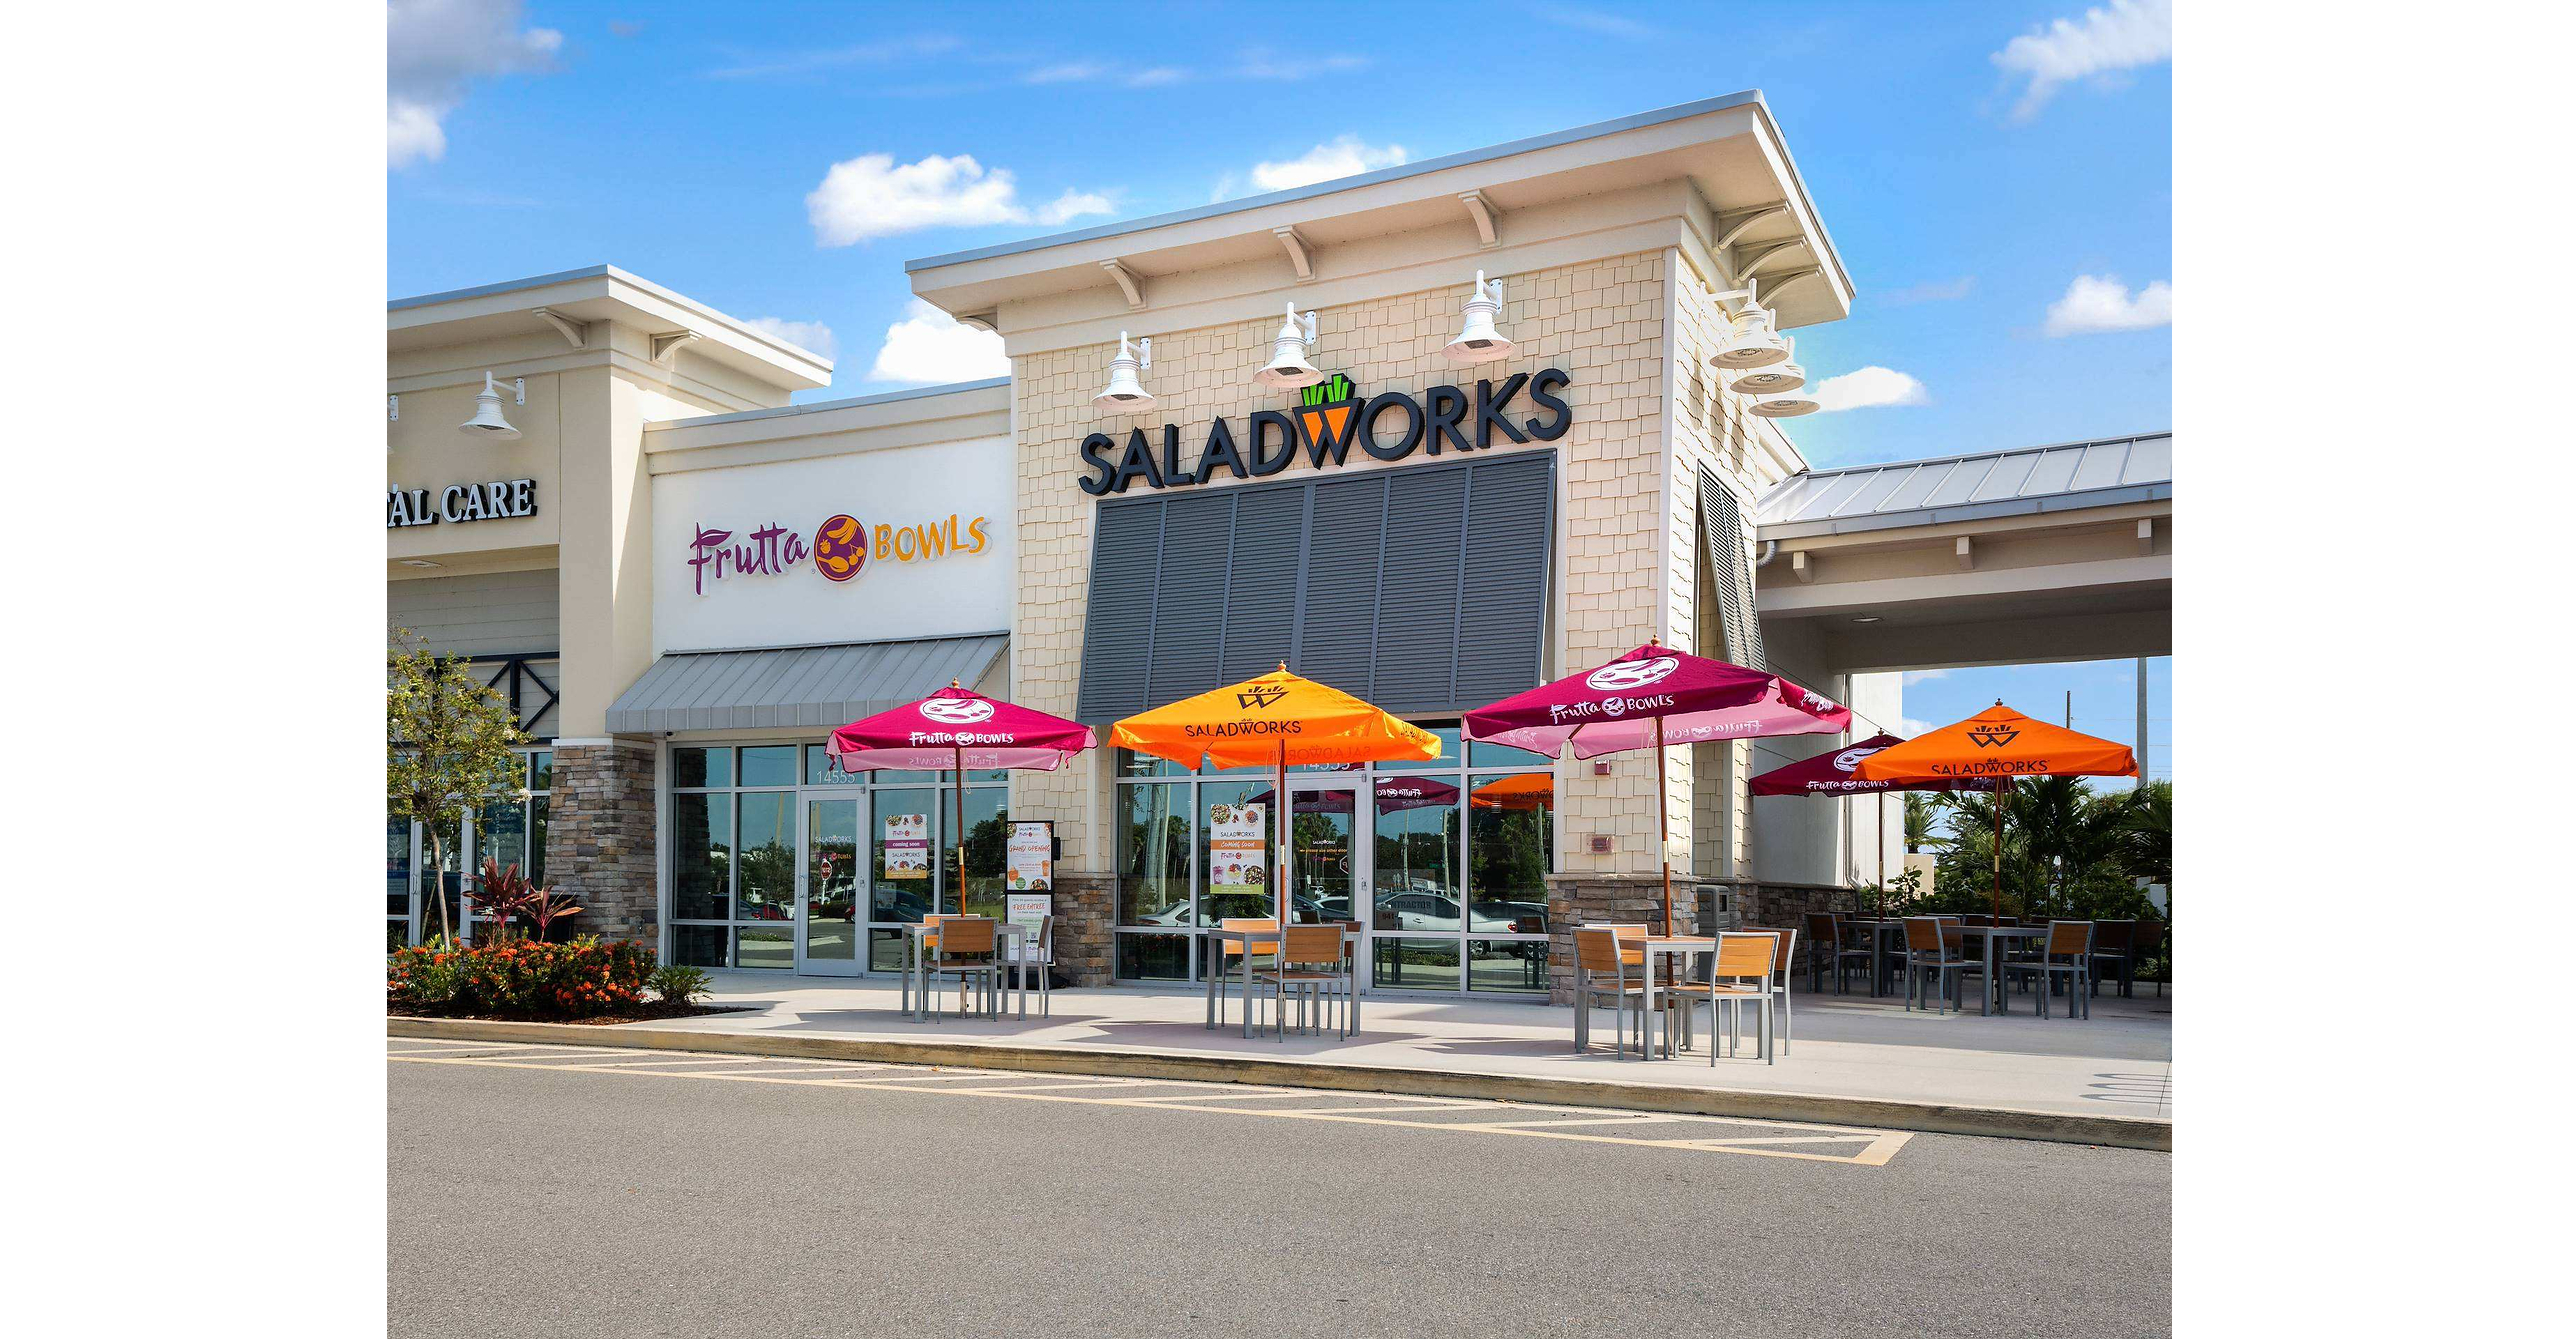
WOWorks launched a limited-time, three-tier franchise incentive program through Q1 2027, offering 50% royalty reductions for six to 12 months and a net $0 franchise fee on the first three locations for developers committing to six or more restaurants. The company also introduced a co-branding offer that lets franchisees add a second WOWorks concept at an existing site without an additional franchise fee. The initiative is intended to accelerate expansion across WOWorks' nearly 240-unit, better-for-you restaurant portfolio while lowering operators' upfront development costs.
Analysis
This is principally a private-market signal rather than a public-equity catalyst: WOWorks is using upfront fee and early-royalty concessions to reduce franchisee cash-on-cash hurdles, suggesting unit-development economics remain difficult to underwrite at prevailing restaurant build-out costs and traffic uncertainty. The co-branding structure can improve four-wall leverage by spreading occupancy and labor across a broader daypart/menu mix, but it also raises execution risk through greater SKU complexity, throughput constraints, and potential brand dilution. The financial benefit to the franchisor is therefore deferred rather than eliminated: lower near-term fee/royalty revenue is exchanged for a larger contracted pipeline whose realization depends on franchisee financing and development compliance.
The more relevant read-through is competitive. Asset-light franchisors with stronger brand awareness, lender relationships, and proven same-store sales should be able to defend economics without comparable concessions; this marginally favors YUM, DPZ, WING and CAVA over smaller, subscale fast-casual systems competing for the same experienced multi-unit operators. Conversely, aggressive incentive packages across emerging concepts would be a warning that franchisee demand is becoming price-sensitive, potentially pressuring development-fee income and long-run royalty growth for lower-scale peers.
No direct trade follows absent evidence that incentives produce signed development commitments, openings, or materially better unit-level sales. Over the next 1-3 months, monitor franchise disclosure filings, operator financing availability, and restaurant construction costs; over 6-18 months, the relevant test is whether co-branded units sustain sales productivity without elevated closure or transfer rates. A broad decline in rates or a meaningful recovery in fast-casual traffic would reduce the need for concessions and improve the outlook for growth-oriented restaurant franchisors.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No standalone position: WOWorks is privately held and the announcement has insufficient verified financial information to support a public-market trade.
- Maintain a relative-quality watchlist: favor YUM and DPZ versus subscale franchise-growth stories if further fee/royalty incentives emerge industry-wide; revisit only if company disclosures show slowing net unit development or higher franchisee churn. Time horizon: 6-18 months.
- Use quarterly earnings from WING, CAVA, YUM and DPZ to monitor development pipelines, franchisee opening costs, and same-store sales. A broad increase in development incentives or a deceleration in signed commitments would support a defensive tilt within restaurant equities; stable pipelines without concessions would falsify that concern.
- Watch restaurant labor, construction-cost inflation, and small-business lending conditions through Q1 2027. Easing financing conditions would make new-unit growth more credible and could support long CAVA/WING on a 6-12 month horizon; persistently high financing costs would favor mature, cash-generative franchisors over expansion-dependent concepts.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)
- AI Portfolio Monitoring: Build an Alert Policy Analysts Can Audit