
Billions Pour Into AI as Manus Rebounds and Huawei Speeds Chips
Source: Bloomberg
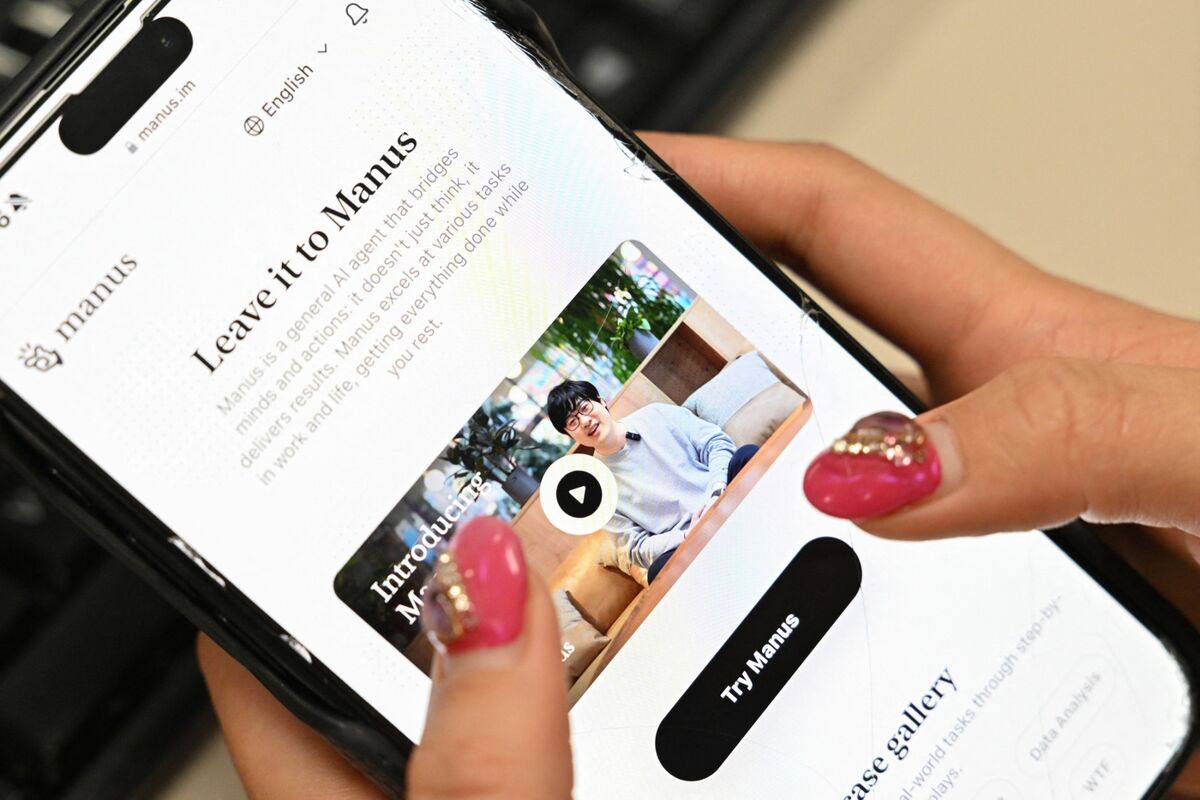
Chinese-founded AI startup Manus is raising about $500 million at a $4 billion valuation, double Meta's previously agreed $2 billion acquisition price after Beijing forced the deal to unwind. Separately, Nvidia partner GMI Cloud is seeking a $300 million bank and private-credit loan to finance chips for a Thailand data-center facility whose computing capacity is set to be used by Tencent. The developments underscore sustained AI capital inflows and an emerging lending market in which high-cost AI chips, rather than only data-center infrastructure, are becoming financeable assets.
Analysis
The important signal is not the private valuation uplift; it is Beijing’s demonstrated ability to reallocate the economics of strategically sensitive AI assets away from US acquirers. META’s direct financial exposure is immaterial, but the precedent increases execution risk for any cross-border acquisition involving Chinese-origin models, data, or engineering teams. Over 6-18 months, this favors firms with domestically ring-fenced China operations and penalizes platform valuations that embed global access to AI talent, IP, and distribution without a clean regulatory perimeter.
Chip-backed borrowing creates a new marginal buyer for accelerated-computing capacity, extending demand beyond hyperscaler capex budgets and supporting NVDA shipment visibility over the next 1-3 quarters. The second-order risk is that GPUs are rapidly depreciating, have constrained resale markets, and can become unusable or less valuable following export-control changes or a new architecture cycle; lenders will eventually demand higher haircuts, covenants, and pricing. If financing spreads widen, leveraged GPU-cloud operators—not NVDA initially—absorb the stress through lower utilization, curtailed expansion, and potential equipment liquidations.
Consensus is likely too constructive on treating financed GPU purchases as equivalent to end-user demand. This mechanism can pull orders forward and obscure whether utilization and inference revenue justify the installed base. The key falsifier for the bullish semiconductor read-through is not another private funding round, but disclosed GPU-cloud utilization, renewal pricing, and any evidence that secondary-market prices for prior-generation accelerators are falling faster than depreciation assumptions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.60
Ticker Sentiment
Key Decisions for Investors
- Maintain a tactical long NVDA versus a short basket of leveraged GPU-cloud/private-credit proxies where liquid exposure is available; use a 1-3 month horizon around supply-chain commentary and earnings. The long works if financed capacity converts into deliveries, while the short leg hedges a utilization-driven capex reversal.
- Do not add to META solely on AI-M&A optionality. Treat any China-linked acquisition strategy as multiple-risk rather than synergy upside until a structure can demonstrate regulatory insulation; reassess after the next earnings call for commentary on AI talent, model partnerships, or cross-border investment constraints.
- Set a risk alert for NVDA: reduce incremental exposure if management, major cloud customers, or channel data indicate demand is increasingly financed by smaller operators while utilization or pricing weakens. A meaningful decline in secondary GPU values or tighter asset-finance terms would signal order pull-forward.
- Monitor private-credit spreads and equipment-finance underwriting over the next 3-6 months. If lenders begin requiring materially larger equity cushions or shorter amortization for GPU collateral, position for a widening gap between NVDA near-term revenue resilience and weaker economics for downstream compute lessors.
More News
- Labor crisis in U.S. chip manufacturing leaves Samsung, TSMC desperate for talent
- Warsh says AI’s hyperscalers are part of why your borrowing costs are rising: ‘The competition for capital is real’
- Bond Market Sell-Off: Is It Really Safe to Invest Right Now?
- Nvidia, AMD, Intel stocks rise after Fed hike: why obvious bearish case is failing
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- NVIDIA and Google's new coalition wants to speed up AI data center power grid connections
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts
- How to Automate Equity Research Workflows: A Control-First Guide