
Midea and Electrolux Group Officially Begin New Chapter in North America as All Three Joint Ventures Go Live
Source: PR Newswire
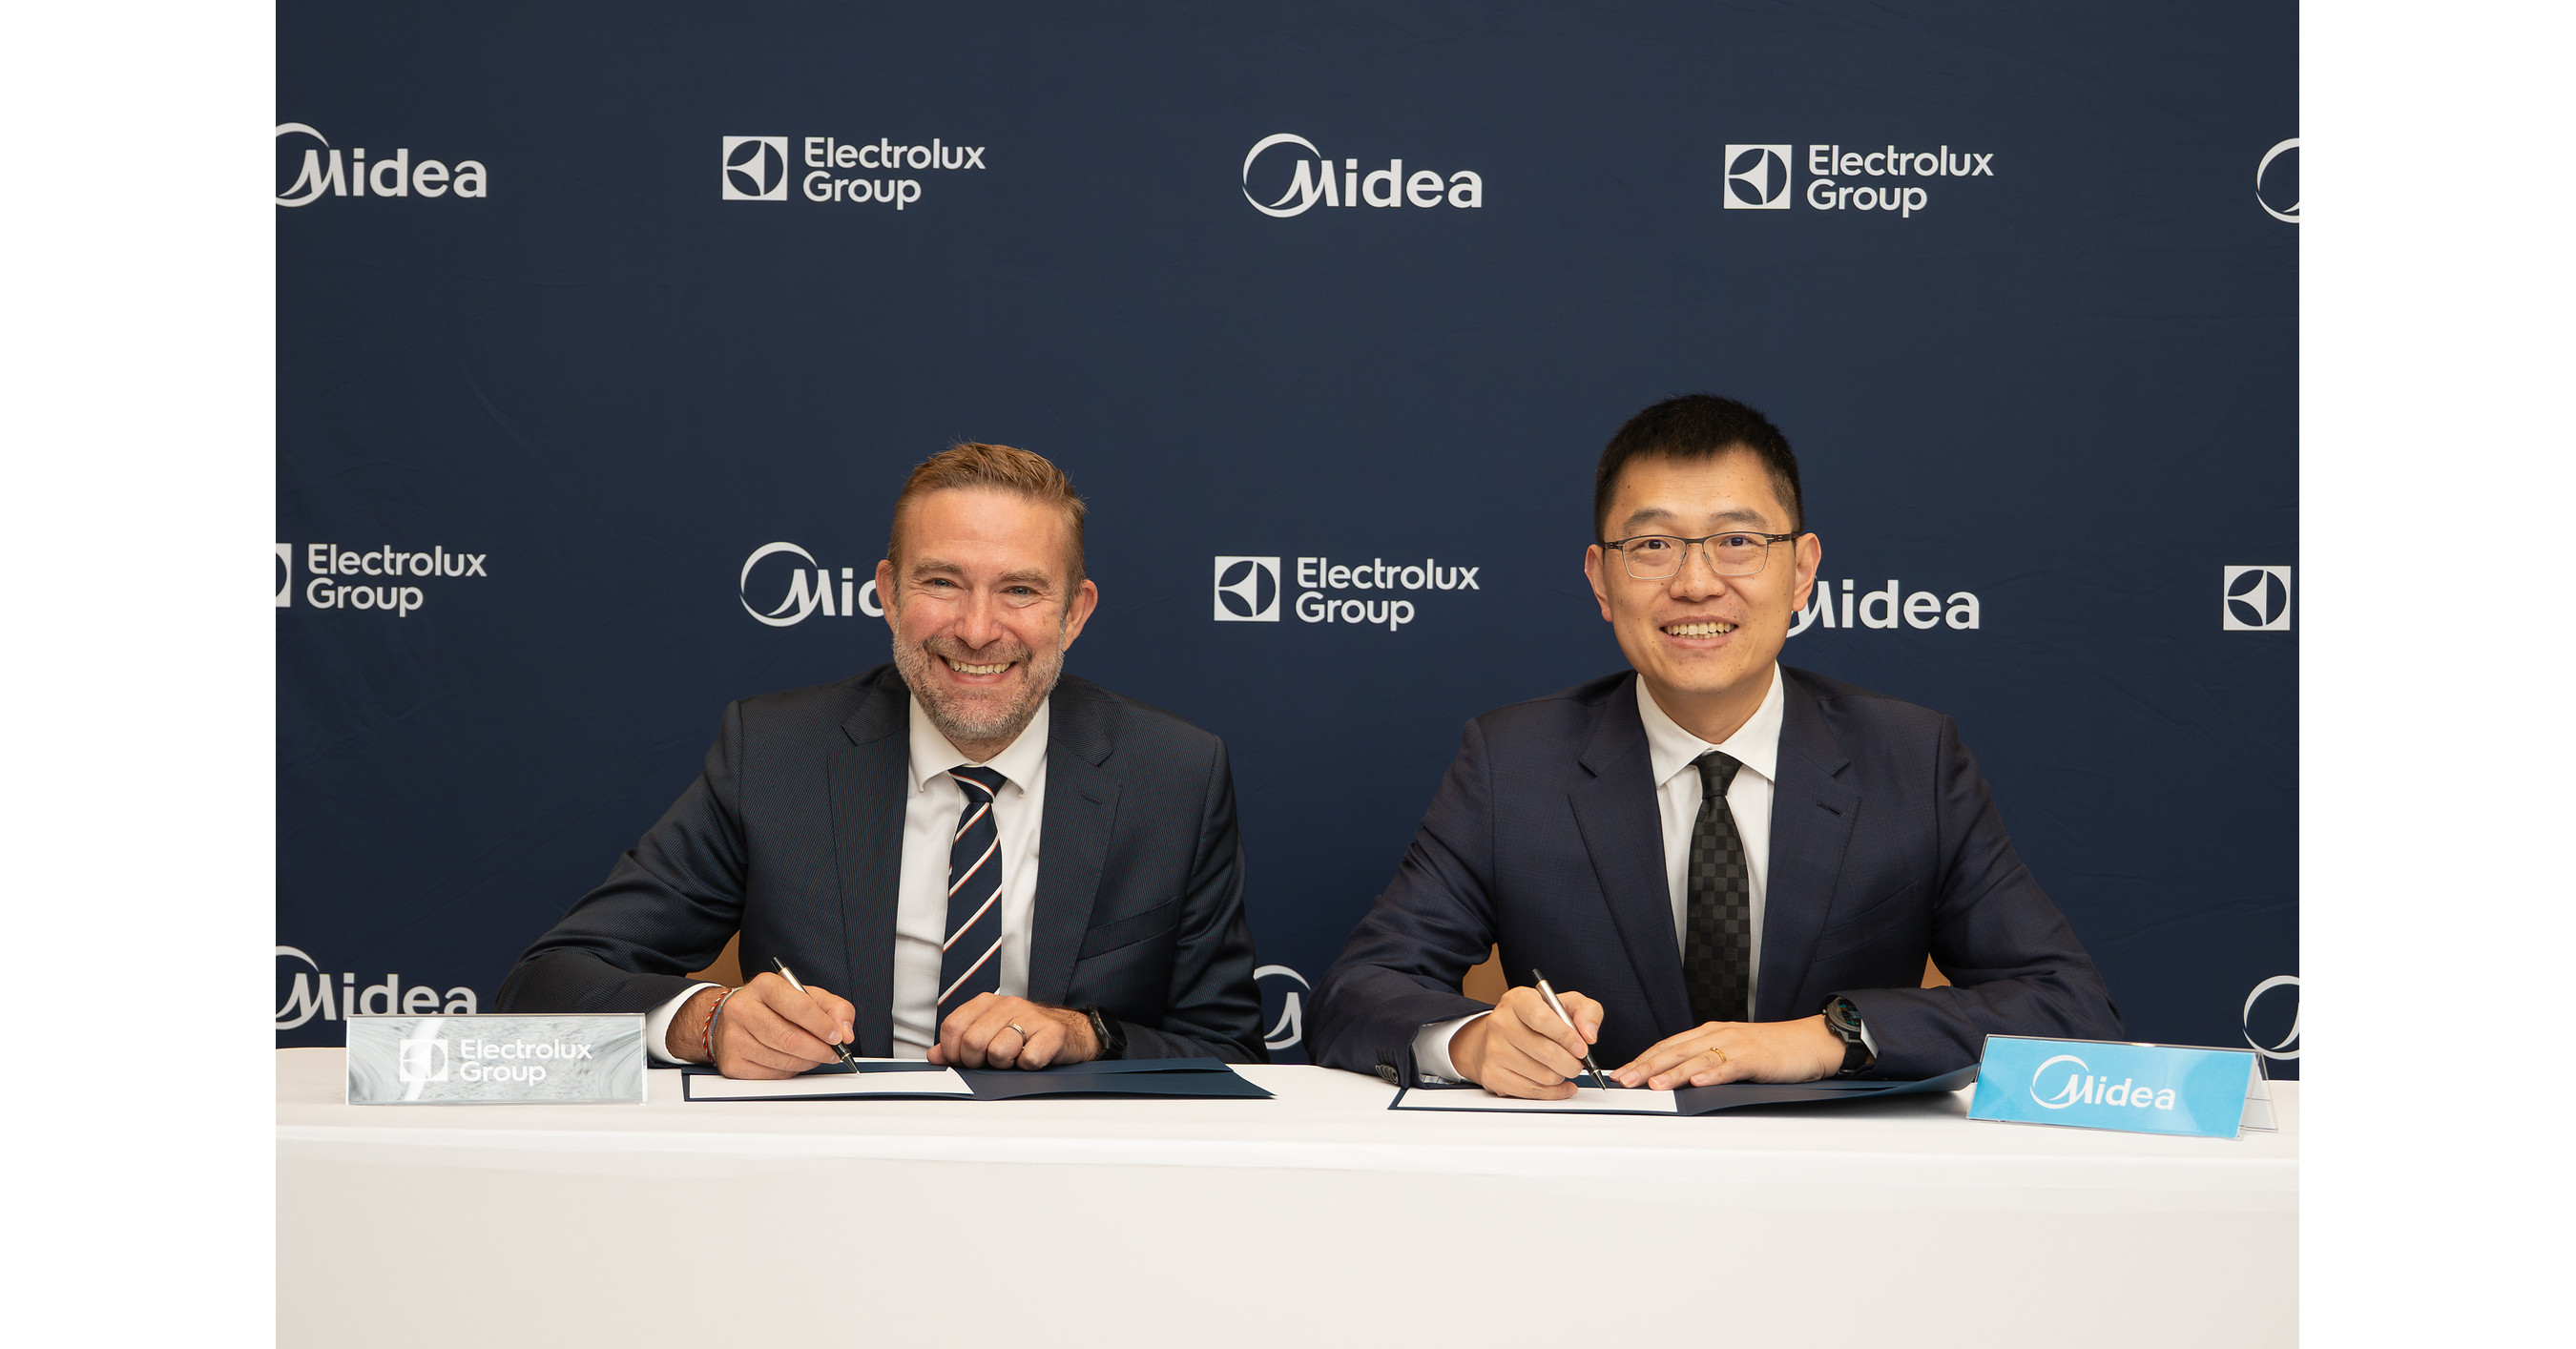
Midea Group and Electrolux Group have launched all three North American joint ventures announced in April 2026, combining manufacturing, product development, supply-chain and commercial operations. The partners plan to roughly double annual North American production capacity for food-preservation and fabric-care appliances while expanding into new product categories. Management expects the localized platform to improve product competitiveness, operating efficiency and Electrolux's profitable-growth trajectory.
Analysis
The economic value of the arrangement will depend less on incremental unit capacity than on whether Electrolux can close its North American cost-to-serve gap without surrendering brand pricing. A more integrated sourcing and manufacturing footprint could improve freight, working-capital and warranty economics for Electrolux (ELUX-B.ST/ELUXY), but it also gives Midea (000333.SZ) a lower-risk route into premium U.S. distribution. The likely near-term market effect is limited because ownership, profit-sharing, committed capex and volume allocations remain undisclosed.
The more consequential second-order effect is intensified mid-market appliance competition. Whirlpool (WHR), Haier Smart Home/GE Appliances (600690.SS), LG Electronics (066570.KS) and Samsung face a competitor with both local route-to-market access and potentially lower Asian component procurement costs. Retailers could use the expanded supplier base to demand promotions and private-label economics, creating a risk that industry volume growth converts into lower gross margins rather than higher earnings.
Over the next 1-3 months, the investable catalyst is disclosure of JV consolidation treatment, capital contributions, factory plans and retailer sell-in commitments rather than the launch itself. Over 6-18 months, evidence of lower inventory days, improved North American EBIT margin and stable realized pricing would support an Electrolux rerating; aggressive promotional activity or rising channel inventory would instead validate the bearish industry-margin case. The contrarian view is that capacity expansion may be demand-led localization rather than excess supply, but that requires household replacement demand and housing turnover to improve materially.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No immediate directional trade: treat this as a disclosure watch item until Electrolux reports JV ownership, expected capex, accounting treatment and a quantified North American margin bridge.
- Conditional 6-12 month pair trade: long ELUX-B.ST (or ELUXY where liquidity permits) / short WHR only after Electrolux demonstrates two consecutive quarters of North American margin improvement without increased promotional spending. Thesis is cost-to-serve improvement versus greater pricing pressure at Whirlpool; exit if Electrolux guidance does not show margin expansion or if retailer inventories rise.
- For existing WHR exposure, reduce overweight positioning ahead of the next earnings cycle if channel checks show expanded Frigidaire/Midea shelf space or above-normal promotions. The key falsifier is stable realized pricing and resilient gross margin despite new capacity coming online.
- Monitor 000333.SZ for evidence that North American appliance revenue or overseas segment margin accelerates faster than consolidated expectations over the next 2-4 quarters; absent segment disclosure, avoid attributing material earnings upside to the partnership.
More News
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- Paramount promised 30 movies a year to win Warner Bros. Losing Miramax if it fails may not scare it
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Automating Financial Model Updates: A Source-Controlled Workflow
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts