
Technip Energies: Why I Am Re-Initiating A Long Position
Source: seekingalpha.com
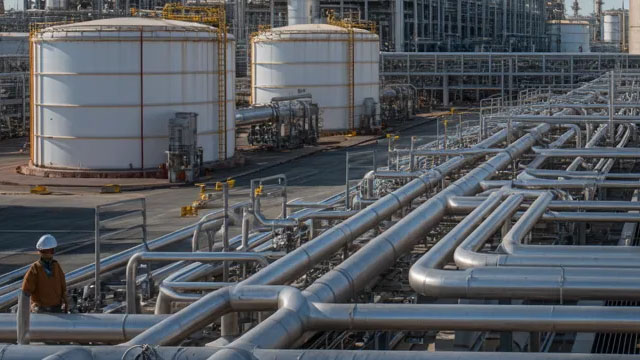
Middle East disruptions deferred revenue and halved Technip Energies’ H1 net profit, although the company remains profitable and free-cash-flow positive. Its record €25B backlog, low-capex model and transparent guidance support a longer-term positive view; the article describes shares below €30 as an attractive entry point via put options.
Analysis
The key distinction is whether Middle East disruption is shifting revenue in time or degrading project economics. Deferral alone need not impair the backlog, but longer schedules can delay cash conversion and increase execution exposure; a large backlog is not a near-term earnings floor. The bullish case therefore depends on backlog conversion and free-cash-flow resilience, not backlog size by itself.
Over the next 1–3 months, watch project-level timing updates, cash flow and any guidance changes: evidence of slippage spreading beyond affected work or weaker cash conversion would challenge the “temporary deferral” thesis. Over 6–18 months, persistent disruption could also alter customer investment priorities and tender timing. Work redirected to other EPC contractors is a possible second-order beneficiary, but there is not enough project detail here to identify a direct winner; compare Technip Energies’ exposure with competitors such as Saipem, Fluor and McDermott rather than assuming they are insulated.
Contrarian risk: the correction may be pricing execution and cash-conversion uncertainty, not merely geopolitical noise. Conversely, if schedules recover without deterioration in cash generation, the market may be discounting a timing issue too heavily. No independent evidence is provided here to validate the scale or duration of the deferrals.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Treat a short put at or below €30 as a conditional entry strategy, not a standalone bullish signal. Consider it only at a strike where assignment would be acceptable and the premium justifies the downside; verify spot price, expiry, implied volatility and net breakeven first. A short put retains substantial downside if shares fall sharply.
- Before adding exposure, check the next reporting update for project-level deferrals, backlog conversion, operating cash flow and any guidance revision. A deterioration in cash conversion or evidence that delays are broadening would falsify the benign timing thesis.
- Avoid extrapolating the record backlog into near-term earnings protection. Track whether customer schedules resume and whether backlog quality and execution economics remain intact; duration without conversion is not equivalent to earnings visibility.
- No direct peer pair is warranted on the supplied evidence. Monitor relative tender wins and project exposure at Saipem, Fluor and McDermott for signs that delayed work is being redistributed rather than postponed across the sector.
More News
- Samsung, SK Hynix shares drop as Q3 earnings loom
- CH Robinson to Buy RXO for $5.8B in Bet on AI Model
- BPCE acquires 7% stake in Spain’s Banco Sabadell
- Wells Fargo gets a bold upgrade ahead of earnings. Why the stock can play catch-up
- SpaceX stock climbs to highest since June, returning Musk to trillionaire status
- Nike’s China troubles: What are the implications for other sportswear brands?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction
- What Is an AI Investment Research Platform?