
Boeing was at risk of losing all fighter-jet production altogether. Now the stock is up on a new Navy contract.
Source: MarketWatch
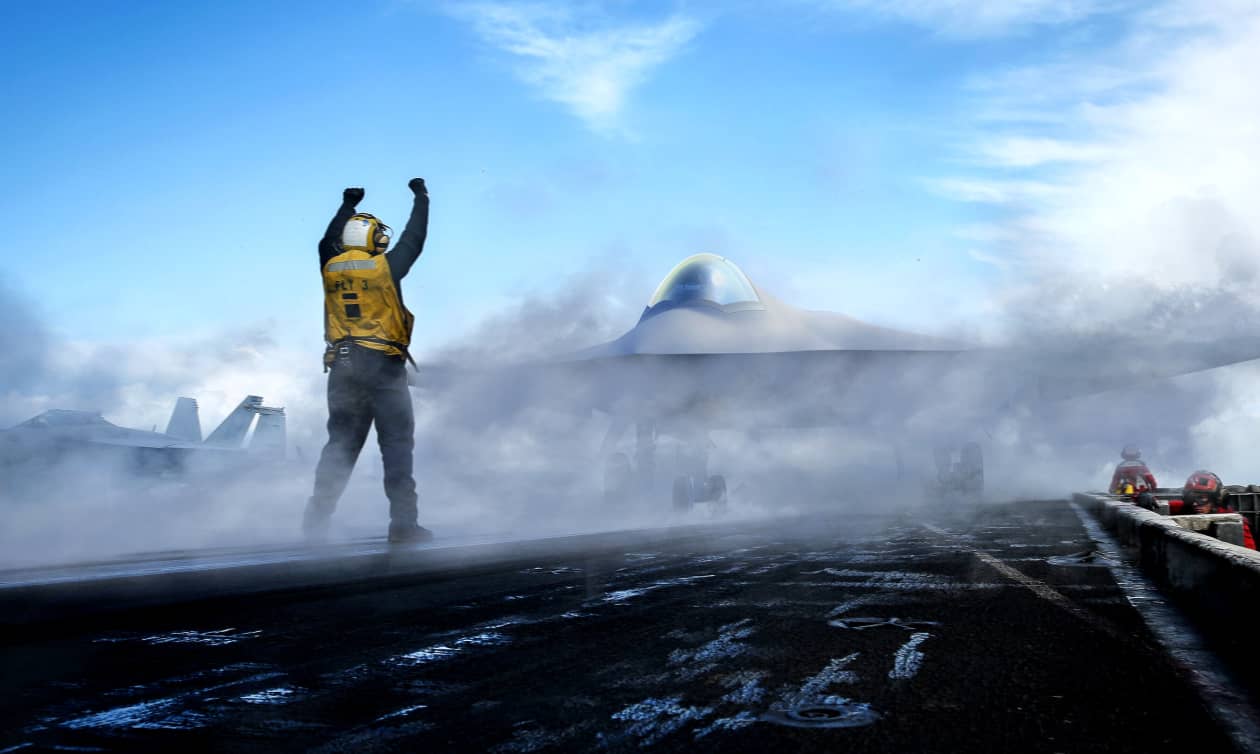
Boeing shares rose nearly 2% in premarket trading after the U.S. Navy selected the company to manufacture its next-generation fighter jet, preserving a critical military-aircraft production franchise. The contract is a meaningful positive for Boeing's defense business after concerns it could lose fighter-jet production entirely, though BA shares remain down about 14% year to date.
Analysis
The contract matters less for near-term earnings than for preserving Boeing Defense’s high-end tactical-aircraft design and production base. A sixth-generation program creates multi-decade engineering utilization and supplier commitments, reducing the probability that fixed costs from legacy fighter lines become stranded; that supports Defense segment margin durability in the 2028-2035 window. The initial market move is likely modest because development revenue is typically lower-margin and cash-consuming before low-rate initial production, while the contract’s disclosed ceiling, funding profile, and cost-plus versus fixed-price terms will determine actual value.
The second-order beneficiary set includes GE Aerospace (GE) and RTX, assuming they retain meaningful propulsion, avionics, radar, and mission-systems content; however, Boeing’s win raises a strategic threat to Lockheed Martin (LMT), whose tactical-air franchise had faced limited prime-contractor competition. LMT’s near-term financial exposure is limited by backlog, but a credible alternative prime can pressure long-cycle upgrade economics and future international campaign assumptions over 6-18 months. Northrop Grumman (NOC) may remain a content beneficiary rather than a clear loser if classified sensors, networking, or subsystems are dual-sourced.
Consensus may overread the award as a rapid BA earnings repair. The relevant 1-3 month catalyst is contract detail—especially prototyping milestones, IP ownership, and the Navy’s annual appropriations—not the headline. The thesis is falsified if the program is structured with uncapped development risk, faces a congressional funding delay, or Boeing’s commercial-aircraft cash burn and certification costs worsen enough to overwhelm the Defense de-risking value.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Do not chase BA on the initial move; establish a 3-6 month tactical long only if contract terms show funded milestones and limited fixed-price development exposure. Target a 8-12% re-rating from reduced defense-franchise extinction risk, with a 5-7% stop if commercial cash-flow guidance deteriorates or appropriation support weakens.
- Express the competitive implication via a 6-12 month pair: long BA / short LMT in equal beta-adjusted dollars after validating Boeing’s program role and LMT’s exposure to adjacent tactical-air upgrades. The expected return driver is relative multiple compression at LMT rather than near-term revenue loss; exit if LMT secures offsetting platform or modernization awards.
- Add GE and RTX to an event-driven watchlist rather than initiate immediately. Buy only after supplier awards identify propulsion and mission-system content; absent those disclosures, the revenue attribution is speculative and the headline provides insufficient edge.
- Monitor FY appropriations and any program protest/review over the next 90 days. A funding deferral or material cost-overrun disclosure would invalidate the BA catalyst and favors taking profits quickly on any defense-led rally.
More News
- Boeing wins U.S. Navy's next-generation fighter contract, Pentagon says
- Boeing Adds Navy’s Sixth-Generation Fighter to Its Roster
- Why is Boeing stock rallying today?
- Airbus gets a new freighter – and its giant door – into the air for the first time
- Alaska Airlines unveils massive premium cabin overhaul in high-end travel race
- U.S. Navy Selects Boeing for F/A-XX Program