
Xinhua Silk Road: Finanzforum in Beijing stellt Offenheit, Zusammenarbeit und Inklusivität in den Mittelpunkt
Source: PR Newswire
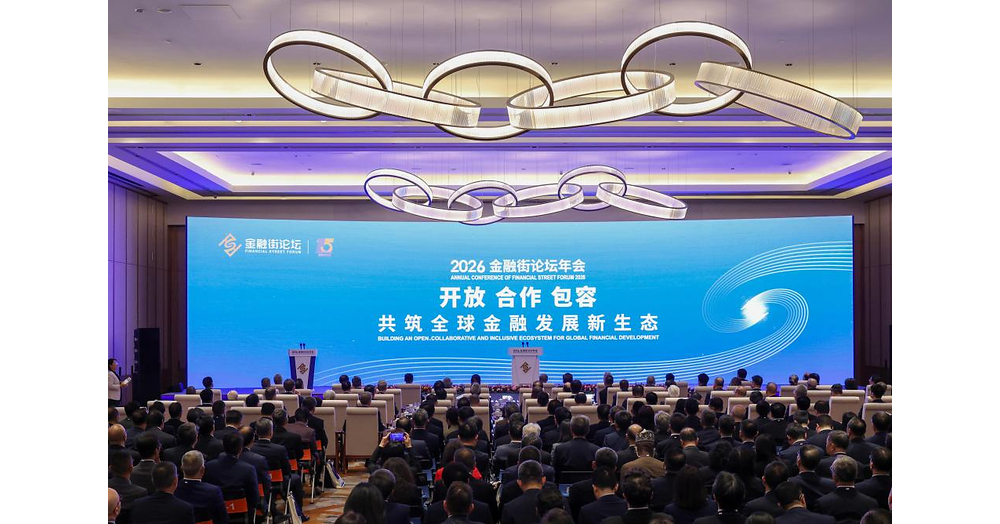
At the Financial Street Forum 2026 in Beijing, PBOC Governor Pan Gongsheng said the central bank would continue improving its monetary-policy framework, expanding its toolkit, strengthening market-based interest-rate mechanisms, and advancing renminbi internationalization. Chinese financial regulators also outlined plans to deepen financial-sector opening, develop capital-market functions, and introduce measures to support companies’ international cooperation; the article reports policy intentions but no specific new measures or market reaction.
Analysis
The signal is policy direction, not an investable policy change: the forum supplied no timetable, rule text, or measurable market-access commitment. Near term, that limits the case for repricing China financials or the renminbi on the announcement alone. The second-order tension is more important: deeper market-based rates and broader cross-border use of RMB require credible price discovery and hedging, while China’s authorities retain incentives to manage capital flows and market volatility. That tension can cap any valuation benefit from “opening.” Over 1–3 months, watch for concrete SAFE/CSRC access measures, changes to cross-border settlement or hedging rules, and PBOC implementation details. If implemented, foreign-facing brokers, exchanges, and custody/settlement providers could gain activity; banks could face mixed effects, as better rate transmission may support liquidity while repricing pressure can weigh on lending economics. Over 6–18 months, sustained progress could gradually reduce the market-access discount, but only if foreign participation and repatriation are demonstrably easier. The contrarian point: official language about openness is not itself evidence of a durable capital-inflow cycle. Reversal risk includes renewed capital controls, weak confidence, or policy actions that prioritize stability over market pricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No directional trade on this announcement alone. Treat it as a watch item; the missing evidence is enacted rules, effective dates, and data showing increased foreign participation or cross-border RMB use.
- For the next 1–3 months, monitor USD/CNH and offshore/onshore funding or basis indicators alongside SAFE and CSRC releases. Consider a tactical RMB-positive view only after specific measures improve access or hedging and are followed by sustained market evidence; exit the thesis if implementation is delayed or controls tighten.
- If rules materially expand foreign access, evaluate China-focused financial exposure through diversified instruments such as FXI rather than assuming a single domestic intermediary captures the benefit. Confirm that the change covers the relevant products and investors before positioning.
- Falsifiers: no meaningful implementing measures over the coming months; foreign participation fails to respond; or renewed restrictions, sharp currency-management actions, or weaker market confidence undermine the stated opening agenda.
More News
- Jio IPO Sees Overwhelming Demand on Day One Even as Nifty Struggles
- New Mexico took on Meta alone and won a $25 billion judgment over Facebook’s privacy violations
- Why the stock market’s fragile calm faces a major test starting Friday
- Meta ordered to pay $25 billion in case related to Cambridge Analytica scandal
- MSCI Pressed by Investors to Justify Drastic Indonesia Warning
- Judge orders Meta to pay $25bn in fines for Facebook privacy violations