
Sazerac Completes Acquisition of Au Vodka, Accelerating Global Growth and Expanding on Diverse Portfolio of Brands
Source: PR Newswire
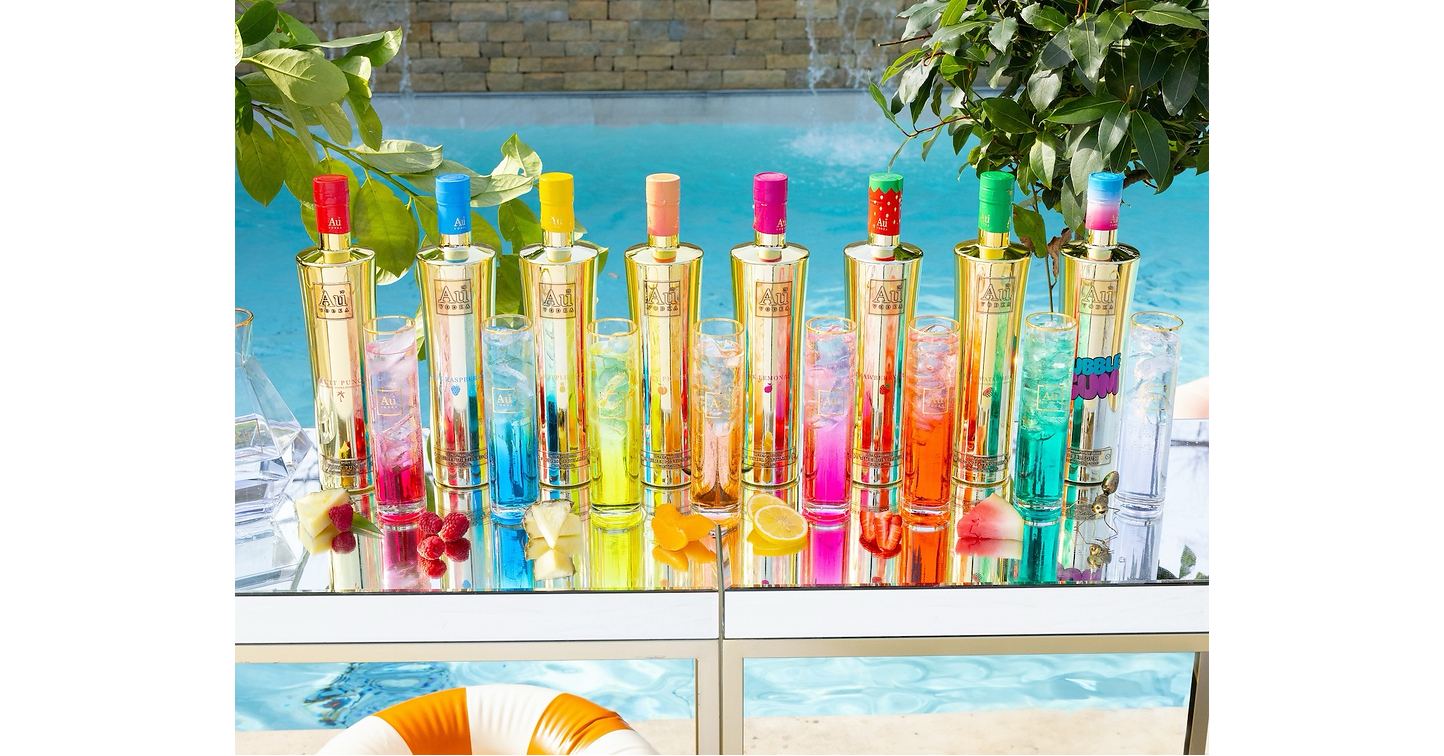
Sazerac completed its acquisition of UK-based Au Vodka, adding the fast-growing vodka and ready-to-drink brand to its global portfolio; transaction terms were not disclosed. The deal deepens Sazerac's UK presence and gives Au, founded in 2015 and employing more than 80 people, greater international distribution capacity. Sazerac expects to support continued global growth for Au alongside brands including Buffalo Trace, Fireball, BuzzBallz and SVEDKA.
Analysis
PJT is the only public-security read-through, but the completed mandate is economically immaterial relative to its advisory franchise and should not alter estimates. The more relevant signal is strategic: private-equity-backed, social-media-native alcohol brands remain viable exit inventory for scaled strategic buyers despite a difficult listed spirits tape. That supports a modest improvement in UK consumer-brand M&A confidence, not a broad rerating of publicly traded beverage stocks.
Sazerac can use its distribution and route-to-market infrastructure to lower Au's per-case logistics and trade-spend burden, while extending the brand into export markets. The offset is portfolio cannibalization: Au overlaps with Sazerac's SVEDKA and RTD ambitions, so the acquisition likely reflects a need for younger-consumer relevance rather than a purely incremental category opportunity. For Diageo (DEO), Pernod Ricard (RI) and Rémy Cointreau (RCO), the second-order risk is that independent flavored-vodka/RTD challengers can now receive global distribution without needing to build it organically, increasing shelf-space and promotional competition in the UK over the next 12-24 months.
No transaction value, Au revenue, profitability, or retention terms are disclosed; consequently, claims of earnings accretion cannot be independently assessed. The near-term market impact is likely negligible. A constructive sector read-through would require evidence that this is followed by additional strategic bids for premium or digitally native UK brands, while a reversal would come from UK off-trade data showing RTD volumes remain promotional rather than repeat-purchase driven, or from broad alcohol downtrading that forces higher trade spend.
Contrarian view: the deal may be more defensive than bullish. Acquirers frequently overpay for culturally salient challenger brands precisely when their organic growth is slowing and distribution saturation is approaching; scaling internationally can dilute scarcity and raise marketing intensity. Listed large-cap spirits companies should not be bought on this news alone, since their valuation debate remains governed by volume recovery, pricing elasticity, and inventory normalization rather than isolated private-brand M&A.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No directional PJT trade: treat the mandate as a qualitative indicator of consumer M&A activity, not an earnings catalyst. Reassess only if PJT reports a sustained increase in consumer advisory backlog or closes multiple comparable strategic transactions over the next 1-2 quarters.
- Maintain a 3-6 month watchlist for UK-exposed spirits/RTD pressure: DEO and RI are the cleanest listed proxies. Consider reducing longs if UK Nielsen/IRI data show Au gaining distribution alongside incremental promotional spend, as shelf-space losses would be more relevant than category growth.
- Do not initiate a broad long in DEO, RI, or RCO on strategic-M&A sympathy. A more actionable bullish setup requires sequential improvement in organic volume and stable gross margin guidance; absent that, challenger-brand acquisitions are evidence of competitive intensity rather than sector pricing power.
- Monitor private-brand sale processes and PE exits in beverage through year-end. A second strategic acquisition at a disclosed premium would strengthen the case for a selective long basket of premium consumer asset managers/advisers, including PJT, but this single undisclosed deal does not clear that threshold.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough