
Niutech finalise la restructuration de son groupe afin de faire progresser le recyclage chimique des pneus et des plastiques
Source: PR Newswire
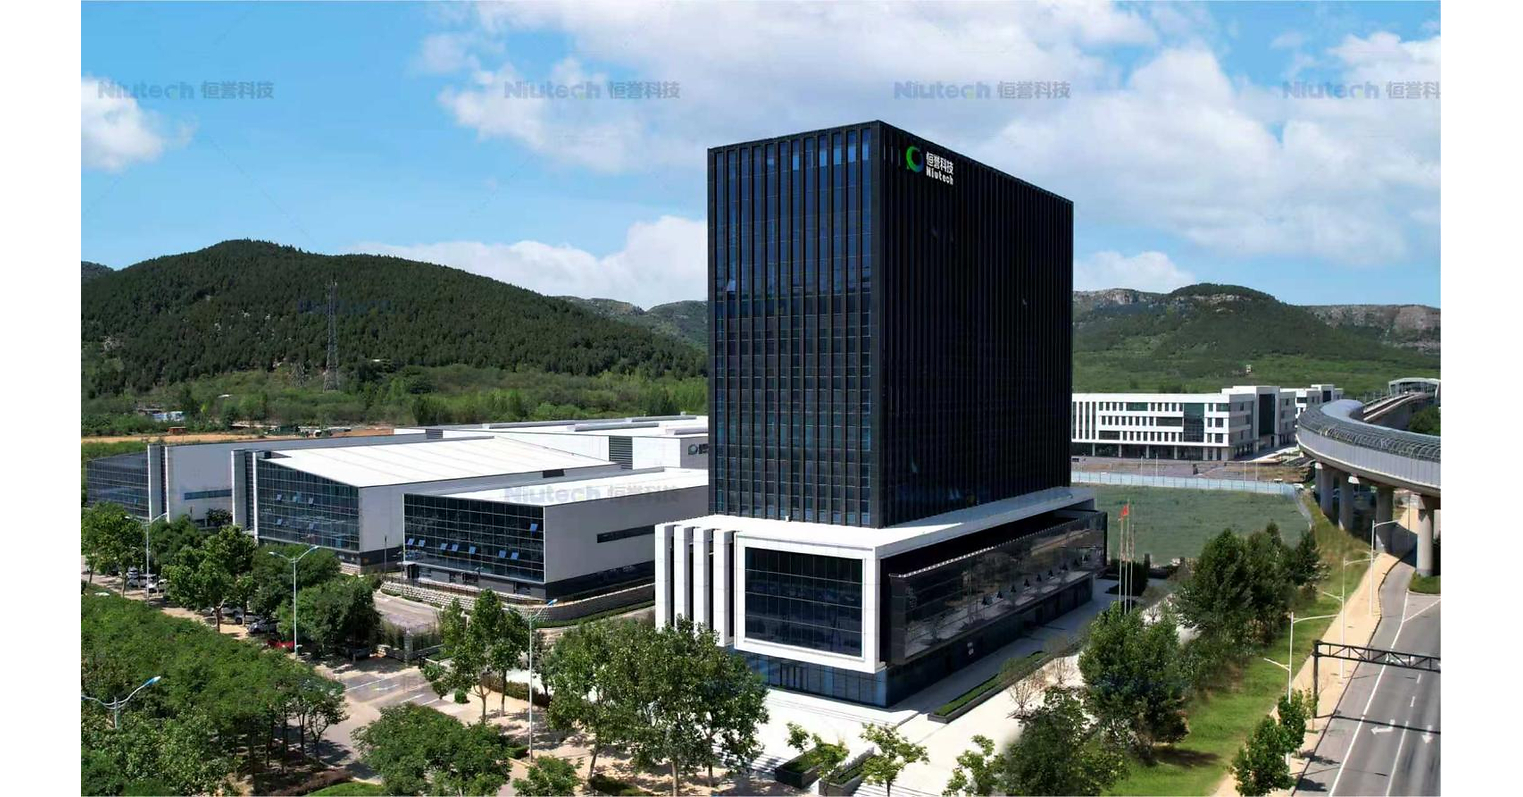
Niutech completed a group restructuring on August 26, 2026, broadening its corporate scope to include resource-recycling technology, equipment manufacturing and new-materials R&D. The company says its next-generation pyrolysis line processes more than 100 tonnes per unit per day; a Phase II project at majority-owned Hesheng is expected to raise capacity to 160,000 tonnes annually in 2026. Niutech also cites a £198 million? No: a UK customer order valued at RMB 198 million, while it develops processes aimed at sustainable aviation fuel production.
Analysis
The investment case is conversion economics, not the enlarged corporate scope: restructuring language does not itself demonstrate new revenue, while the subsidiary’s capacity expansion and the UK order are separate evidence points and should not be conflated with consolidated earnings. The key swing factors are sustained plant uptime, feedstock cost (including any gate fees), saleable yields, product specifications, and contracted offtake prices. If these work, pyrolysis can compete for waste streams that mechanical recycling cannot handle and displace some virgin petrochemical feedstock; if not, regulation may generate project announcements without attractive returns. The potential losers are virgin polymer and carbon-black suppliers at the margin, but only once buyers qualify recycled outputs at scale. Mechanical recyclers may also lose low-value feedstock, though better-sorted material could remain more valuable in their processes.
Near term, the press-release claims are not independently verified: the order’s delivery schedule, cancellation terms, payment milestones, and revenue recognition are unknown. Regulatory recycled-content rules support demand over 6–18 months, but implementation, approved accounting methods, and buyer qualification can delay conversion. The SAF angle is exploratory; blending-process R&D is not evidence of certified aviation fuel production or material economics. A sharp share-price reaction to this release alone would be vulnerable to reversal if order conversion or project returns are not disclosed.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- Do not initiate a directional position solely on the announcement. First verify Niutech’s current valuation, trading liquidity, order backlog conversion, and whether the UK contract has binding delivery and payment terms.
- Set a 1–3 month diligence trigger: seek reported project utilization, realized product prices, gross contribution after feedstock/logistics, and customer acceptance of pyrolysis oil and recovered carbon black. These determine whether capacity translates into earnings.
- Treat the 100,000-tonne subsidiary expansion as a project-level catalyst, not automatically consolidated growth; confirm ownership, commissioning cadence, financing, and the subsidiary’s contribution before updating group estimates.
- If the shares rally materially without new financial disclosure, consider a tactical fade rather than chasing; invalidate that view on evidence of contract execution, sustained operating performance, or binding long-term offtake. No price level can be specified without current market data.
More News
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Israel’s economy prospers despite years of war, but prices worry voters
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- SpaceX’s Wireless Threat Rises With Spectrum Deal
- Why is the Chinese stock market missing the AI rally
- OpenAI's revenue scare, Delta earnings, what investors think of a Starbucks-Chipotle deal and more in Morning Squawk