
Lucid shares rise on Bolt deal for 25,000 robotaxis in Europe
Source: proactiveinvestors.com
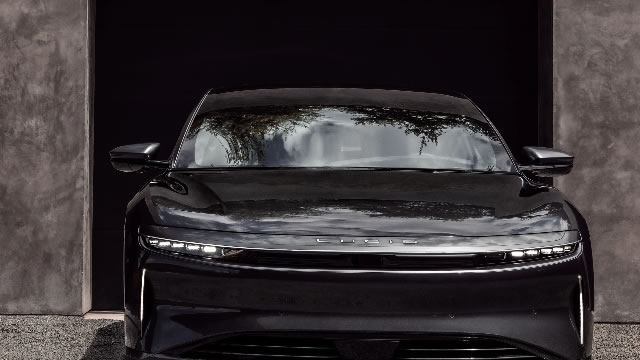
Lucid shares rose after the EV maker agreed with European ride-hailing platform Bolt to deploy at least 25,000 autonomous vehicles across major European cities. The planned fleet will use Lucid's upcoming midsize platform and Nvidia's Hyperion autonomous-driving architecture, targeting SAE Level 4 driverless operation under defined conditions. The deal provides a sizable prospective commercial use case for Lucid and expands Nvidia's automotive AI ecosystem.
Analysis
The equity implication for LCID hinges almost entirely on whether this is a financed, binding fleet purchase commitment rather than a framework agreement. A fleet order of this scale would require manufacturing capacity, working capital, service infrastructure and residual-value support far beyond Lucid's current consumer-sales model; without deposits, minimum purchase obligations and a credible financing partner, the headline should not be capitalized into revenue estimates. The first 1-3 month catalyst is disclosure of unit economics, delivery timing, and who carries vehicle ownership and autonomous-operations liability.
Even if volumes materialize, fleet economics are lower-margin than premium retail: Bolt will seek utilization-based pricing, uptime guarantees and rapid parts availability, potentially limiting gross-margin recovery. The more important 6-18 month upside is that predictable fleet demand could improve Lucid's plant absorption and supplier purchasing leverage, reducing fixed-cost deleverage; conversely, any delay in the midsize platform would turn a strategic validation into another execution overhang. European Level 4 authorization will be jurisdiction- and operating-domain-specific, leaving regulatory approval, insurance and remote-assistance costs as material risks to deployment timing.
NVDA's direct revenue contribution is likely immaterial against its automotive and data-center base, but a commercial fleet design win is strategically useful evidence that its automotive platform can participate beyond development programs. The consensus may overvalue the autonomous label: the scarce asset is not compute hardware but a validated driving stack, regulatory approvals and fleet operating capability. Mobileye (MBLY), Waymo/Alphabet (GOOGL), Tesla (TSLA) and European AV operators remain the relevant competitive benchmarks; a vehicle-platform announcement alone does not establish an operating moat.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Do not chase LCID on the initial move. Establish a 1-3 month watch trigger for a disclosed binding purchase schedule, customer deposits or third-party fleet financing; absent those items, treat the announcement as low-confidence pipeline rather than booked revenue.
- If LCID rallies materially without contract economics, consider a tactical long RIVN / short LCID pair over 1-3 months: RIVN has a more tangible production ramp and strategic funding support, while LCID remains more exposed to platform timing and cash-burn risk. Cover if LCID discloses meaningful non-refundable deposits, a funded fleet vehicle-finance structure, or raises delivery guidance.
- Maintain NVDA only as a strategic optionality beneficiary, not a trade catalyst. The relevant confirmation is incremental automotive design-win backlog or software/services monetization at quarterly results; without either, this deployment should not alter NVDA earnings expectations.
- For existing LCID longs, require evidence by the next two earnings cycles that fleet-related demand improves production utilization without further gross-margin deterioration. A lowered delivery outlook, increased capital requirement, or delay in the midsize-platform launch falsifies the bull case and warrants reducing exposure.
More News
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year
- What an Oscar-winning movie can teach us about investing through the AI slowdown debate
- Goldman’s top strategist just added hard numbers to his earnings-bubble warning
- Marvell pushes GlobalFoundries to light up wafer production
- Huawei's next-gen Ascend NPUs could become China's best option