
Japan's Cash-Strapped Monks Pushed to Invest as Inflation Worsens
Source: Bloomberg
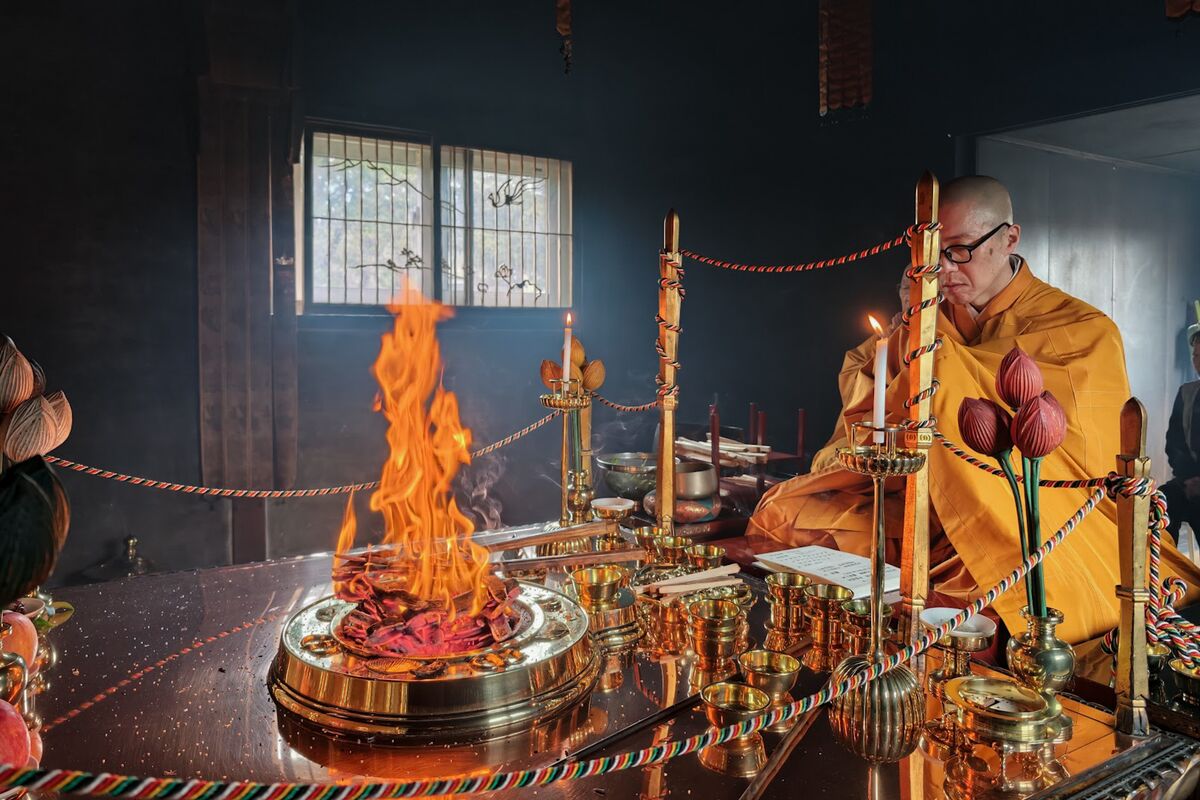
A cash-strapped Buddhist temple in Hokkaido generated annual returns of more than 10% over two years by investing donations in US Treasuries, Japanese REITs, and equities including BYD and Hyundai. The gains helped fund part of roughly ¥25 million ($162,000) in repairs and enabled an expansion of the renovation plan, illustrating how inflation and declining donations are pushing Japanese temples toward investment income.
Analysis
This is not a standalone temple-finance trade, but it is a small signal of Japan’s broader forced migration from cash deposits into market assets. If inflation persists while household and institutional cash earns below real funding needs, flows should favor domestic dividend equities and listed real estate over traditional deposits; likely beneficiaries include high-quality financials (TSE: 8306 MUFG, 8316 SMFG), asset managers (TSE: 8604 Nomura) and large J-REITs (TSE: 8951 Nippon Building Fund, 8952 Japan REIT Investment). The second-order effect is a gradual expansion of Japan’s retail/institutional risk appetite, supporting valuation rerating for income-producing assets rather than simply raising aggregate equity demand.
The key distinction is that this flow is yield-sensitive, not indiscriminate. A further BOJ normalization would improve banks’ net-interest income and make deposits more competitive, while pressuring long-duration J-REIT NAVs and refinancing costs. Over the next 1-3 months, BOJ communication and JGB yield moves matter more than anecdotal allocation behavior; over 6-18 months, durable positive real wage growth and continued governance-driven buybacks would determine whether domestic capital remains in equities.
Contrarian risk: consensus treats higher Japanese rates as uniformly bearish for risk assets. Modest curve steepening can be net positive for banks and insurers, and their dividend capacity may attract the same income-seeking capital that would otherwise enter REITs. The weak link is highly levered property exposure: if 10-year JGB yields rise materially without rent growth, J-REIT distribution yields must reset higher, creating NAV and equity-price downside despite incremental investor flows.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Prefer a 6-12 month long MUFG (TSE: 8306) / short broad J-REIT ETF (TSE: 1343) pair if the 10-year JGB yield sustains above 1.25%: banks benefit from normalization while property vehicles face cap-rate and refinancing pressure. Target 10-15% relative return; exit if BOJ signals renewed easing or long yields retreat below 0.90%.
- Maintain selective exposure to Japanese shareholder-return beneficiaries through EWJ or a basket led by TSE: 8306, 8316 and 8766 (Tokio Marine), rather than chasing lower-quality yield equities. Reassess at next BOJ meeting and earnings guidance; the thesis fails if NIM guidance and buyback commitments weaken despite higher rates.
- Do not add broad J-REIT exposure solely on prospective domestic flows. Upgrade the sector only if distribution growth exceeds financing-cost growth and implied cap rates widen enough to restore a meaningful premium versus 10-year JGBs; monitor quarterly debt maturities and rent-reversion data.
More News
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- Asian markets make nervous start ahead of Fed decision
- BOJ set to raise interest rates to 31-year high as inflation risks loom
- Iran war increasing inflation, straining US munitions: congressional report
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- Three Big Central Bank Decisions Loom: Evening Briefing Americas