
Smart Shooter Awarded JIATF-401 Single-Award IDIQ Contract for SMASH Counter-Drone Systems with a Ceiling of Up to $150 Million
Source: PR Newswire
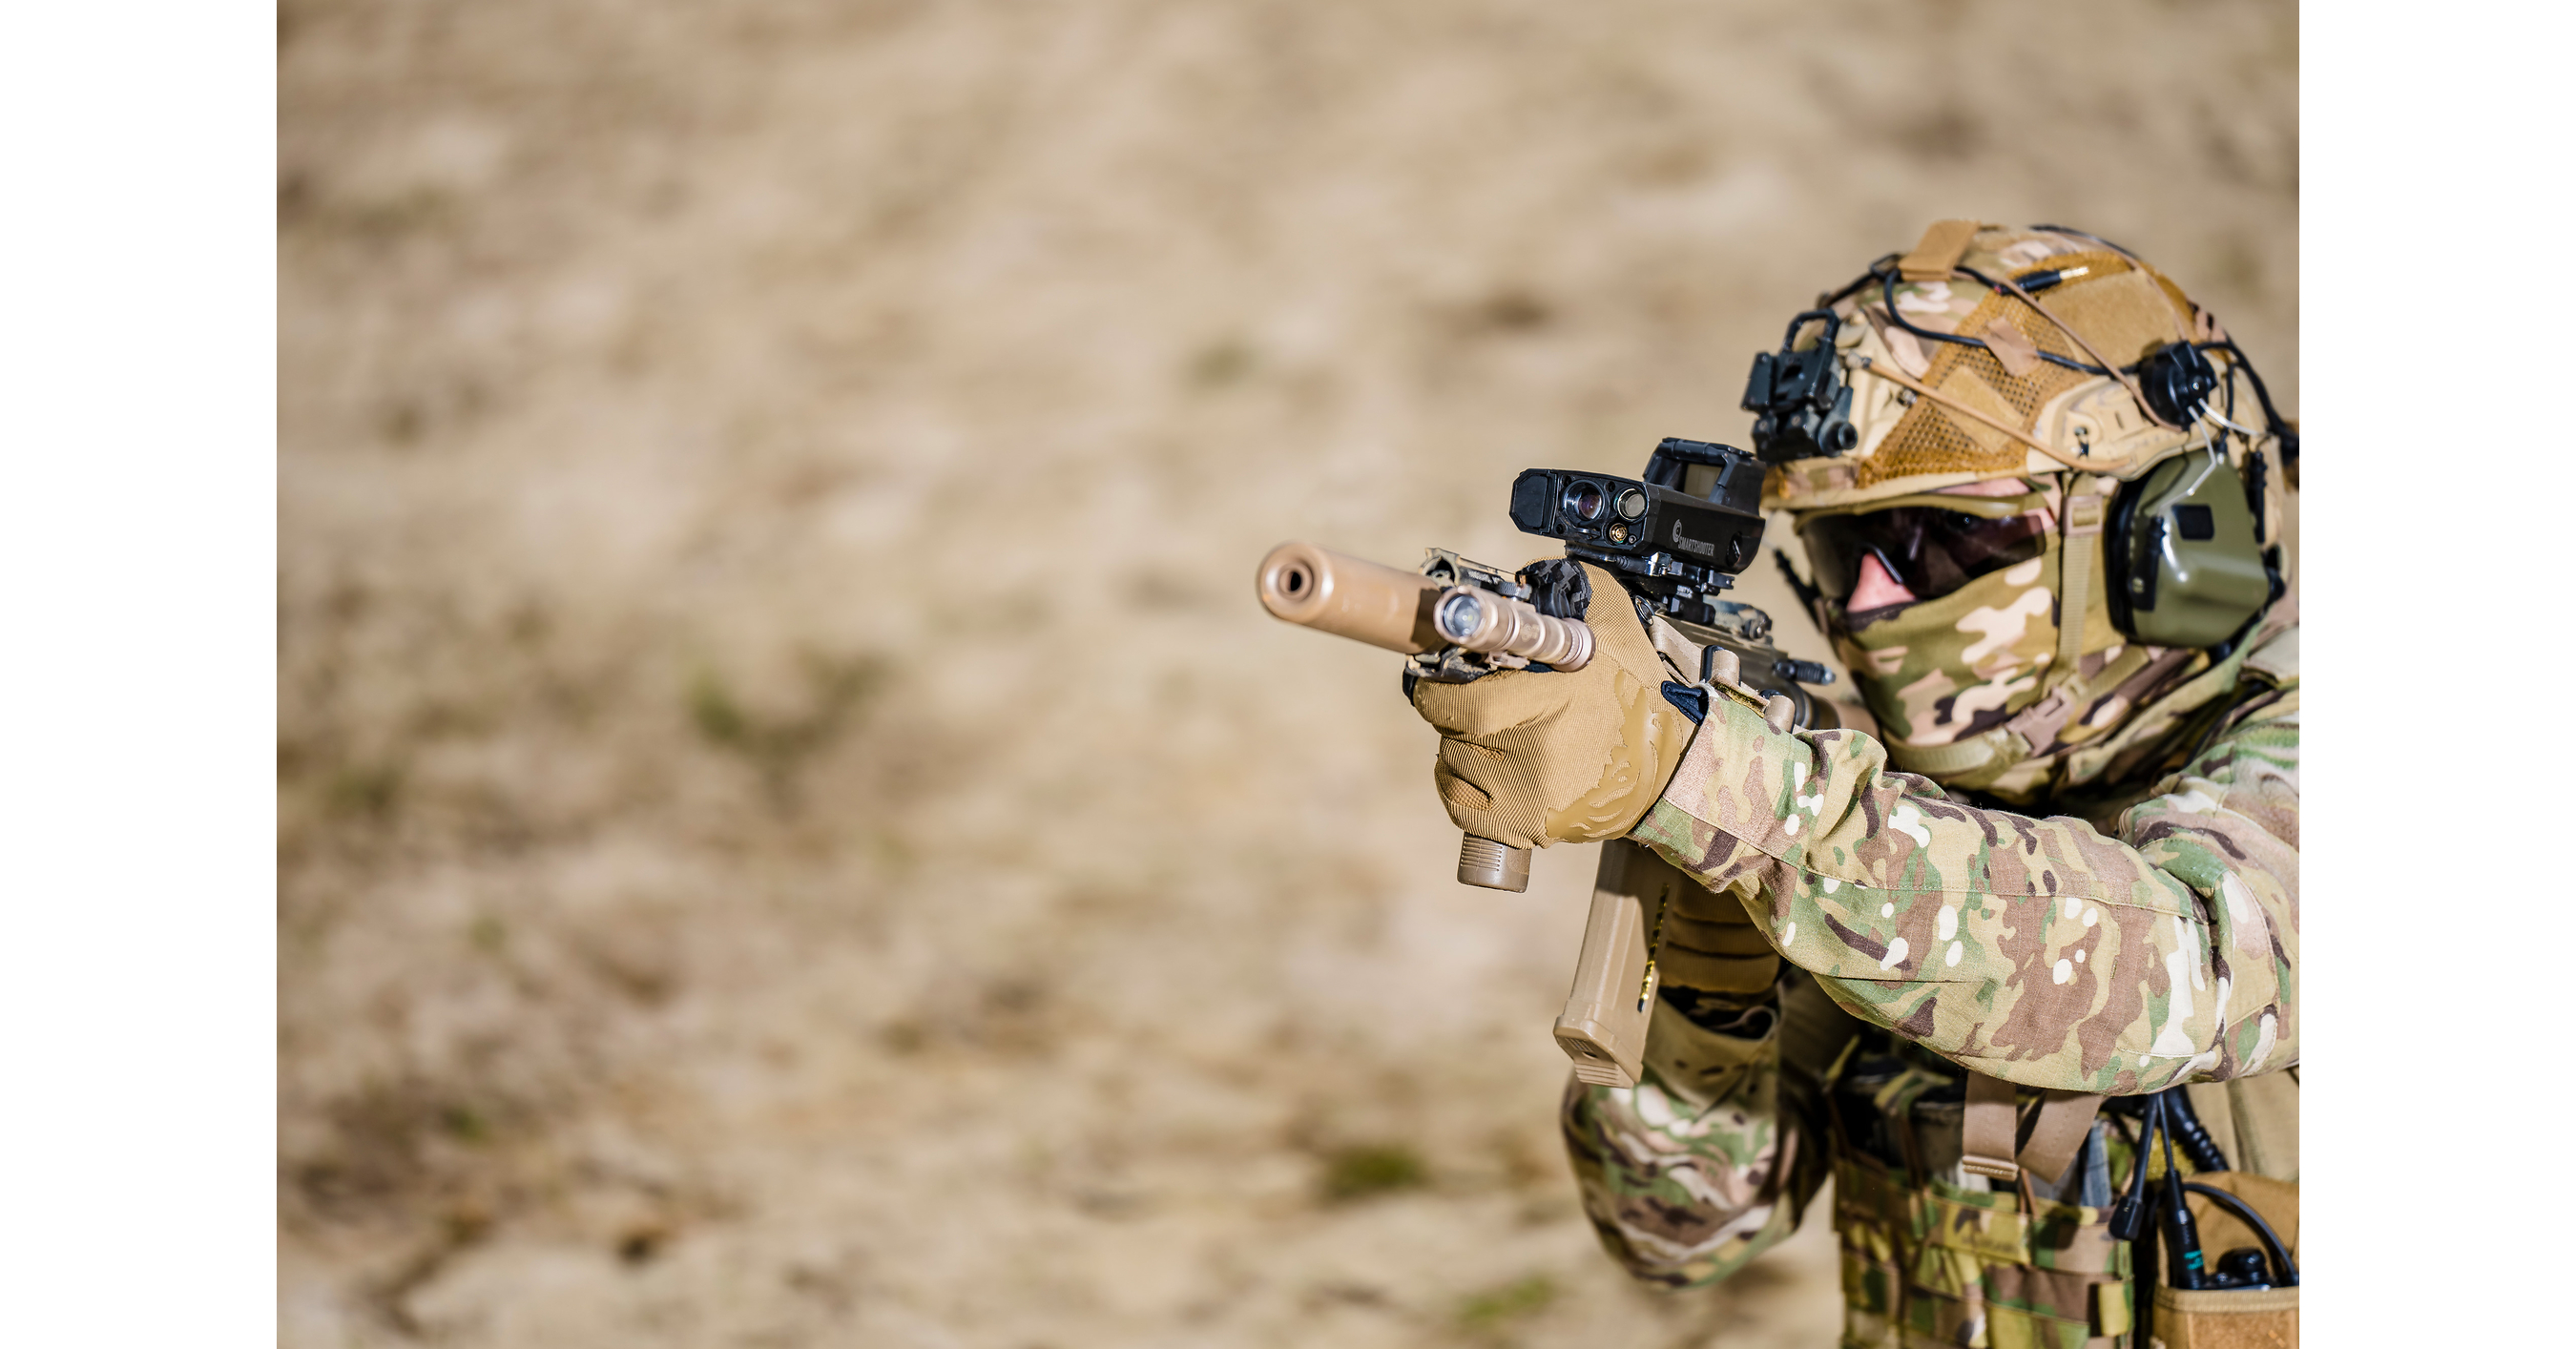
Smart Shooter secured a JIATF-401 counter-UAS contract framework that could generate future delivery orders of up to $150 million for its rifle-mounted SMASH fire-control systems. The agreement supports the U.S. military's Domestic Shield program and global force-protection missions, covering hardware, software updates, training, and support. The award expands Smart Shooter's U.S. defense-market presence following prior JIATF-401 and broader U.S. Army, Navy, Air Force, and Marine Corps awards, with thousands of its systems already deployed across U.S. services.
Analysis
The investable signal is less about the private vendor and more about procurement architecture: low-cost, soldier-operated kinetic defeat is becoming a required final layer beneath radar, EW, and interceptor systems. That favors integrated counter-UAS stacks at RTX, LHX, KTOS, and AVAV/BlueHalo, but creates a modest substitution risk for expensive interceptor-per-drone solutions where a rifle-based option is operationally sufficient. The larger recurring opportunity is likely training, software updates, sensor integration, and doctrine-driven replenishment rather than initial hardware revenue.
The stated ceiling should not be treated as funded backlog. Delivery-order cadence, unit pricing, and the share allocated to hardware versus support are the critical missing data; absent those, there is no basis to revise public-company estimates. Near term, this is principally a validation event for counter-UAS budget priority, with a 1-3 month catalyst if DoD supplemental appropriations, base-protection requirements, or allied procurement announcements broaden demand. Over 6-18 months, proliferating cheap drones should support higher defense-electronics multiples, but only for companies demonstrating fielded systems and production capacity rather than concept-stage autonomy.
Consensus may overvalue AI branding and undervalue engagement economics. Computer vision at the edge improves effectiveness, but operational adoption depends on false-positive rates, soldier training burden, ammunition use, and performance against swarms, obscurants, and electronic countermeasures. A shift toward coordinated swarm threats would favor layered systems from RTX, LHX, and AVAV over point-defense fire-control products; failure to demonstrate reliable integration with command-and-control networks would similarly cap the addressable market.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Key Decisions for Investors
- Do not assign revenue to the announced framework or chase a read-through in large primes; treat delivery-order disclosure, funded backlog, and unit-volume data as required confirmation before changing estimates.
- Build a 6-12 month basket overweight AVAV and KTOS versus ITA, sized modestly, for asymmetric exposure to counter-UAS modernization. Target 15-20% upside if funded counter-UAS programs translate into bookings; exit if FY2027 guidance fails to show backlog conversion or gross-margin dilution from rapid production ramps.
- Prefer RTX or LHX for lower-volatility exposure where the thesis is layered base defense rather than a single defeat mechanism. Reassess if U.S. defense appropriations delay, or if management commentary indicates counter-UAS demand is being met from existing budgets rather than incremental funding.
- Monitor AXON as a second-order domestic-infrastructure beneficiary through its Dedrone platform, but wait for evidence that defense and critical-infrastructure contracts become material to segment growth; its core valuation remains driven by public-safety software, making this only an upside optionality watch item.
More News
- UK Prime Minister Burnham says Iran 'played a part' in British air base incident
- South Korea’s exports hit record high on AI boom
- Asian stocks dip, bonds in focus after torrid September
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Greer urges G20 to back Trump tariff agenda, takes aim at China
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework