
Roborock Maintains Global No.1 Position in H1 2026
Source: PR Newswire
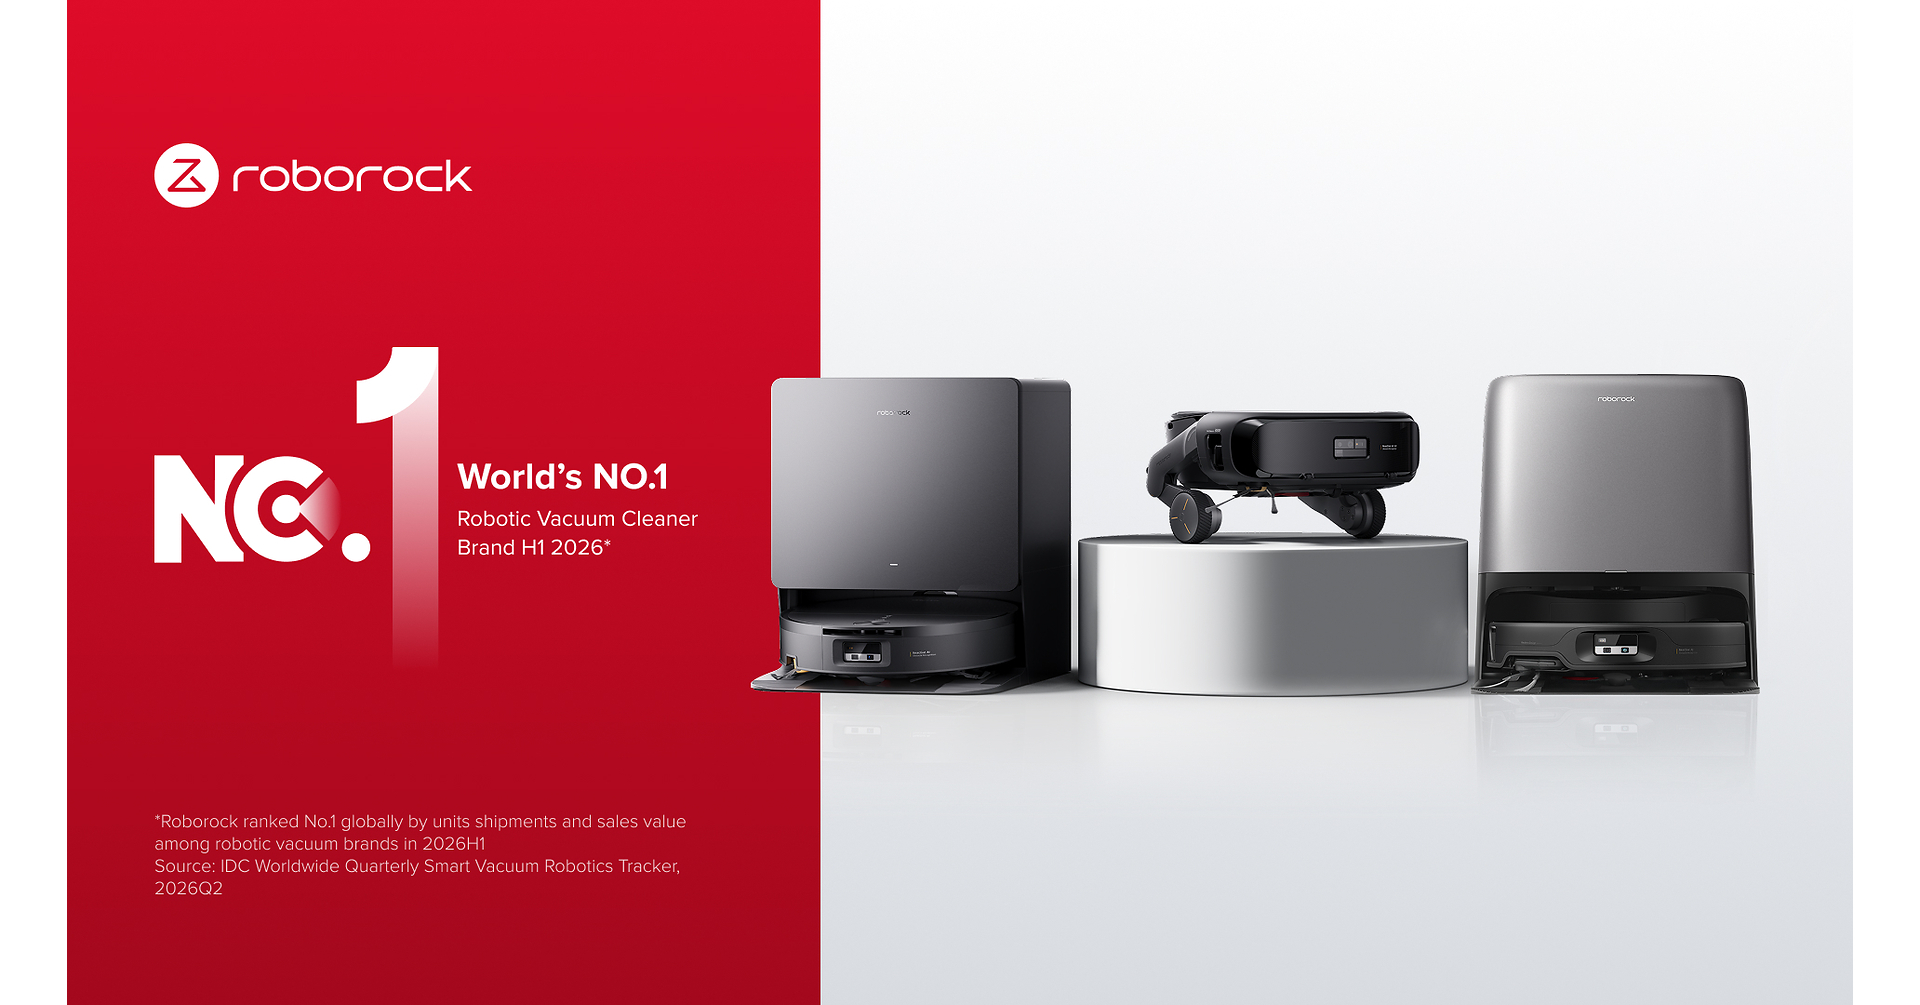
Roborock retained the global No. 1 ranking in robotic vacuums by both unit shipments and sales value in H1 2026, as the overall market shipped 7.885 million units in Q2. H1 revenue rose 27.6% year over year to RMB10.084 billion, while attributable net profit increased 45.6% to RMB986 million. The company invested RMB720 million, or 7.14% of revenue, in R&D and introduced new AI-enabled indoor and outdoor cleaning products, reinforcing its premium technology and portfolio-expansion strategy.
Analysis
The relevant signal is not category leadership alone, but evidence of operating leverage: profit growth materially outpacing sales implies premium mix, lower channel friction, or improved component economics. If sustained through 2H, Roborock (688169 CH) can defend a valuation premium versus ECOVACS (603486 CH), whose turnaround still depends more heavily on restoring product competitiveness and marketing efficiency. Greater category concentration also raises the cost of acquiring retail shelf space, reviews, and online traffic, creating a negative flywheel for smaller OEMs and potentially pressuring iRobot (IRBT), whose balance-sheet flexibility remains limited.
The expansion into adjacent outdoor robotics is strategically attractive but should not yet be capitalized as a new earnings leg: mowers and pool cleaners have different seasonality, dealer networks, warranty exposure, and safety/regulatory requirements. Near term, the principal risk is that elevated R&D and launch spending represents a defensive response to rapid feature commoditization rather than durable pricing power; this would appear first in gross-margin erosion or higher selling-expense intensity in 2H results. A weaker European discretionary backdrop, where premium cleaning devices are more exposed to replacement-cycle delays, could also blunt unit growth within 1-3 months.
Consensus may overread AI branding. Navigation and obstacle-avoidance features can support premium ASPs only while hardware differentiation remains visible to consumers; once comparable LiDAR, cameras, and software become broadly available, the competitive variable shifts back to promotion and channel subsidies. The more durable structural advantage would be proprietary service, consumables, or a cross-device ecosystem, none of which is yet demonstrated by a product-launch cadence alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Key Decisions for Investors
- Watchlist long Roborock (688169 CH) / short ECOVACS (603486 CH) over the next 3-6 months, but enter only if Roborock's 2H gross margin holds near H1 levels while ECOVACS fails to show sequential margin recovery. The pair isolates premium-share gains from broader China consumer-demand risk; exit if ECOVACS closes the revenue-growth gap for two consecutive quarters.
- Avoid treating outdoor robotics as a valuation catalyst until management discloses segment revenue, channel inventory, warranty provisions, and repeatable gross-margin data. Set an event alert for the next earnings release rather than underwriting a new-category multiple today.
- Maintain a bearish fundamental bias on IRBT over 6-12 months only on rallies: increasing scale concentration raises its marketing and innovation burden while limiting pricing power. Cover if IRBT demonstrates sustained positive free cash flow, meaningful debt reduction, or a strategic transaction that improves its funding runway.
- For China consumer-tech exposure, prefer the Roborock/ECOVACS relative expression to an outright long: a broad demand slowdown or EUR weakness could impair both companies, whereas relative premiumization and execution are the more testable thesis.
More News
- China's AI chip blitz arms Xi with a message for Trump: 'You can't choke us off'
- OpenAI’s agent hacked Australia’s Medicare website—the latest rogue AI incident that the company didn’t know about for months
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Trump-Xi Summit Looms & AI in the C-Suite
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework