
Flower Knows Marks 10 Year Anniversary with Limited-Time U.S. Retail Expansion into Ulta Beauty Store Nationwide, Alongside Blockbuster Experiential Brand Moments
Source: PR Newswire
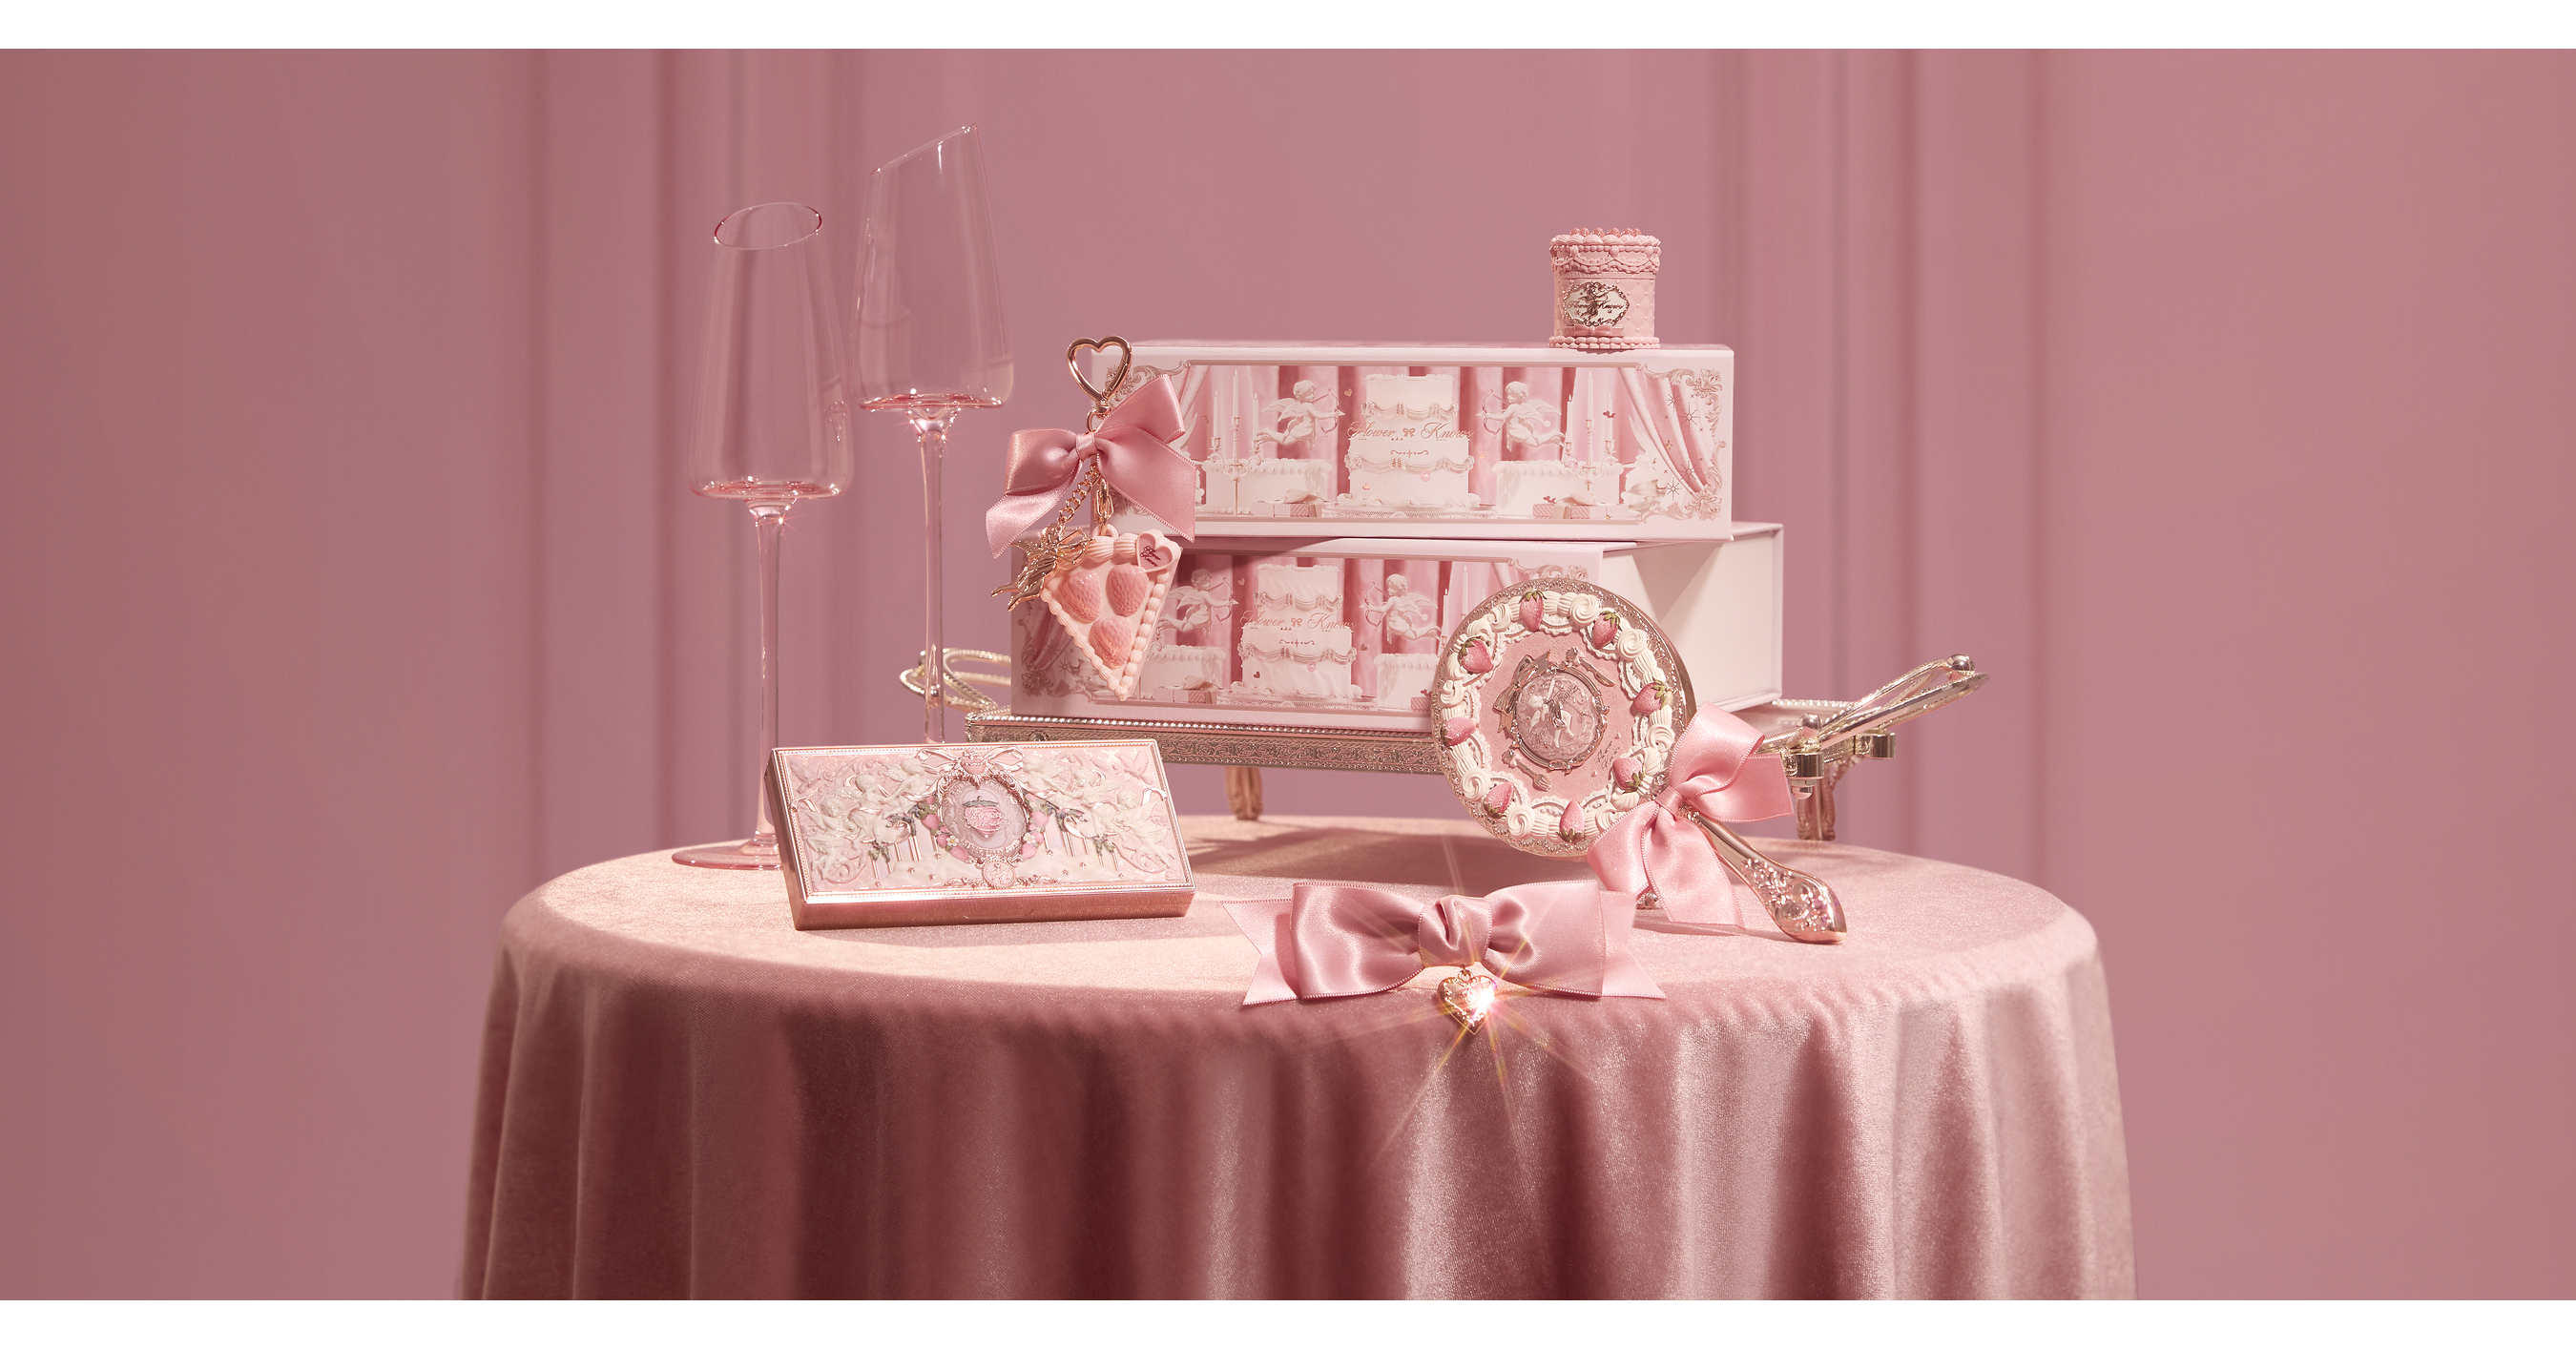
Flower Knows is expanding into 450 Ulta Beauty stores through early 2027 after a successful Ulta.com launch, where its assortment now exceeds 62 products priced from $8 to $45. The C-beauty brand will feature five hero products in Ulta's Just Dropped Beauty platform, launch its Snow Ballet holiday collection, and operate a four-day New York City pop-up in mid-November. The U.S., now Flower Knows' largest overseas market, is a central growth focus as the brand builds physical retail distribution and consumer awareness.
Analysis
This is directionally positive for ULTA's merchandising differentiation, but the financial contribution from a limited, low-SKU rollout is immaterial. The investable signal is whether Ulta can repeatedly convert social-first international brands into store traffic and incremental basket attachment; if successful, it supports a modest mix-driven gross-margin benefit and reduces reliance on promotional legacy prestige brands. The key read-through arrives in holiday traffic, conversion and cosmetics-category commentary over the next 1-3 months rather than from initial door count.
The greater risk is that highly aesthetic, viral color cosmetics produce strong launch sell-through but weak replenishment after novelty fades. Limited distribution also constrains sales impact while creating execution costs through resets, sampling and labor; ULTA needs evidence of incremental visits rather than substitution from existing makeup brands. Watch for management commentary on prestige versus mass cosmetics growth, store conversion, inventory markdowns and holiday gross-margin guidance at the next earnings update.
AMZN and URBN are not meaningful direct beneficiaries. Amazon could eventually gain marketplace demand if the brand's U.S. awareness expands, but direct wholesale availability at Ulta may instead shift higher-intent purchases away from third-party sellers. For Ulta, the more consequential second-order implication is competitive: Sephora/LVMUY and specialty retailers may need to increase their own sourcing of Asian social-commerce brands, raising vendor-acquisition and marketing intensity across color cosmetics over the next 6-18 months.
Contrarian view: the market should not capitalize a single viral-brand placement into ULTA estimates. The upside is not this launch's revenue, but validation of a scalable new-brand pipeline; absent disclosed replenishment velocity or category incrementality, this remains a qualitative merchandising datapoint rather than an earnings catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.50
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the announcement; maintain ULTA only as a watch-list catalyst into holiday results. Upgrade the signal if management cites cosmetics traffic/conversion acceleration or extends the brand beyond its initial placement, which would support a 1-3 month multiple re-rating case.
- For an existing ULTA long, use post-holiday earnings as the decision point: add only if comparable-sales growth and gross-margin guidance improve without higher promotional activity. Falsify the thesis on evidence of incremental markdowns, weakening makeup sell-through, or management framing the launch as traffic-neutral.
- Monitor ULTA versus LVMUY/Sephora-channel proxies over the next 6-18 months for evidence that global, social-native beauty sourcing is becoming a competitive arms race. A sustained ULTA outperformance accompanied by improving cosmetics mix would favor ULTA; isolated viral launches without category growth do not.
- Avoid treating AMZN or URBN as sympathy longs. Their exposure is distributional rather than economically material; revisit only if either retailer announces a broader exclusive assortment or reports measurable beauty-category traffic gains.
More News
- Meta's standoff with Amazon over Muse could be a sign of things to come
- Meta is having a ChatGPT moment with Muse. What is it and what makes it so special
- A rare Microsoft bear warms up to the stock. Here's what changed their mind
- Amazon Blocked Meta's AI Shopping Agent. Shopify Welcomed It -- and Gets Paid on Every Checkout.
- Why McDonald's is following Walmart and Amazon into the advertising business
- One hyperscaler's rally is just getting started, Wolfe Research says
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk
- AI Equity Research Tools for RIAs and Wealth Managers