
Ballard closes acquisition of GeoPura, becoming an integrated hydrogen energy solutions provider
Source: PR Newswire
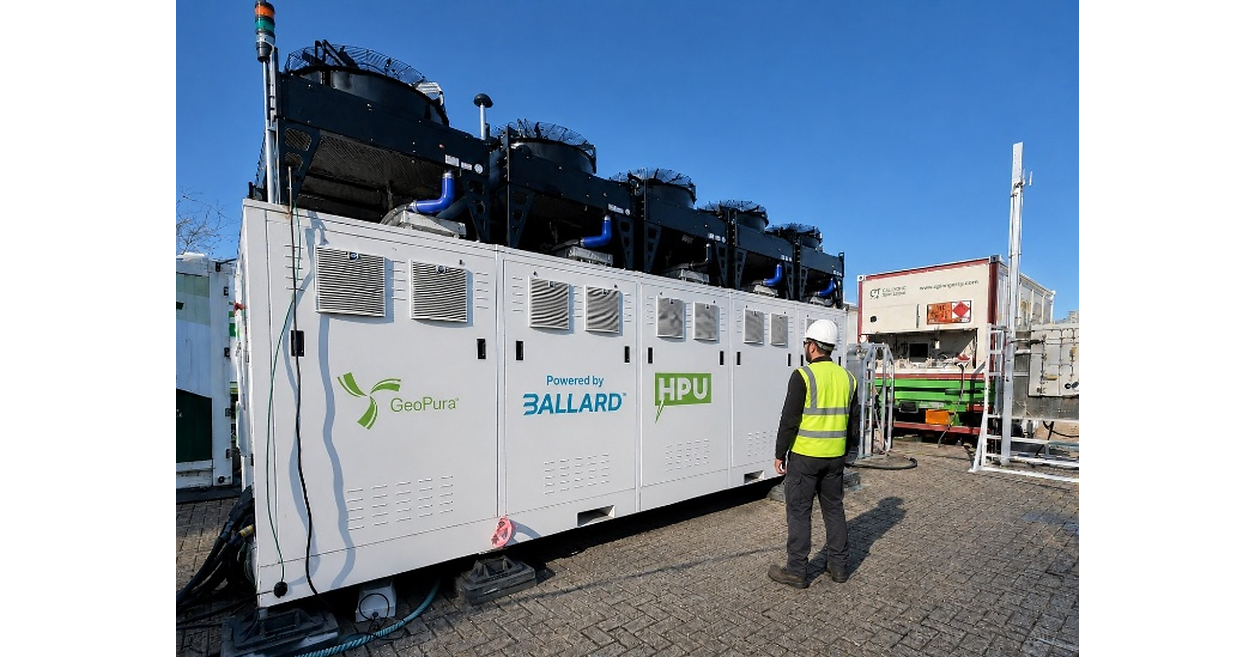
Ballard closed its £275.0M acquisition of UK hydrogen power provider GeoPura to create an integrated hydrogen Energy-as-a-Service (EaaS) platform combining fuel cell technology with HPU deployments, green hydrogen production, and logistics. Consideration includes £82.5M cash, 49,584,212 newly issued Ballard shares/restricted share units (plus additional shares settling over 12 months), and up to £27.5M in contingent post-closing payments. GeoPura shareholders will hold ~14.1% of Ballard on a pro-forma basis, a deal that management says strengthens Europe expansion and enables new North America opportunities.
Analysis
This is less a technology win than a business-model pivot: Ballard is moving from component exposure to owning the messy, capital-hungry middle of the hydrogen stack. That can improve revenue visibility and potentially support a higher multiple, but only if utilization stays high and delivered hydrogen costs do not outrun pricing. In practice, the acquisition increases balance-sheet sensitivity to working capital, fleet capex, and customer project timing, which tends to matter more than stack efficiency in this part of the market.
The immediate beneficiary is Ballard’s credibility with customers that want a turnkey solution; the most direct losers are diesel genset and temporary-power incumbents in premium niches where noise, emissions, or grid constraints justify a higher-cost alternative. PSIX and similar power-equipment names are the cleaner second-order shorts only if the installed base starts to see real substitution, which is a months-to-years story rather than a same-quarter shock. The bigger competitive effect may be internal to hydrogen: this move validates that standalone fuel-cell economics still need an ecosystem wrapper to scale.
Near term, sentiment can lift the stock on ‘vertical integration’ headlines, but the catalyst path is all about disclosure quality: backlog, gross margin, cash burn, and whether GeoPura’s utilization can be replicated outside the UK. The contrarian risk is that investors overpay for the narrative and underprice dilution; if hydrogen project wins do not convert into recurring free cash flow within 1-3 quarters, the market will likely reframe this as an expensive growth purchase rather than a strategic inflection. The thesis is falsified if the next earnings cycle shows no improvement in margin trajectory or if incremental capex/working capital keeps absorbing cash faster than revenue scales.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Do not chase BLDP on the first reaction; if the stock gaps higher, wait for a retracement before considering exposure. The setup is a 1-3 month prove-it trade, not a same-day fundamental rerate.
- If taking risk, use BLDP call spreads expiring after the next two earnings reports to express upside from a successful integration while limiting dilution and execution risk. Risk/reward is attractive only if management starts quantifying margin and backlog lift.
- Relative-value idea: long BLDP / short PSIX only as a small basket if you want to play the niche substitution away from diesel temporary power. The short side is a hedge, not a core conviction short, and should be covered if PSIX shows no hydrogen displacement in order flow or guidance.
- Set an alert on BLDP cash burn and gross margin in the next print; if operating metrics do not improve, fade any post-deal multiple expansion. That is the clearest falsifier of the vertical-integration thesis.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Saudi Arabia says 1 dead, 11 injured in latest attack on Riyadh airport
- Why is LG Innotek stock plunging today?
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Alternative Data Due Diligence for Institutional Investors
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors