
Rockwood Retirement Communities Announces Plans for New Life Plan Community in Liberty Lake, WA
Source: PRWeb
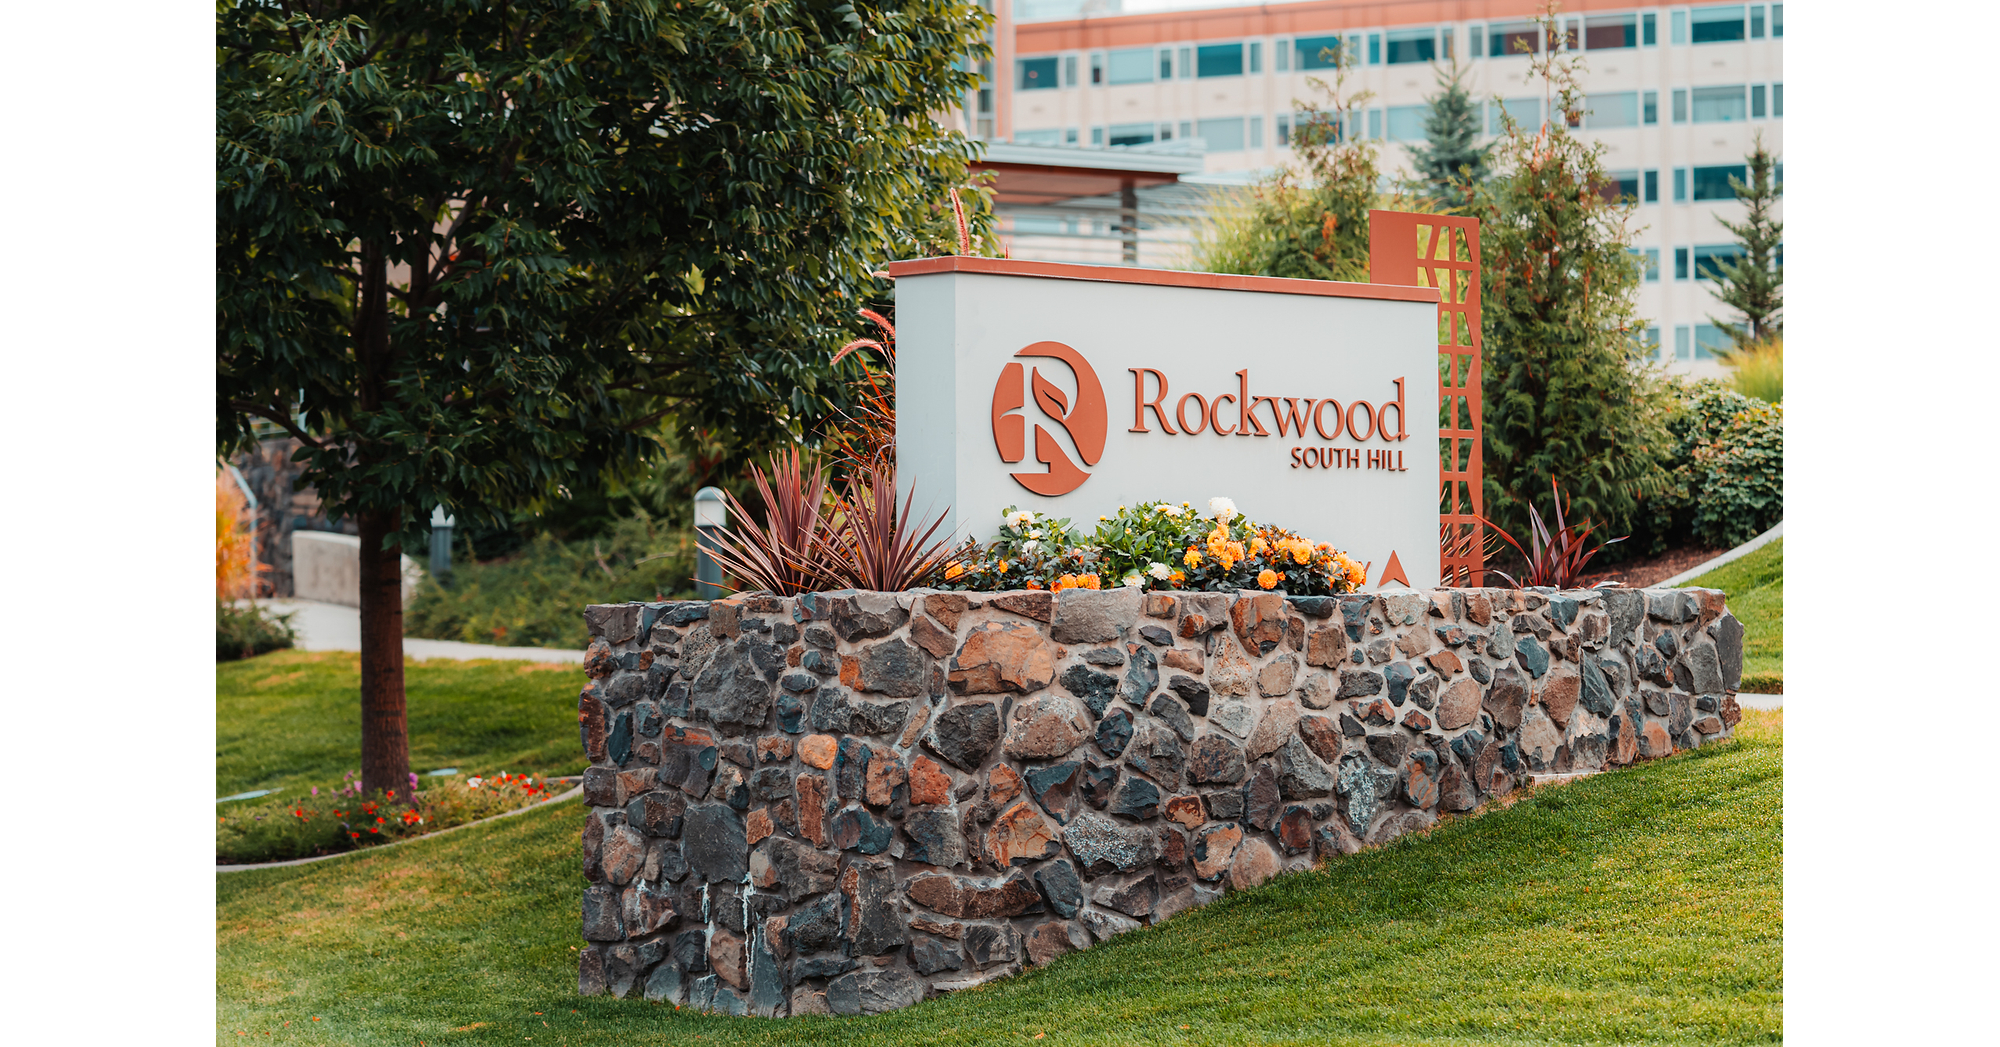
Rockwood Retirement Communities is planning a Liberty Lake, WA senior living campus with 260 total residences (about 200 independent living, 36 assisted living, and 24 memory care) within the River District. The project is expected to cost over $275 million, with due diligence and design underway and construction not anticipated until late 2028, targeting first occupancy in 2030. Management expects the campus to create 100+ full-time jobs and expand access to senior housing and supportive services in the Spokane area, but no immediate financial impact is indicated.
Analysis
This is more a land-option than a financial event. With first occupancy years away, the announcement has little immediate EPS relevance for any public equity; the only real signal is that senior-living developers still believe high-end private-pay demand in the Inland Northwest can absorb a large new asset despite today’s capital cost backdrop. The near-term beneficiaries are private contractors, healthcare staffing, food/service vendors, and local utilities; for public markets, the read-through is mostly that the supply pipeline remains constrained by financing rather than demand.
The second-order risk is that the project becomes a tell on underwriting discipline. If a nonprofit-backed campus of this size can clear financing, it suggests lenders still see durable move-in economics, which is supportive for senior housing sentiment more broadly. If not, the project may never break ground, turning this into a non-event and reinforcing the idea that aging-demographic demand is not the binding constraint—funding is. Over 12-18 months, the key catalyst is rates: lower long-end yields and easier construction financing would materially improve the odds of commencement.
Contrarian takeaway: investors should not extrapolate this into a short thesis on senior housing REITs. One planned campus in a single metro is too small to pressure national pricing, and the long lead time means any competitive impact is likely to be absorbed by regional demographic growth. If anything, this hints that upper-income senior housing still has pricing power, but only when paired with home-sale liquidity and stable financing conditions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No immediate public-equity trade; do not short senior-housing REITs (WELL, VTR, NHI) on this announcement alone. Reassess only if multiple funded projects appear across the region over the next 6-12 months.
- Put WELL on a watchlist for a 1-3 month long entry only if Treasury yields drift lower and broader senior-housing occupancy data remain firm; the upside would come from easier move-in economics, not this specific project.
- If looking for a catalyst-driven pair, consider long WELL / short an overlevered healthcare REIT basket only after actual financing and permitting milestones are disclosed in 2027-2028; until then the setup is too speculative.
- Mark this as a regional supply non-signal unless local vacancy or pre-lease data show a step-up in 2028-2029; that would be the point to revisit competitive pressure on nearby private-pay operators.
More News
- Copper is outshining gold this year. Investors say the rally can survive an AI correction
- 'Cannot play hide and seek': Singapore minister's warning over haze sends agricultural stocks lower
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Elice shares plunge 28% on debut as investor doubts over AI trade deepen