
Red Sea Global et le groupe médical du Dr Sulaiman Al Habib inaugurent l'hôpital Red Sea
Source: PR Newswire
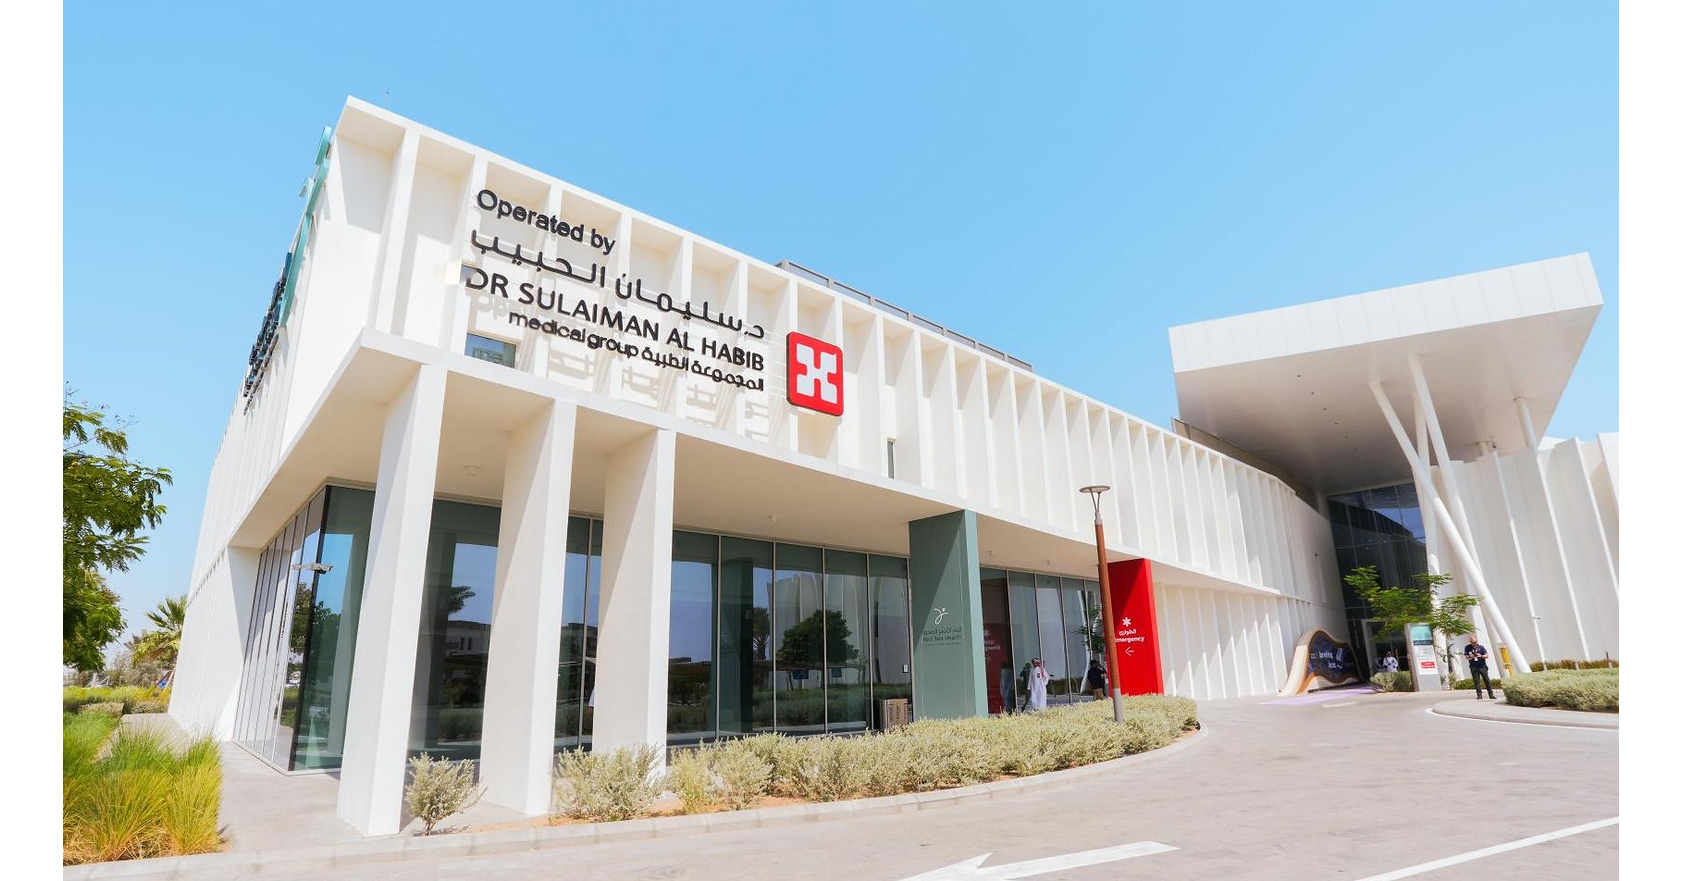
Red Sea Global and Dr. Sulaiman Al Habib Medical Services Group inaugurated The Red Sea Hospital in Saudi Arabia, establishing a central clinical facility for RSG's integrated Red Sea Health ecosystem. The hospital provides emergency, inpatient, outpatient, specialist, surgical and digital-health services, with the broader network planned to include six pharmacies and dedicated emergency medical transport. The development supports Saudi Vision 2030 and the expansion of RSG's Red Sea tourism destination, which currently has 11 operating hotels and expects six additional Shura Island resorts to open in coming months.
Analysis
For HMG (TADAWUL:4013), the economic question is not the opening-day revenue contribution but whether this becomes a replicable asset-light operating model for Saudi giga-projects. A remote, premium-destination hospital can carry structurally lower utilization and higher staffing/logistics costs during the resort ramp; unless the contract includes minimum-revenue guarantees, management fees, or pass-through staffing economics, it could dilute consolidated margins before visitor and employee density matures. The market should demand disclosure on bed capacity, ownership/capex responsibility, fee structure, and any RSG volume guarantee before assigning material value.
The second-order benefit is strategic: demonstrated capability in digitally connected emergency care and medical transfers may strengthen HMG's bid credibility for future NEOM, AMAALA, and other Vision 2030 developments. That favors HMG over domestic listed peers Mouwasat (4002), Dallah Healthcare (4004), and Care Medical (4005) only if the agreement creates a pipeline rather than a one-off branding arrangement; otherwise, those peers retain more attractive exposure to dense urban catchments and established utilization. Suppliers of hospital equipment, pharmacy, and medical staffing may see incremental contracts, but the project is too small in isolation to move earnings for diversified global vendors.
Near term, this is likely narrative-positive rather than an earnings catalyst. Over 1-3 months, the relevant trigger is HMG's next results call: confirmation of contract economics, startup losses, and additional destination-health mandates could support a multiple premium; silence or evidence of fixed-cost absorption would reverse the effect. Over 6-18 months, tourism occupancy and resort-opening cadence—not clinical demand alone—will determine whether the facility reaches efficient utilization.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain a watch, not a new directional position, in HMG (4013) until management discloses revenue recognition, capex ownership, capacity, and minimum-volume protections. Upgrade only if contract economics are fee-based or guaranteed and management identifies follow-on destination contracts.
- For Saudi healthcare exposure, favor a conditional pair: long HMG (4013) / short Mouwasat (4002) only after evidence of a broader giga-project pipeline. Target a 6-12 month horizon; exit if HMG guides to startup-margin dilution without contractual reimbursement or if no additional mandates emerge by the next two earnings reports.
- Monitor HMG's EBITDA margin and new-facility ramp commentary at the next earnings release. A margin decline attributable to remote-site staffing and low utilization is the clearest falsifier of the strategic-premium thesis and would favor urban-focused peers such as Dallah (4004) and Care Medical (4005).
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Here's who we know is going to the Trump-Xi dinner so far
- UK to refuel Saudi jets to help counter Houthi attacks
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Portfolio Monitoring: Build an Alert Policy Analysts Can Audit
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)