
Wheaton Precious Metals Targets 50% Production Growth by 2030 Without New Capital
Source: marketbeat.com
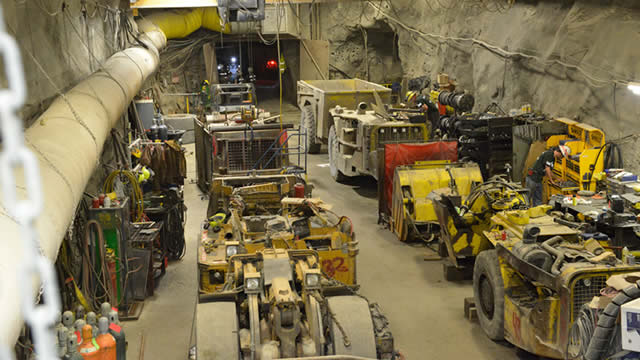
Wheaton Precious Metals outlined a 2026 Investor Day strategy focused on selective precious-metals stream acquisitions and contract terms designed to retain upside while limiting downside risk. Management said its production growth outlook through 2030 can be achieved without additional capital deployment, supporting a capital-efficient growth narrative.
Analysis
The investable implication is less the growth target than the funding structure: WPM can compound metal-linked cash flow without taking operating-cost, capex-overrun, permitting, or labor-inflation risk borne by mine operators. That makes its earnings quality relatively more valuable if gold/silver remain elevated while miners face rising sustaining-capital requirements. The trade-off is that WPM's upside is partly capped by fixed stream terms, so a broad precious-metals melt-up may still favor higher-beta producers such as AEM, NEM, PAAS, and FNV/RGLD depending on the metal mix.
Over the next 1-3 months, the key catalyst is whether management translates the strategy into a transaction pipeline at returns that are accretive after financing costs; absent disclosed asset-level economics, Investor Day language alone should not justify a material rerating. A higher valuation multiple is sustainable over 6-18 months only if production delivery, counterparty mine ramp-ups, and reserve-life replacement validate a low-risk growth profile. The principal downside is not direct cost inflation but partner-asset underperformance, delayed mine construction, or an acquisition made near a cyclical peak in metal prices.
Consensus may underappreciate WPM as a scarcity vehicle for diversified precious-metals exposure with limited operational execution risk, particularly if investors rotate away from capital-intensive miners. Conversely, that defensive premium can become fragile if real yields rise or gold weakens: WPM retains commodity-price sensitivity but lacks the operational leverage that can drive producer outperformance in a sustained bull market.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long WPM versus short GDX over a 3-6 month horizon if the objective is precious-metals exposure with lower mine-operating risk; reassess if WPM materially underperforms GDX following the next earnings release or if management cannot identify an actionable acquisition pipeline.
- Use WPM as the lower-beta leg of a long WPM / short NEM pair into periods of expected cost-inflation or permitting scrutiny; target a 5-10% relative return, with a stop if gold rises sharply while NEM's operating guidance improves, since producer operating leverage would then dominate.
- Do not chase an Investor Day-driven move without transaction details. Set an alert for any new stream acquisition and underwrite purchase price, expected ounces, counterparty concentration, and financing source before increasing exposure; equity issuance or low-return deployment would falsify the capital-discipline thesis.
- For a bullish 6-12 month gold view, prefer WPM shares over near-dated calls: the missing inputs are implied volatility, strike pricing, and timing of transaction catalysts, while shares preserve exposure to both metal prices and potential deal-driven NAV accretion.
More News
- Companies promised AI gains— here's how the payoff showed up in earnings
- FBI blames North Korea for record $6.3bn crypto heist
- Binance to resume crypto withdrawals in phases after record $6 billion hack
- China sees the yuan vs. dollar rivalry like Pepsi vs. Coke, expert says — ‘never the market leader, but serviceable in a pinch’
- AWS grows 39% and Amazon will spend even more on AI in 2027
- SpaceX loses bid to toss NAACP lawsuit over Memphis data center air pollution