
KIA'S FAMILY OF HYBRID SUVs AND UTILITY VEHICLES CREATE THE BEAT OF A CITY IN NEW CREATIVE CAMPAIGN
Source: PR Newswire
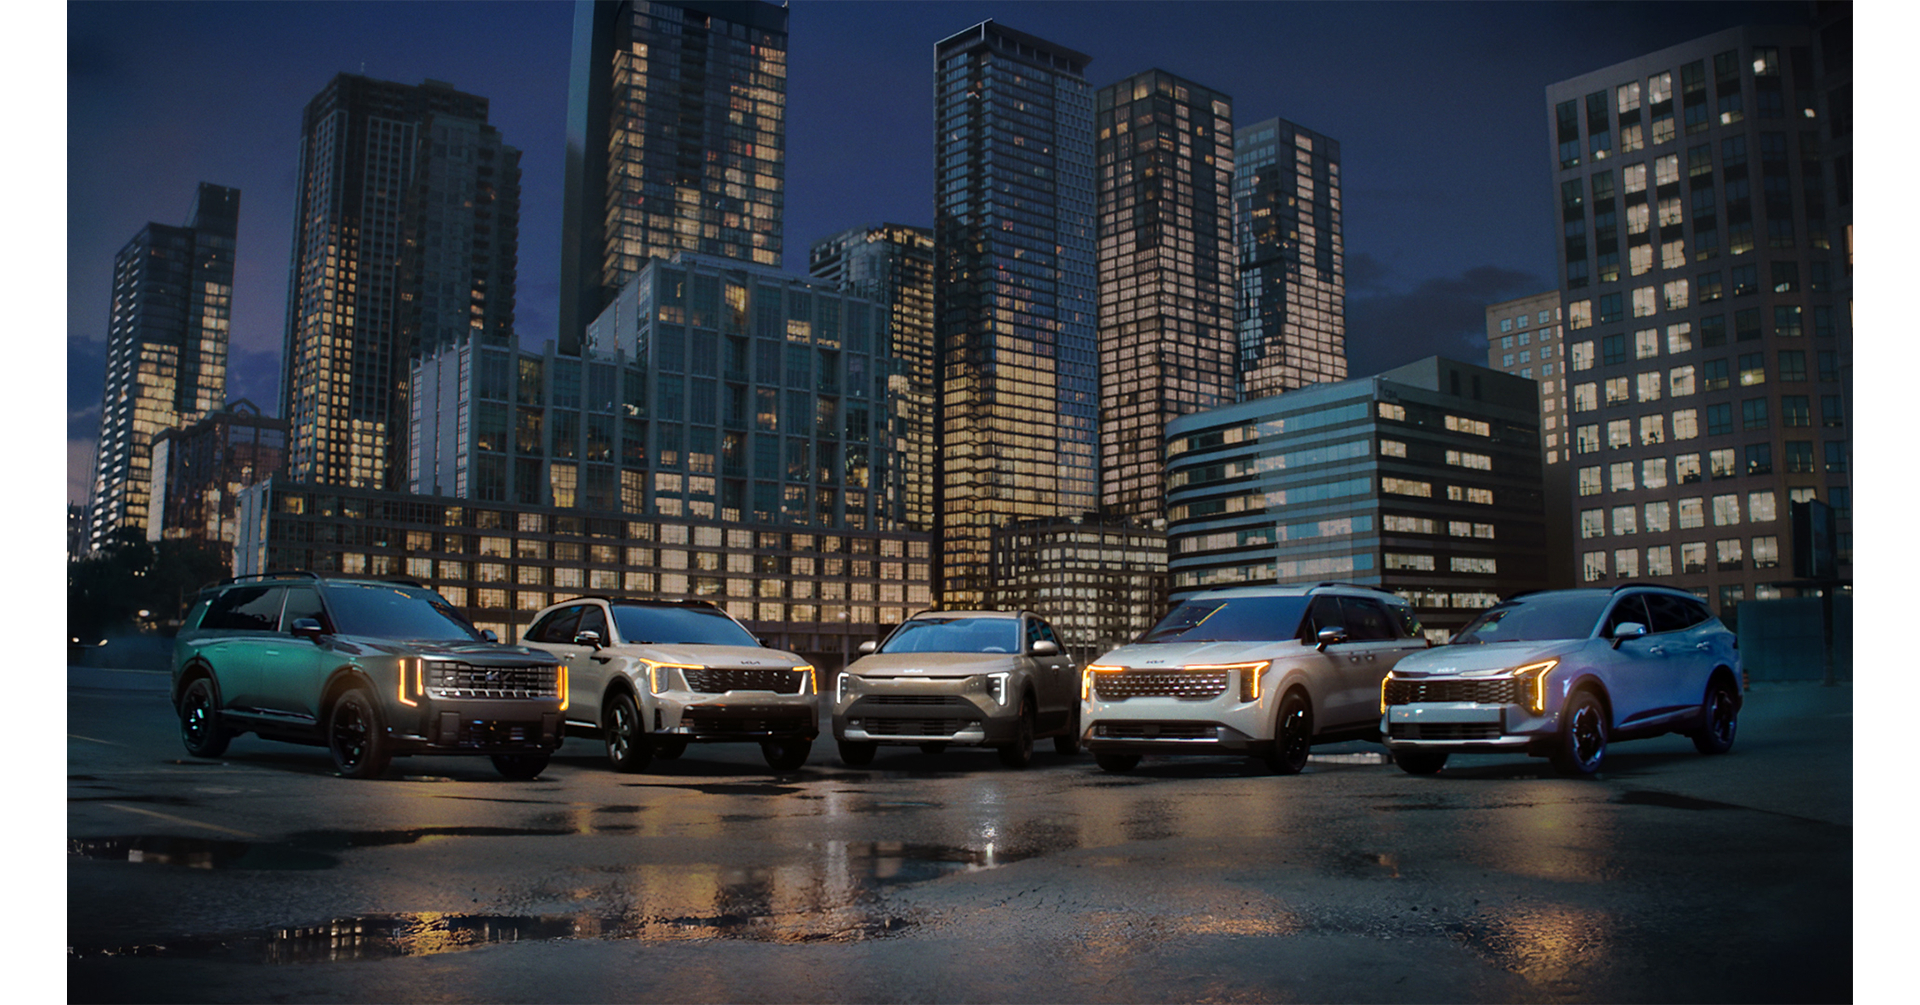
Kia America launched its "Hybrids That Move to a New Beat" marketing campaign to promote its hybrid SUV and utility lineup, including the 2027 Telluride, Sportage and Carnival. The campaign highlights the Telluride Turbo-Hybrid's 329 hp and 564-mile total range, alongside the Carnival Turbo-Hybrid's 608-mile total range. The 360-degree effort spans broadcast, print, digital, out-of-home and social media, but contains no sales, pricing, production, or financial guidance updates.
Analysis
This is advertising spend rather than a disclosed production, pricing, order, or guidance event; it is not independently evidence of incremental demand. Kia is privately held through Hyundai Motor Group, while CCL is Carnival Corp. and has no apparent economic linkage to Kia's Carnival-branded vehicle, so the supplied ticker signal should be disregarded.
The more relevant read-through is competitive: a broad hybrid push in high-volume utility segments raises pressure on Toyota (TM), Honda (HMC), Ford (F) and GM (GM) to defend hybrid mix and transaction prices before full-EV adoption normalizes. Hyundai Motor (HYMTF) could benefit only if dealer inventory turns and hybrid mix rise without incentive escalation; otherwise incremental media spending merely shifts share within a constrained hybrid-component supply base. Suppliers with exposure to hybrid powertrains, including BorgWarner (BWA) and Denso (DNZOY), would need production schedules—not campaign reach—to support an earnings inference.
Over the next 1-3 months, monthly U.S. sales, days' supply, incentive per unit, and hybrid transaction-price data are the relevant catalysts. A positive thesis is falsified if Kia/Hyundai hybrid inventory rises while incentives accelerate, indicating demand is being bought rather than organically expanded; sustained gasoline-price weakness would further reduce hybrid payback appeal. Over 6-18 months, the structural risk is that hybrid capacity allocation crowds out battery-electric launches or compresses margins through more expensive powertrains without adequate pricing.
Contrarian view: the market may be too quick to treat hybrid marketing as a clean anti-EV signal. Hybrids can be margin accretive during a transition period, but only where OEMs control component availability and preserve pricing; Toyota's established scale gives it a stronger cushion than late-cycle entrants. No standalone trade is warranted from this release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No action in CCL: remove it from any event-driven basket for this item; there is no identifiable revenue, demand, or supply-chain connection.
- Place HYMTF on watch for the next two monthly U.S. sales releases: consider a tactical long only if hybrid unit growth exceeds overall brand growth while incentive spend remains stable or lower year over year. Exit on rising hybrid days' supply or a material incentive increase; this is a data-dependent alert, not a current recommendation.
- For autos exposure, prefer TM over F and GM on a 6-12 month basis if hybrid demand continues to outpace EV demand: Toyota has greater hybrid scale and lower execution risk. Reassess if U.S. gasoline prices fall materially or Toyota hybrid dealer inventories normalize above industry levels.
- Monitor BWA and DNZOY around quarterly guidance for hybrid-powertrain volume commentary. Do not initiate on campaign news; upgrade only on verified OEM build-rate increases and margin-accretive hybrid content guidance.
More News
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Google's Gemini 4 Carbon looks like a diamond in the rough
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- As Waymo expands overseas, it remains a niche cash-burning business
- Peltz’s Trian Offers $1.4 Billion for Wendy’s, WSJ Reports
- Fed chairman talks tough on inflation — plus, what's behind Micron's big rally