
Industry Veteran Bana Qashu Joins ARG Team as Part of Acquisition of Certain BanaTech Consulting Assets
Source: PRWeb
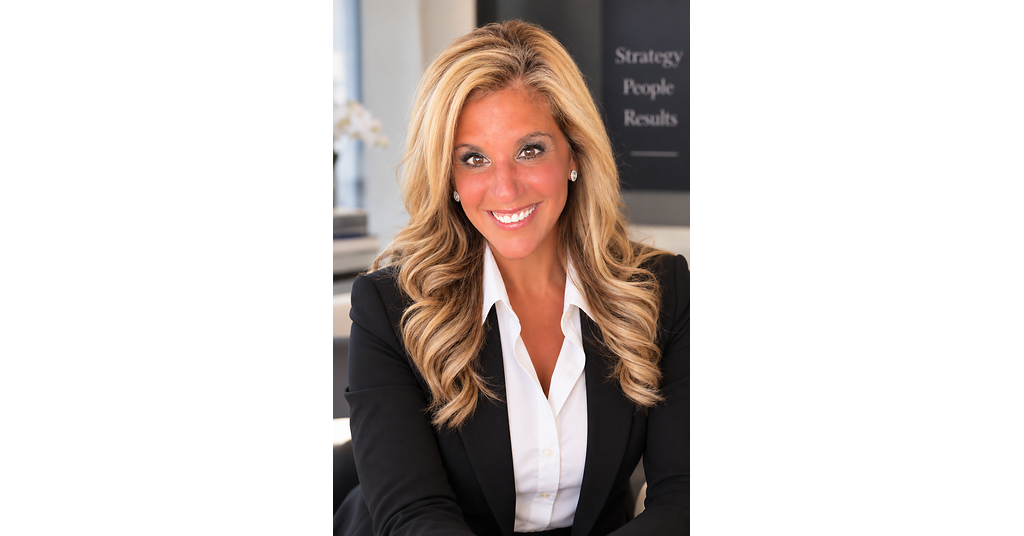
ARG appointed technology-channel executive Bana Qashu as Vice President of Marketing & Strategic Growth, consolidating responsibility for marketing, business development, strategic partnerships and national expansion initiatives. The company also acquired certain assets of Qashu's BanaTech Consulting, founded in 2025, to support its expanded advisory capabilities. The moves follow Bear Creek Partners' strategic investment and are intended to strengthen ARG's leadership and infrastructure for organic and inorganic national growth.
Analysis
This is not a public-markets catalyst: ARG and its sponsor appear private, and the announcement provides no revenue, client-retention, purchase-price, or pipeline metrics with which to underwrite a change in enterprise value. The acquisition of a founder-led consulting asset is more likely an acqui-hire than a material roll-up; any near-term value creation depends on converting channel relationships into recurring advisory revenue rather than merely expanding executive capacity.
The more relevant read-through is for the fragmented technology-advisory/channel ecosystem. Sponsor-backed platforms that consolidate advisor distribution can gain supplier bargaining power and improve lead economics, potentially pressuring independent agencies and smaller technology-services brokers over 6-18 months. Public beneficiaries are indirect and low-beta: large channel vendors and distributors such as AVT and TD SYNNEX (SNX) could see incremental enterprise technology demand only if advisory-led project origination accelerates broadly, but this isolated personnel event is immaterial to their estimates.
Consensus risk is assigning strategic significance to relationship capital before validating monetization. Referral partnerships often produce long sales cycles, weak attribution, and revenue-sharing that can dilute gross margin; national expansion also raises integration and fixed-cost risk ahead of scale. A credible re-rating catalyst for the private platform would require disclosed advisor productivity, supplier attach rates, recurring-revenue mix, or a subsequent institutional financing/transaction at a marked-up valuation—not additional leadership announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional public-equity trade warranted; impact is below the threshold for an actionable estimate revision in AVT, SNX, or broad IT-services/channel proxies.
- Monitor private-market signals over the next 6-12 months: a disclosed ARG acquisition, financing, or customer/supplier partnership with contract economics could establish whether this is a scalable consolidation platform rather than an acqui-hire.
- For any future channel-consolidation thesis, require evidence that incremental referral revenue exceeds added sales-and-marketing expense within two quarters; absent that evidence, treat national-expansion claims as margin-risk rather than growth upside.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Paramount will need to release way more movies to make this merger work
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data
- Best AI Stock Research Tools for Professional Investors