
CME Group Sets New FX Open Interest Record
Source: PR Newswire
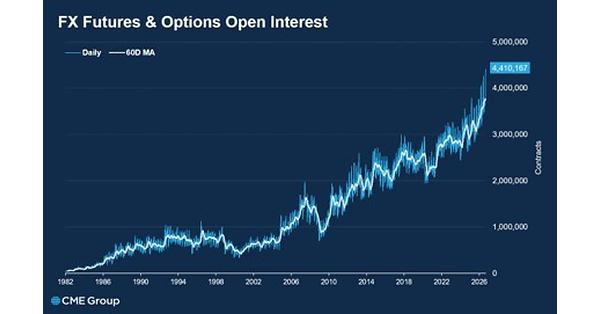
CME Group's FX futures and options open interest reached a record 4,410,167 contracts on September 4, surpassing the prior 4,269,622 record set on June 11. Large FX futures holders rose to an all-time high of 1,446, while asset-manager FX futures notional open interest exceeded $200 billion for the first time. The data signals strengthening institutional demand for centrally cleared FX derivatives and CME's risk-management products.
Analysis
The investable signal is not the headline level of contracts but the evidence of institutional migration from bilateral FX execution toward cleared listed products. That shift is structurally favorable to CME because clearing, collateral optimization and workflow integration create higher switching costs than a one-off volume surge; it also gives CME cross-sell opportunities in rates, equity-index and options products. The near-term earnings contribution is likely modest unless average daily volume and realized FX revenue per contract remain elevated through quarter-end, but sustained participation can support a higher quality-of-growth multiple over the next 6-18 months.
The key ambiguity is whether positioning reflects durable hedging demand or a temporary macro-volatility event. Elevated open interest without corresponding turnover can be balance-sheet efficient hedging rather than incremental transaction revenue, while a rapid decline in implied FX volatility could unwind activity without materially damaging CME's franchise. Competitive pressure should be monitored at ICE, LSEG's FXall/Refinitiv ecosystem and OTC dealer platforms: a persistent listed-market share gain matters more than aggregate contracts.
Consensus may underappreciate the margin leverage if FX growth is incremental to existing clearing and technology capacity. Conversely, the press release provides no contract-mix, ADV, options penetration or net fee-rate data; absent those, this is not sufficient evidence to revise earnings materially. The most useful confirmation will be CME's next monthly volume report and management commentary on FX average rate per contract, block-trade mix and customer retention.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long CME on weakness rather than chase a press-release move; use a 1-3 month horizon into the next volume update/earnings. Upgrade sizing only if FX ADV remains above the prior-quarter run rate and total revenue per contract is stable or rising, indicating monetizable flow rather than passive open-interest accumulation.
- Pair trade watch: long CME / short ICE only after evidence that CME is taking listed FX share for two consecutive monthly reports. The thesis is superior clearing-led growth and operating leverage; invalidate if ICE's transaction-and-clearing growth accelerates while CME FX ADV normalizes.
- Do not treat EBS as an independent public-equity beneficiary; it is part of CME's broader FX ecosystem. Track whether futures growth is accompanied by cash/OTC FX connectivity gains, which would strengthen the platform narrative but may also signal internal channel substitution rather than entirely incremental revenue.
- Set a downside trigger for CME longs at the next earnings release: reduce exposure if management identifies lower FX realized rates, declining options participation, or an FX-volume reversal while market volatility remains elevated. That combination would imply competitive or product-mix deterioration rather than a macro normalization.
More News
- The perfect storm behind the Nasdaq's rout — plus, some of the bright spots in the market
- The Federal Reserve's Latest October Inflation Forecast Has Arrived, and It's Terrible News for Wall Street
- Emerging credit risk: What could take out the AI trade
- Japan manufacturing growth slows to 7-month low in October, PMI shows
- France is flashing euro crisis signals. This time, the fault lines are different
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs