
UK Asylum System Tests Burnham’s Push for More Public Control
Source: Bloomberg
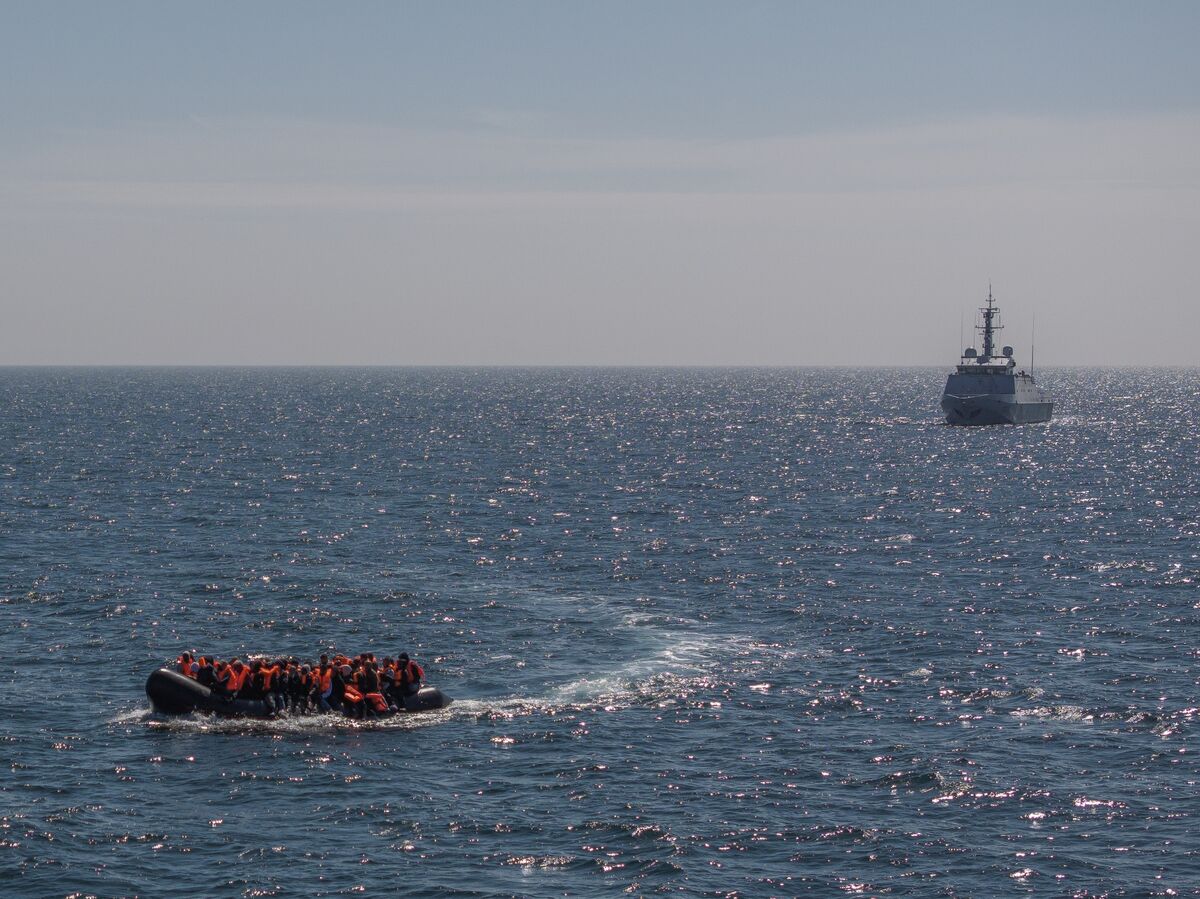
UK plans are framed around Andy Burnham’s push to reduce private-sector control over public services, with the asylum system as the key test case. The UK asylum system is estimated to cost £4.9B ($6.6B) in 2024-25, mostly for accommodation and support while asylum applications are assessed, and multiple contractors (including MTC Group, Clearsprings Ready Homes, and Mitie) play dominant roles. Potential shifts in contracting or oversight could create operating and governance uncertainty for the involved service providers.
Analysis
This is more of a policy-multiple story than an earnings story. For MITFY, the direct asylum-related revenue pool is too small to justify a fundamental de-rating on its own, but UK outsourcing names can trade on headline risk because investors extrapolate one politically charged contract into a broader repricing of government services exposure. The immediate move is likely sentiment-driven; the real question is whether procurement teams start demanding shorter duration, lower-margin renewals across adjacent contracts.
The second-order winner from a push toward public control is not necessarily the state, but the private incumbents that are less exposed to politically sensitive work and can rotate toward harder-to-replace facility management or technical services. The loser set is any contractor with opaque UK public-sector margins, because a policy campaign raises bid friction and can force concessionary pricing even before any contract is lost. If insourcing talk gains traction, expect a wider UK outsourcing discount rather than isolated downside in asylum-specific operators.
Contrarian view: full public control is operationally expensive and slow, so the market may be overestimating how quickly policy can displace private capacity. The near-term catalyst path is speeches, party platforms, and spending reviews; the 6-18 month risk is contract churn and lower margin on renewals, not an overnight revenue cliff. The thesis breaks if the government reframes the issue as reform-with-contractors rather than insourcing, or if MITFY’s next update shows no sensitivity in UK public-sector bid win rates or margin commentary.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.12
Ticker Sentiment
Key Decisions for Investors
- Small tactical short MITFY on policy-headline rallies over the next 1-3 months; target a 10-15% downside from UK outsourcing multiple compression, but cover if official guidance explicitly preserves private delivery or if renewal commentary stays constructive.
- Use MITFY puts only as a catalyst trade after a concrete policy proposal or spending-review milestone; avoid pre-positioning because implementation risk is high and theta decay will dominate if the issue stays rhetorical.
- Do not force exposure in BURCP or TGT; BURCP is a political catalyst rather than a clean equity expression, and TGT has no meaningful read-through to UK asylum procurement.
More News
- FBI says an OpenAI engineer used his wife’s AI chatbot to figure out how to plant a secret recording device at the office
- The best banks for personal loans in 2026
- Bending Spoons Stock Soars on Berkshire’s Increased Stake
- Travis Kelce joined an activist group pushing Six Flags to consider a sale. The ‘Final Destination’-style death of a patron poured gas on the fire
- ‘The biggest financial institutions are not above the law’: Bessent hits BofA with $1.2 billion fine for money laundering—the third-largest in history
- Merck CEO tells CNBC he expects breakthrough cancer vaccine will become faster to make