
Tom's of Maine Introduces Hydroxyapatite Toothpaste to Meet Rising Consumer Demand
Source: PR Newswire
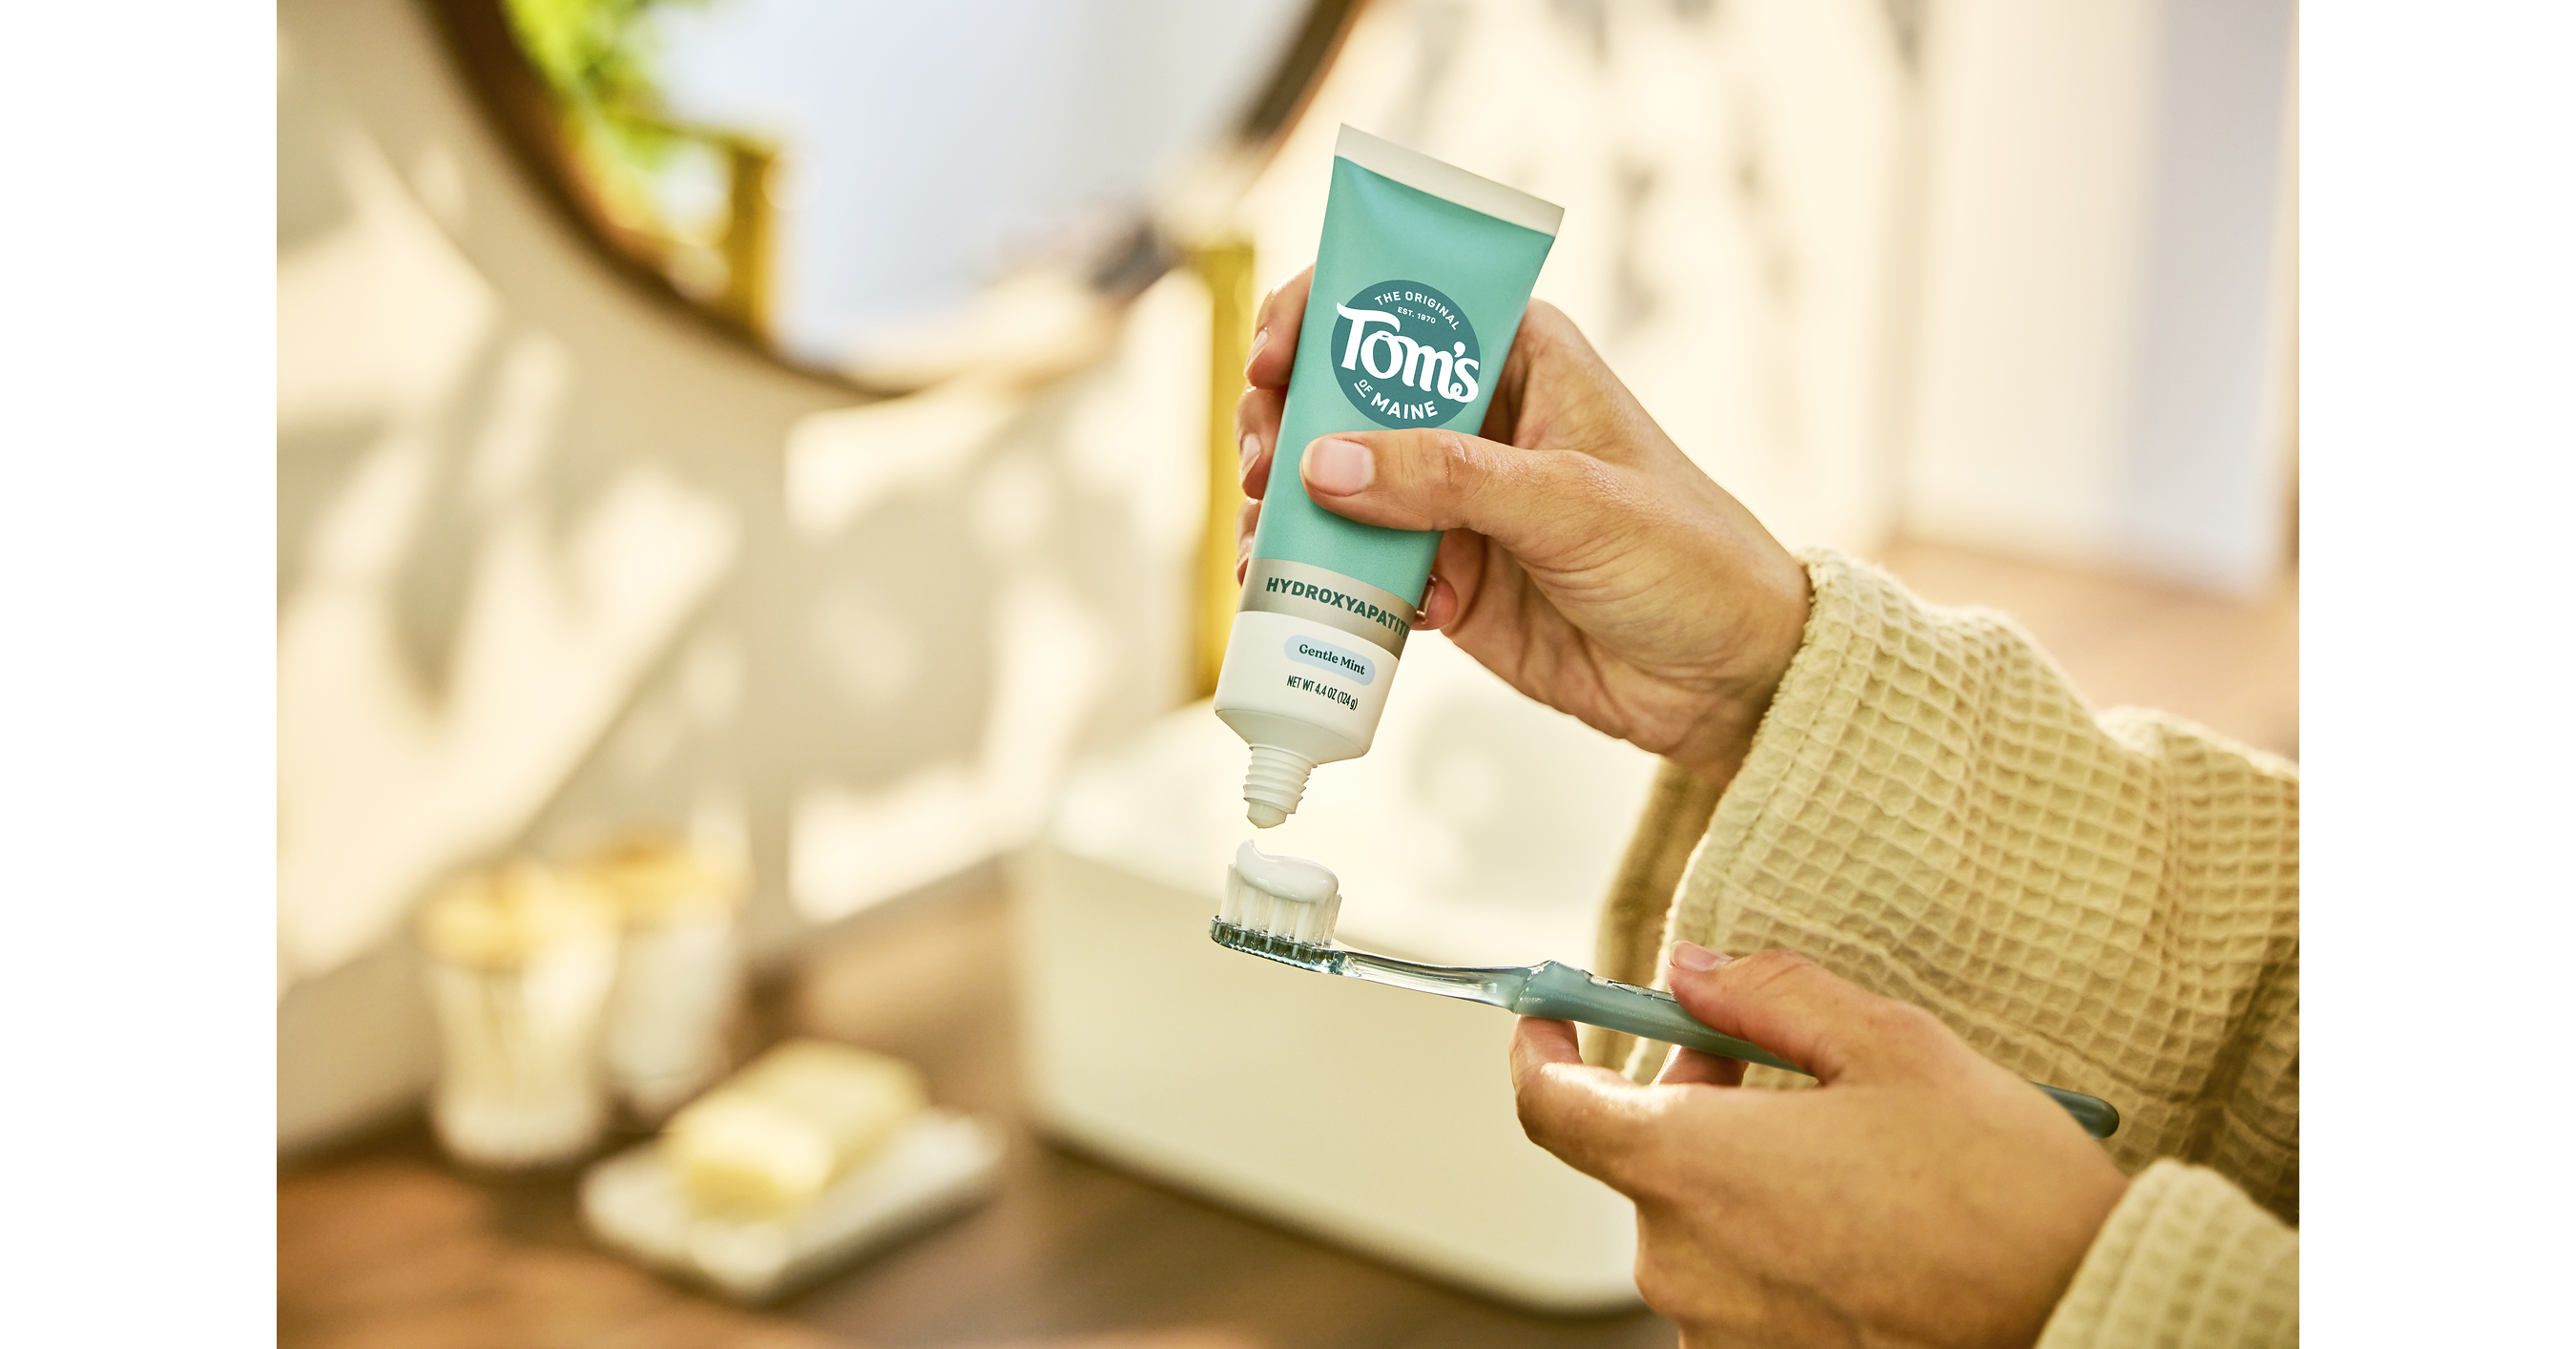
Colgate-Palmolive subsidiary Tom's of Maine launched a fluoride-free hydroxyapatite toothpaste priced at $11.99 for a 4.4-ounce tube, targeting demand for natural oral-care and sensitivity-relief products. The vegan, SLS-free product is initially available on Amazon, with broader retail distribution planned for 2027. The launch modestly expands Tom's natural-care portfolio but is unlikely to materially affect Colgate-Palmolive's near-term financial results.
Analysis
This is strategically more relevant to CL’s category architecture than to near-term earnings. Hydroxyapatite gives Tom’s an entry point into the premium, efficacy-led “fluoride-free” segment, where consumers are willing to accept materially higher unit pricing and where shelf placement is increasingly contested by privately held brands such as Boka, RiseWell and David’s. If repeat rates validate sensitivity relief claims, CL can use Amazon velocity to negotiate conventional retail distribution in 2027, potentially improving Tom’s mix without meaningful incremental brand-building spend.
The near-term financial contribution is immaterial relative to CL’s oral-care base, and the launch should not change estimates over the next 1-3 months. The relevant KPI is not initial Amazon rank but subscription penetration, review quality around sensitivity efficacy, and whether the product cannibalizes existing Tom’s SKUs versus taking share from premium natural incumbents. A weak consumer response would expose the limitation of “natural” positioning when clinical efficacy, rather than ingredient avoidance, drives repurchase.
The contrarian read is that the fluoride-free trend is fragmented rather than a broad replacement cycle: dental-professional endorsement remains a meaningful barrier to mainstream adoption, particularly for cavity-prevention claims. CL’s advantage is distribution and manufacturing scale, but a successful premium niche may be more disruptive to smaller natural oral-care brands than to PEP’s/PG’s mass-market portfolios. The structural upside for CL comes only if the platform broadens into a credible enamel-health franchise over 6-18 months, not from a single SKU launch.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No standalone CL trade on this announcement; maintain existing core exposure only. The expected revenue contribution is too small to affect the next 1-3 months of consensus estimates or valuation.
- Set a 6-12 month monitoring trigger on Amazon: sustained top-tier category ranking, strong sensitivity-related reviews, and subscription/reorder penetration would support a modest positive mix thesis for CL ahead of broader retail rollout.
- Watch 2027 retailer assortment data and CL organic-sales guidance. Incremental distribution accompanied by stable Tom’s pricing would validate premiumization; promotional intensity or evidence of cannibalization would falsify the margin-upside case.
- For a relative-value expression only after verified traction, favor long CL versus a consumer-staples basket rather than short PG: CL has greater strategic leverage to premium natural oral care, while PG’s oral-care exposure is less central to the fluoride-free niche.
More News
- CoreWeave seeks truce with Texas Governor-elect Hinojosa
- These funds tout hefty income tied to the tech trade – if you’re willing to deal with the complexity
- Street Calls of The Week
- Meta’s $25 Billion Bond Sale Highlights Shifting Landscape for Tech Debt
- Binance CFO exits days after catastrophic $6 billion crypto hack
- Coffee giant Dutch Bros made all of its executives, including the CEO, do a two-week bootcamp where they learned how to pour drinks and run stores